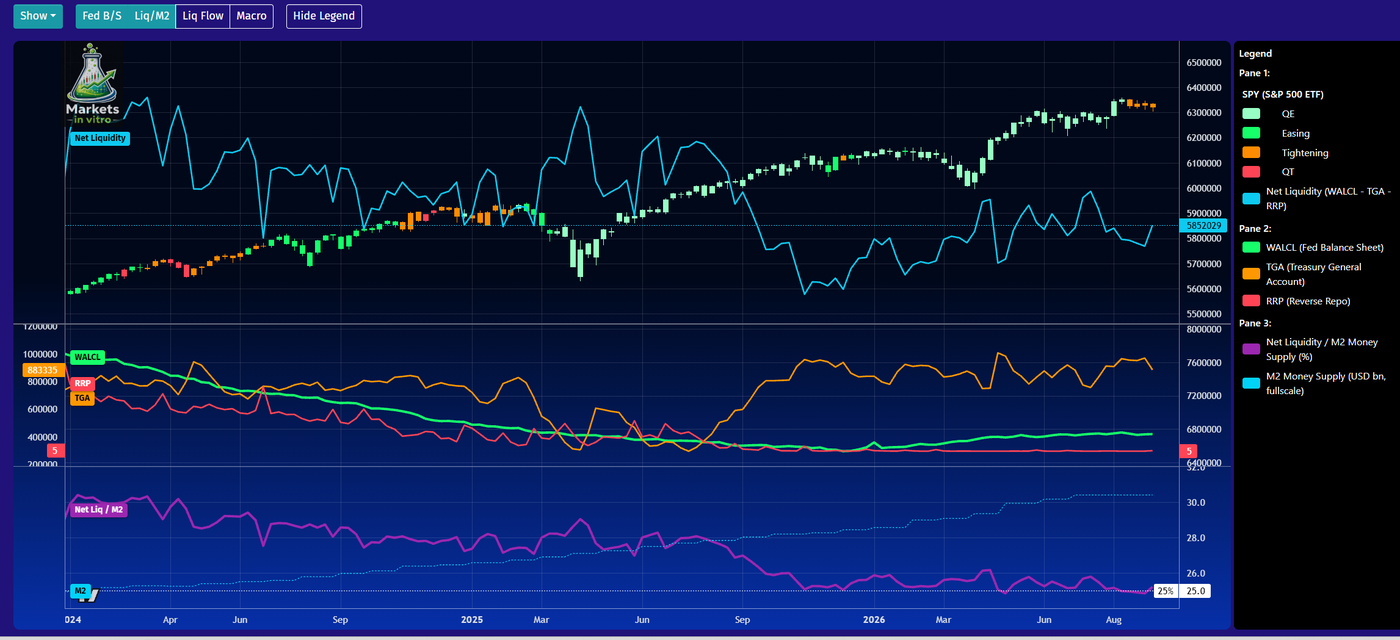
The FED has already started tightening, about 4 weeks ago, according to our model, which takes into account several observables, such as the Total FED assets (WALCL), the Treasury General Account (TGA), Reverse Repurchasing Activities (RRP), the US Dollar and the FED Funding rate. Since August, the total FED assets declined by roughly -0.3%. Not a huge number, but the message sent out this way gives rise to concerns among investors.
4 weeks ago the model shifted from Quantitative Easing to Tightening
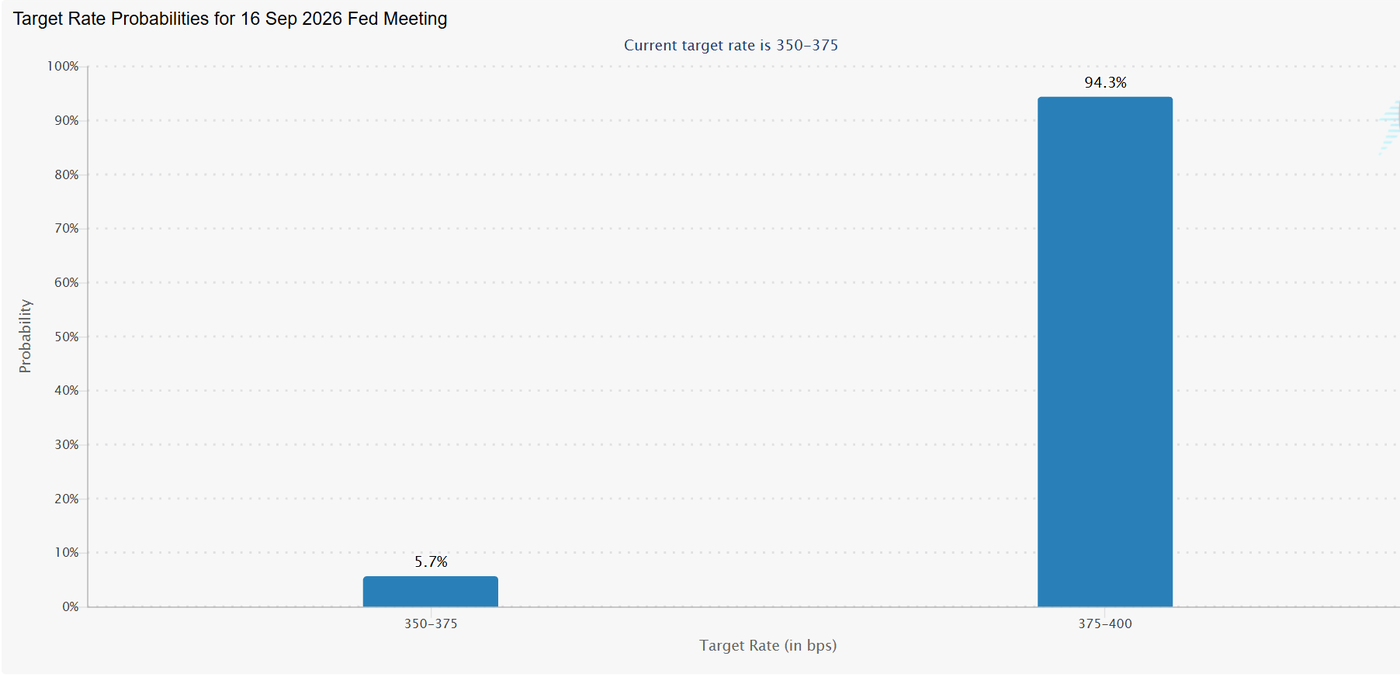
The main event is expected this week, at the FOMC decision on Wednesday 2:00 pm ET. Markets are almost certain of a +25 bp rate hike, with a 95% chance, according to the CME FED Watch Tool.
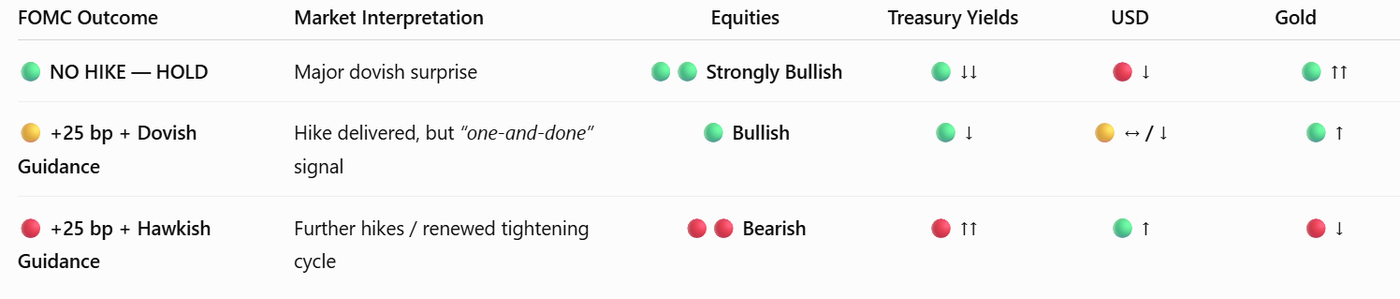
The most logical market reaction to the FOMC decision can be summarized as follows:
Key takeaway: With a +25 bp hike already >90% priced in, the hike itself is unlikely to be the main market mover. The forward rate path, Powell's guidance, and especially the reaction of long-term Treasury yields will matter much more.
With a 25 bp hike already largely priced in, markets will focus primarily on the Fed’s guidance and the future rate path. A) 🟢 No Hike / Hold: A dovish surprise. Equities, Treasuries, gold, silver, crypto and REITs should rally as expected rates and real yields fall. The USD would likely weaken, supporting commodities and emerging markets. Oil may remain driven primarily by geopolitical supply risks. B) 🟡 25 bp Hike + Dovish Guidance: Potentially the most bullish outcome. The Fed delivers the expected hike but signals limited further tightening. Equities and crypto could rally, Treasury yields and the USD fall, while gold and silver rise. Stable or tighter credit spreads would reinforce the risk-on signal. c) 🔴 25 bp Hike + Hawkish Guidance: The main risk-off scenario. Expectations of further hikes would push yields, real rates and the USD higher, pressuring equities, bonds, gold, silver, crypto, REITs and high-yield credit. Cyclical commodities such as copper could weaken, while oil may remain supported by supply risks.
Key signal: A hike with falling 10Y yields and stable credit spreads = bullish. Rising 10Y yields, a stronger USD and widening spreads = risk-off.
Our new Daytrading Tool suggests an overall positive average trend after the FOMC decision, which may come as a surprise, since higher yields are not associated with “all is good…” especially in the context of US Treasury yields already being at historical highs.
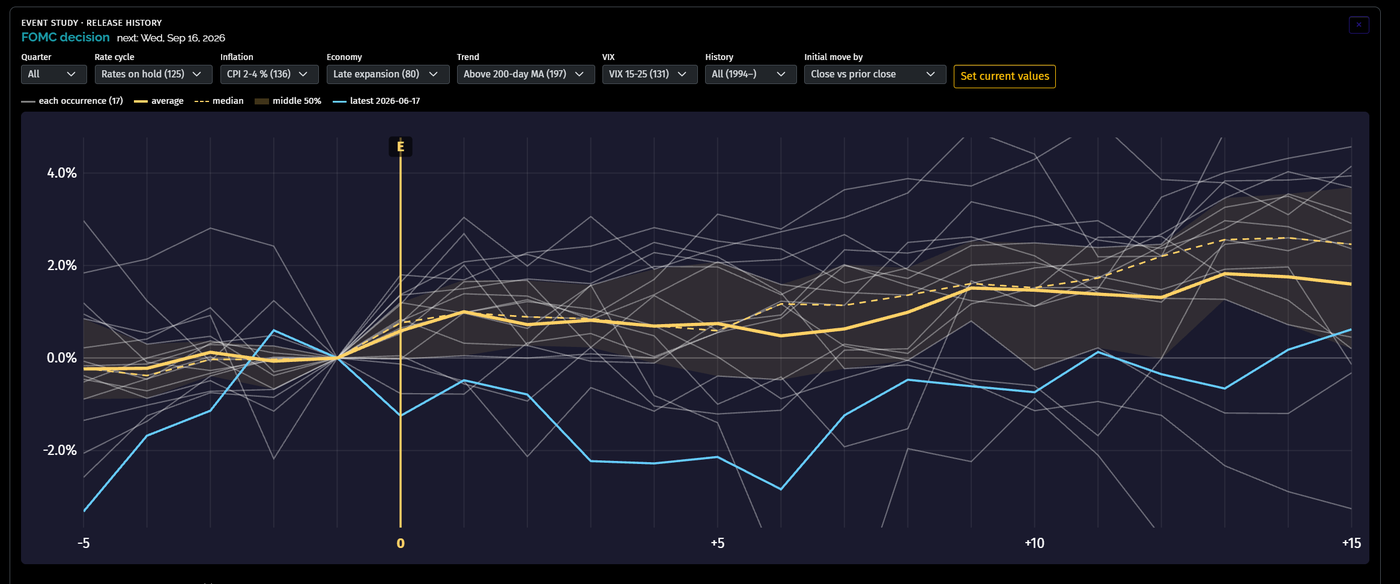
Previous FOMC meetings under similar circumstances gave on average a positive market performance in following days
The Smart Money Tracker also detected two consecutive Accumulation days, around the 760 level in the SPY, where the current Daily-50 MA acts as a support.
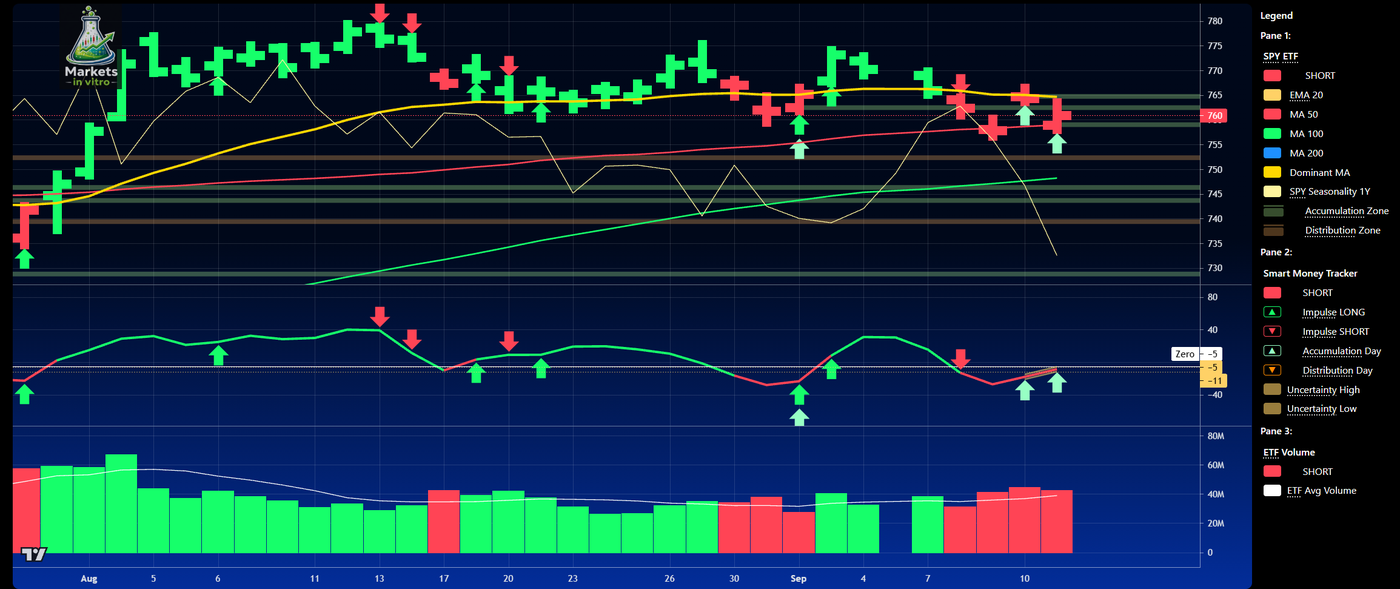 What is missing in this picture is the impulse to the bullish side, which could occur after the FED decision.
The accumulation is detected also by the Entropy Indicator, and according to the latest Commitment of Traders Report, the ES future (and all other major US Index Futures) LONG exposure is unusually low among Asset Managers, Leveraged Funds and Others.
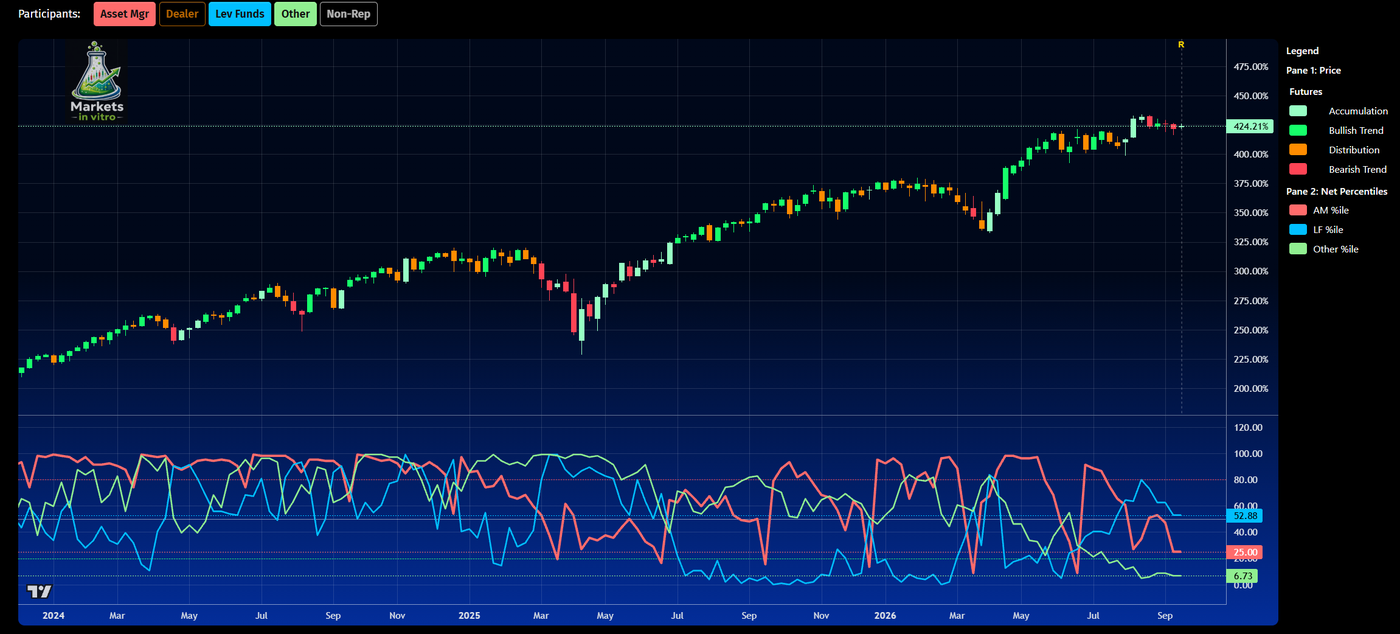 Many large institutions went short or at least risk-off. In this environment a bullish move could trigger a large short-squeeze and spark a rally, whereas a bearish move could spark a bearish breakout and initiate a new trend to the downside.
A 25 bp hike is already largely priced in, with futures implying roughly a 90% probability and 85% of economists in the latest Reuters poll expecting a hike. This means the hike itself would not be a major hawkish surprise. Reuters: Fed rate hike now likely
At the same time, much of the recent inflation pressure comes from the energy shock, with Brent above $100 amid Middle East supply disruptions. Higher policy rates cannot resolve an oil supply shock, giving the Fed a reason to hike as an inflation-insurance measure without committing to an aggressive tightening cycle. Reuters: Oil shock and Fed expectations
Financial conditions have also tightened substantially already. The 10Y Treasury yield has reached 5%, raising mortgage, corporate and consumer borrowing costs even without additional Fed action. Reuters: U.S. 10Y reaches 5%
Most importantly, markets are now pricing up to four hikes, while economists are considerably less aggressive. That creates room for a dovish surprise even if the Fed hikes: Warsh could deliver +25 bp while emphasizing that future decisions remain data-dependent rather than signaling a new hiking cycle. Reuters: Markets price further tightening
Scenario B therefore represents a potentially bullish “less hawkish than priced” outcome: the Fed hikes, but expectations for subsequent hikes fall → Treasury yields ↓, USD ↓, equities ↑, gold ↑, crypto ↑ and credit spreads tighten. Reuters specifically notes that a signal from Warsh that the hike is a one-off rather than the start of a hiking cycle could provide an upside surprise for risk assets. Reuters: Fed policy and Bitcoin/risk assets
**Wallstreet’s Playbook: ** 1. Price in the wors 2. Scare weak money out and accumulate 3. Rally on bad news for no fundamental reason and blame everybody
Stay cautois out there and take informed trading dcisions With Markets in Vitro