Market Analysis
!!! We developed a workaround to temporarily neglect missing data !!!
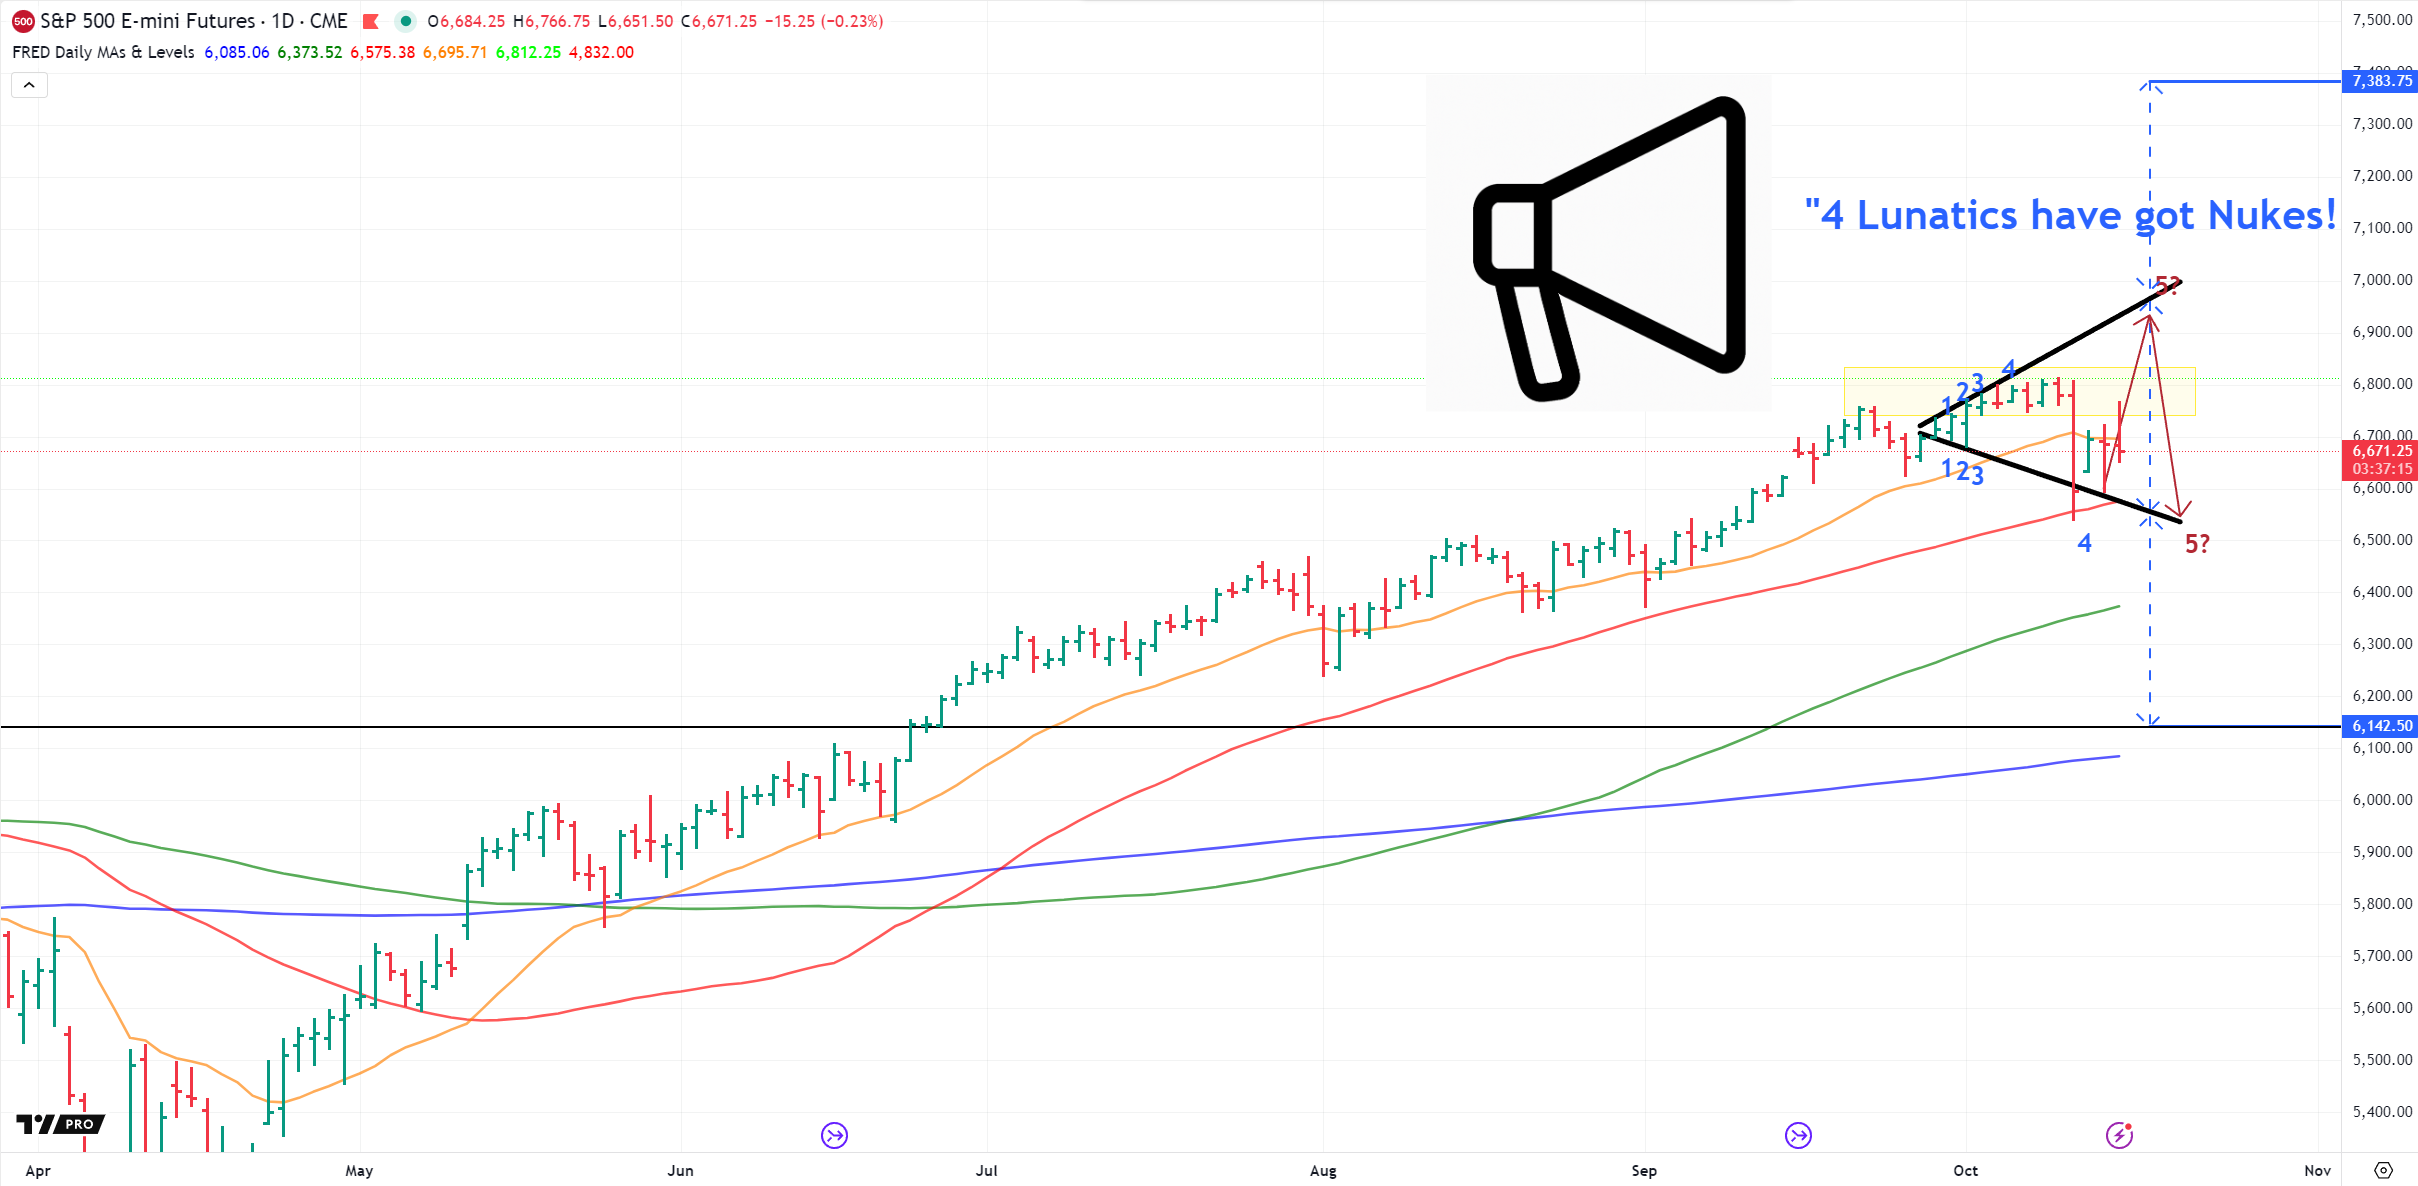
Despite strong moves up and down, volatility has come to stay.
With the SP500 Indicator deep in the red zone, we expect powerful bear-market rallies that could reverse suddenly.
Don’t get fooled by extreme upside spikes — they are the hallmark of early-stage bear markets.
“Informed money” (not the so-called “smart money”) continues to rotate out of Big Tech, a trade that started earlier this year. October could therefore bring further rounds of selling pressure.
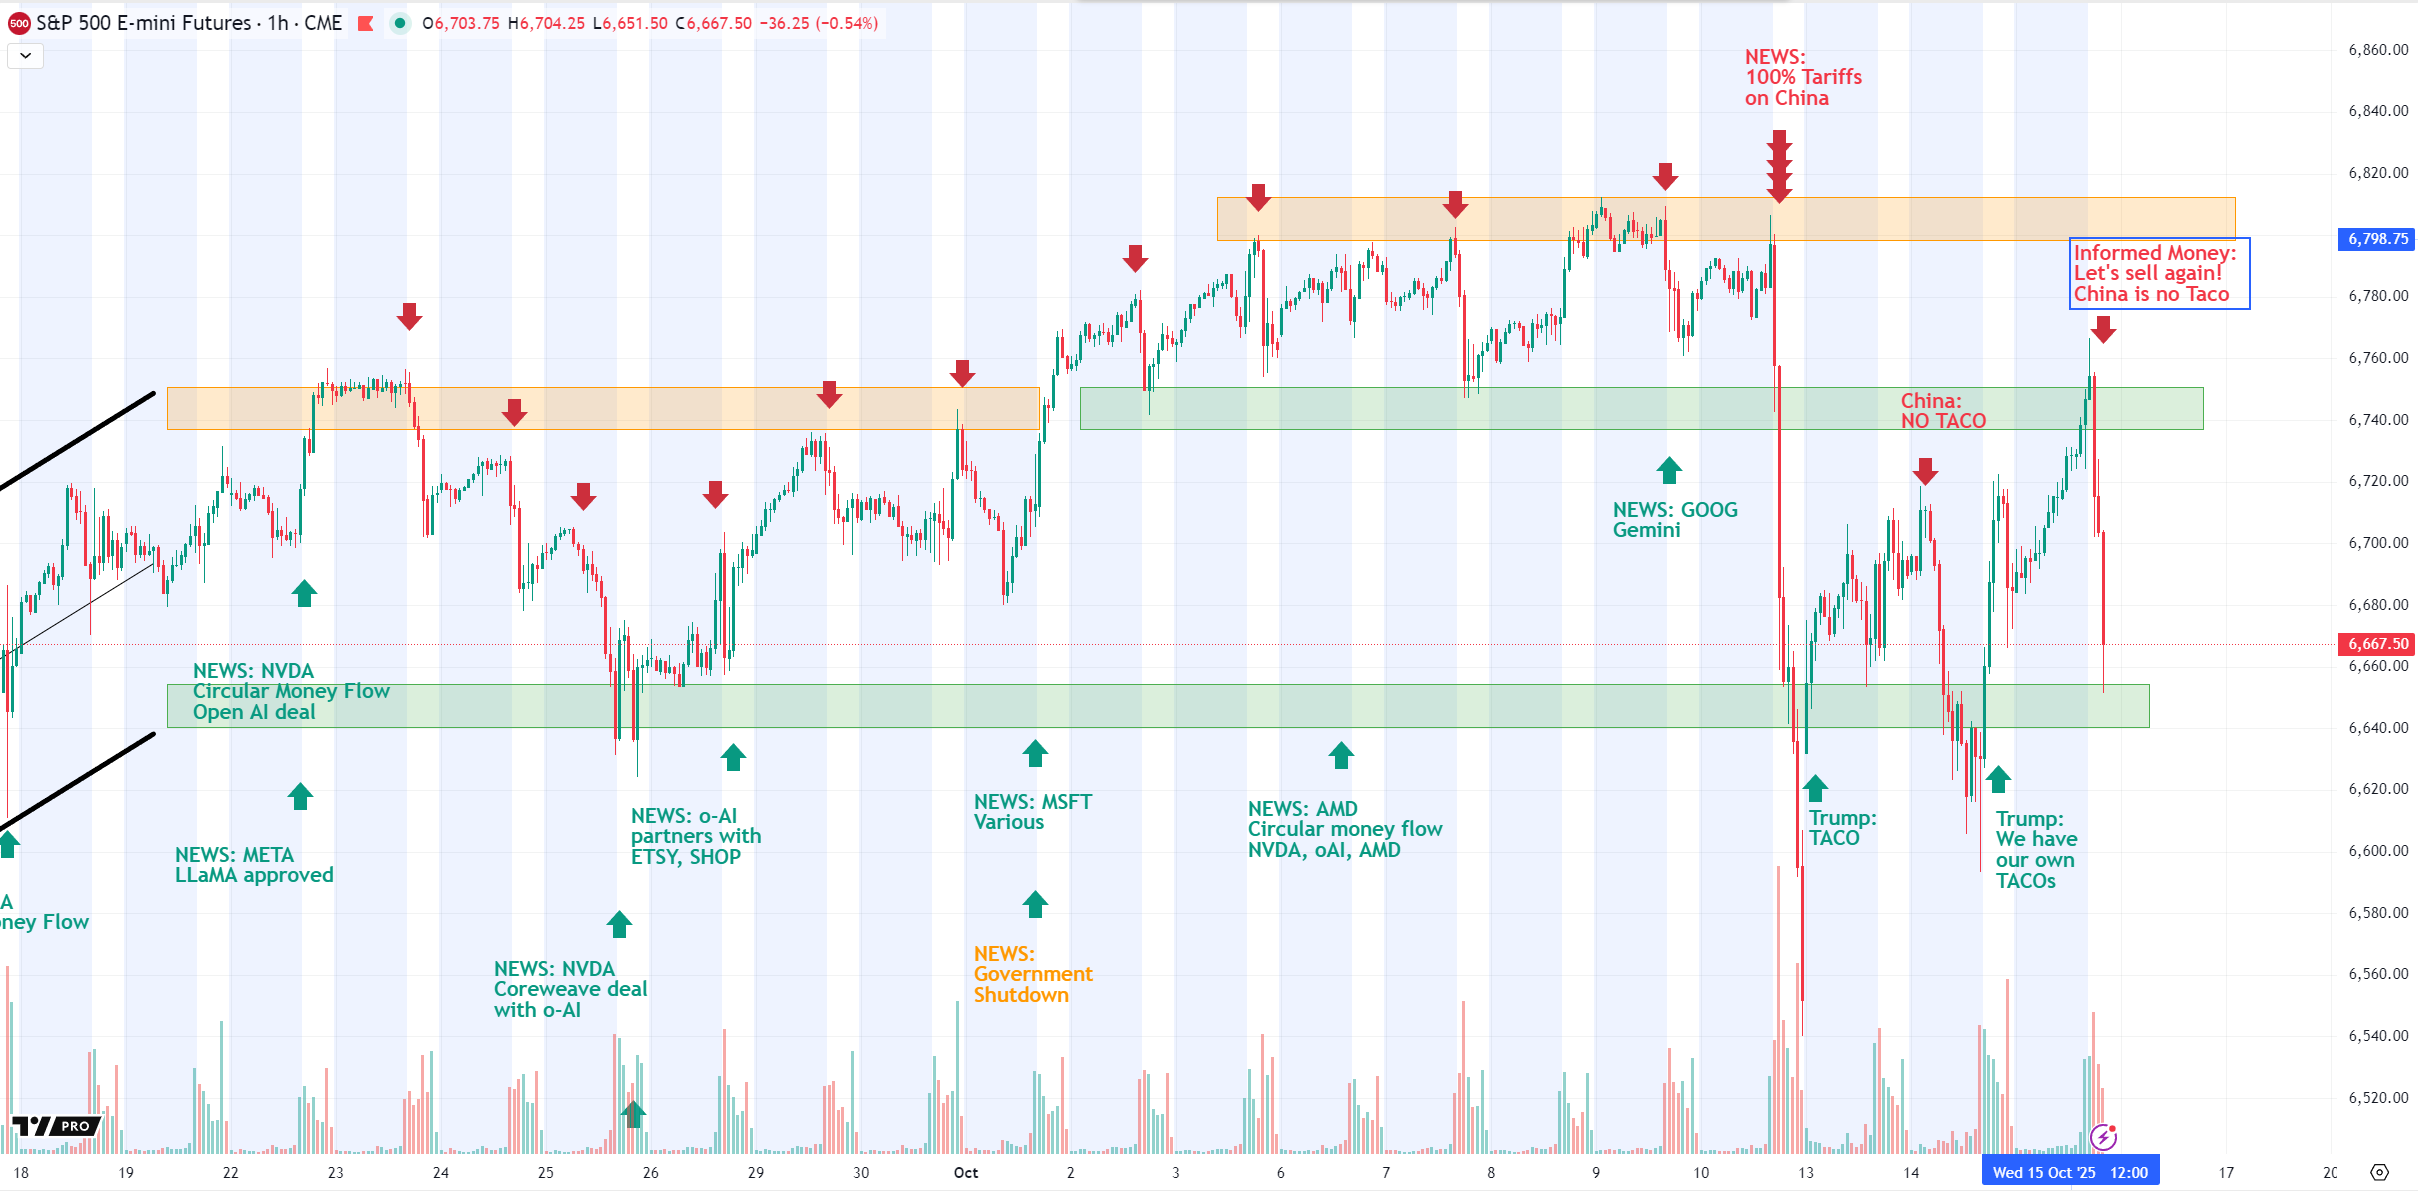
The overall structure has all the characteristics of a bear market just unfolding.
Yes, new ATHs are still possible — but systemic weakness is becoming more evident, and the economic and political missteps of 2025 will eventually have to be paid for.
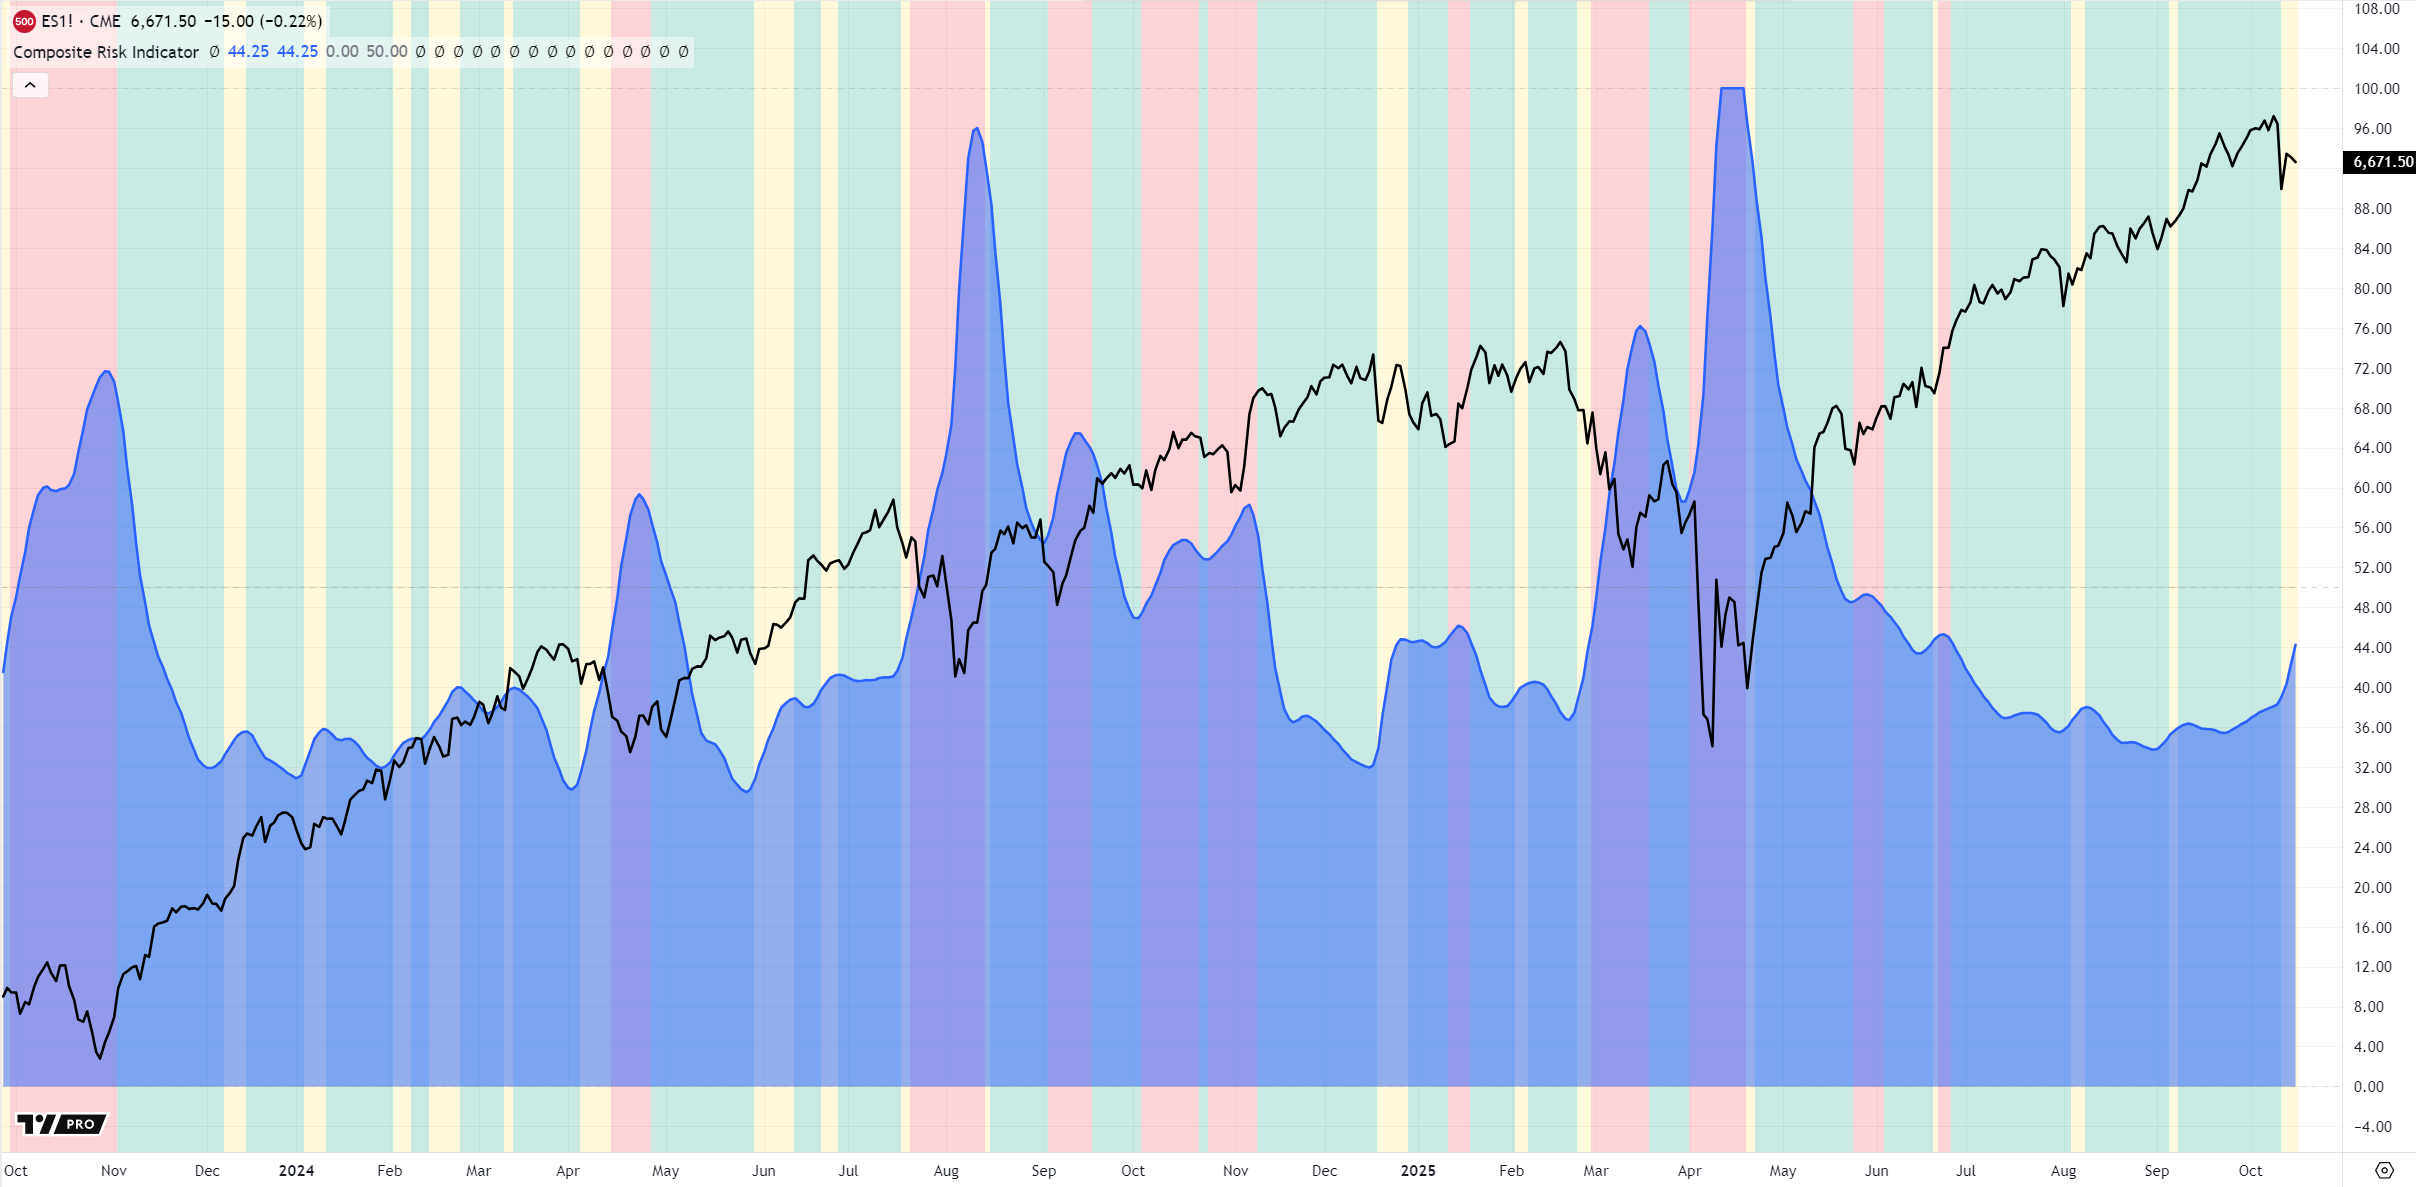
As an additional warning signal, the Composite Risk Indicator is now skyrocketing — and that’s never good news for equity markets.
Stay cautious in these fast-moving, news-driven markets.
Only disciplined, risk-managed trading can navigate such environments successfully.
The US-China Trade Conflict
Global growth remains fragile.
Although the IMF slightly revised its forecasts upward this week, it warned that renewed trade conflicts could knock up to 1.2 percentage points off global GDP growth (Reuters).
China’s exports to the U.S. fell 27% year-over-year in September, underscoring the depth of the slowdown (AP News).
Meanwhile, the trade conflict is escalating sharply.
Washington is preparing 100% tariffs in retaliation for Beijing’s export controls on rare earths (The Guardian).
Analysts at Oxford Economics warn that a full-scale decoupling from China’s supply chains — without viable alternatives — could trigger a shock to the U.S. economy on par with COVID (Investopedia).
This geopolitical overhang adds another layer of risk to already nervous markets.
Investors should not underestimate the feedback loop between policy uncertainty, currency weakness, and capital outflows — a mix that often precedes the next leg down in equities.
Outlook
This is not an environment for a healthy bull market. Big money may push and pull with bursts of optimism, but reality has a way of striking back hard. Expect that exuberant rallies will continue to be tempered by structural weakness, policy risk, and sentiment shifts. Looking ahead, this week’s calendar holds a few market-relevant events to watch closely: China will release its GDP (QoQ & YoY) data on October 16, which could reignite volatility in global equities. Meanwhile in the U.S., continued fallout from the federal government shutdown and delayed economic data releases may amplify uncertainty. Keep an eye on any surprise commentary from central banks or trade officials — they may once again move markets in a flash.