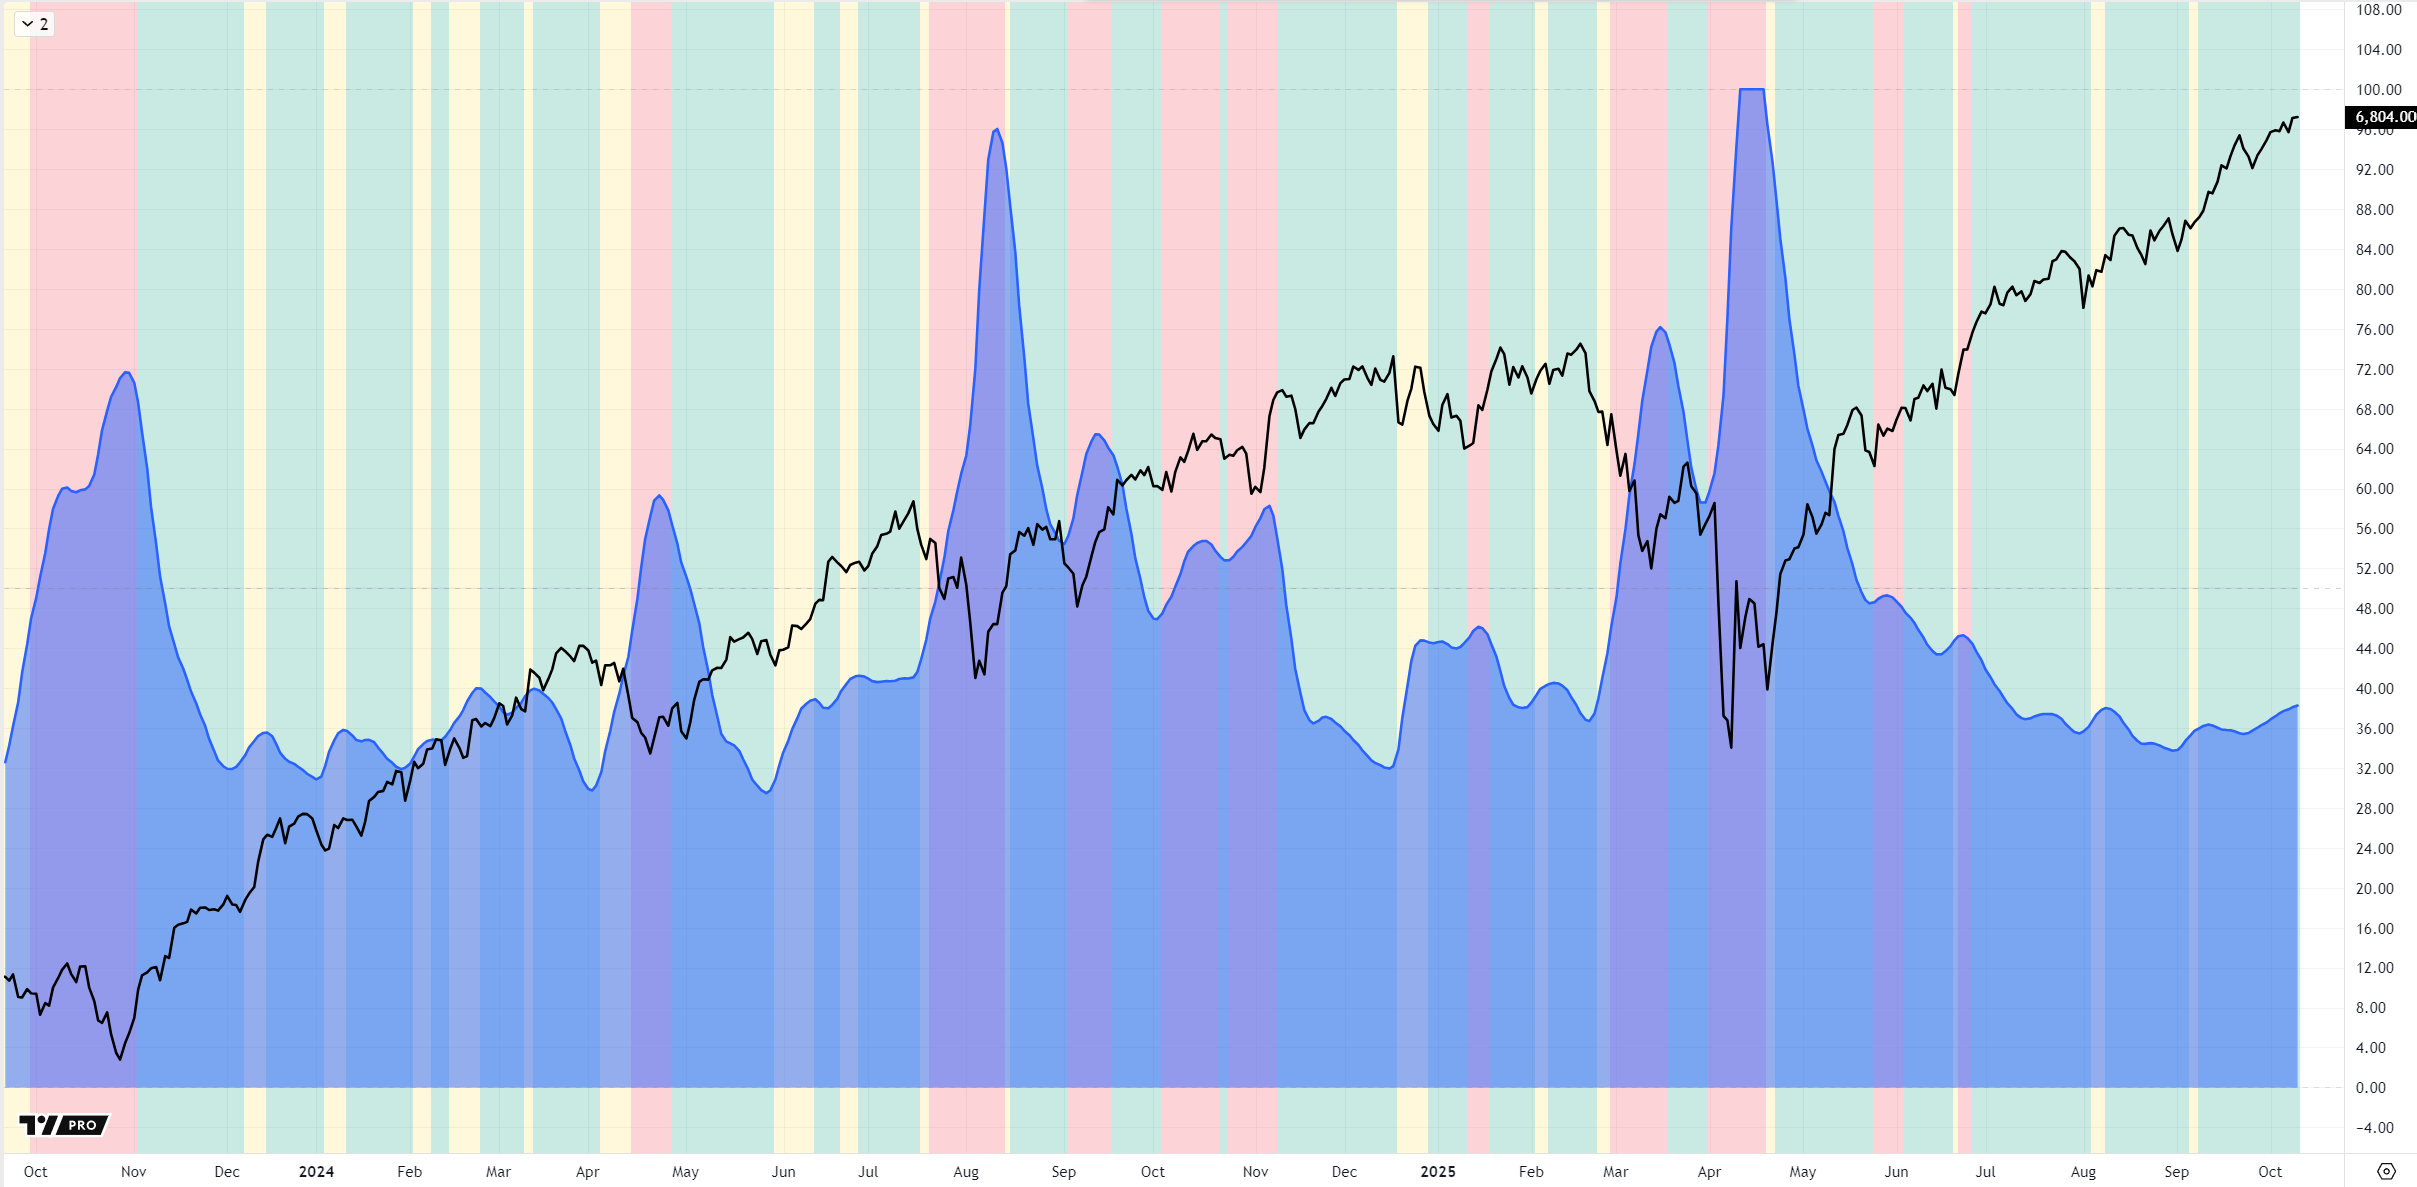
+++ DUE TO THE GOVERNMENT SHUTDOWN, THE SP500 INDICATOR CANNOT BE CALCULATED +++
With uncertainty elevated and key data missing, the SP500 Indicator cannot provide its usual level of reliability and is therefore temporarily suspended.
🕒 U.S. Data Releases Delayed Due to the Government Shutdown
Status as of October 9, 2025
The ongoing federal government shutdown has disrupted a wide range of economic reporting.
Many crucial datasets—vital for investors, policymakers, and analysts—are temporarily unavailable.
This “data blackout” adds an additional layer of uncertainty to an already fragile market environment.
Most major macroeconomic data from the BLS, BEA, and Census Bureau are paused until Congress restores funding.
Market transparency has also suffered—the CFTC’s Commitment of Traders (COT) Report, a key measure of speculative and institutional positioning, has been suspended.
Without these indicators, volatility models, inflation forecasts, and macro trading signals are effectively running blind.
Only the Federal Reserve and EIA remain operational, maintaining limited visibility into financial and energy markets.
| Agency / Source | Data Release | Original Schedule | Status / Impact |
|---|---|---|---|
| Bureau of Labor Statistics (BLS) | Employment Situation Report (Nonfarm Payrolls, Unemployment Rate, Average Hourly Earnings) | October 4, 2025 | ❌ Postponed – Labor Dept. websites offline |
| Department of Labor | Weekly Initial Jobless Claims | Every Thursday | ⚠️ Suspended – relies on federal-state coordination |
| Bureau of Labor Statistics (BLS) | Consumer Price Index (CPI) / Inflation Data | October 10, 2025 | ❌ Delayed – critical for inflation expectations & COLA |
| Census Bureau (Commerce Dept.) | Retail Sales, Durable Goods Orders, Construction Spending | Mid-October 2025 | ⚠️ At risk – dependent on funding resumption |
| Bureau of Economic Analysis (BEA) | Trade Balance / International Trade Report | October 8, 2025 | ❌ Not published |
| Bureau of Economic Analysis (BEA) | GDP revisions (Q3 advance estimate preparations) | Late October 2025 | ⚠️ Work halted – may delay Q3 GDP release |
| Department of the Treasury | Federal Budget (Monthly Deficit Report) | October 11, 2025 | ❌ Delayed |
| Commodity Futures Trading Commission (CFTC) | Commitment of Traders (COT) Report | Weekly, every Friday | ❌ Suspended – CFTC halted transparency reports |
| Census Bureau | Wholesale Inventories | October 9, 2025 | ❌ Not released |
| Social Security Administration (SSA) | Cost-of-Living Adjustment (COLA) Announcement | Mid-October 2025 | ⚠️ Likely delayed – depends on CPI-W data |
| Federal Reserve Board | Financial Accounts (Z.1) & Consumer Credit | October 2025 | ✅ Still on schedule – Fed remains funded independently |
| Energy Information Administration (EIA) | Petroleum & Natural Gas Reports | Weekly | ✅ Released normally – Energy Dept. exempt from shutdown cuts |
Market Analysis
Despite slowing momentum and occasional heavy selling, the S&P 500 continues to edge higher as every dip is quickly bought.
No clear warning signals are visible in the bond or volatility markets, meaning perceived risk remains low.
As long as U.S. liquidity injection remains strong, equities should keep drifting upward while the USD gradually weakens.
The resulting inflationary impulse will likely show up only with a delay of several months.
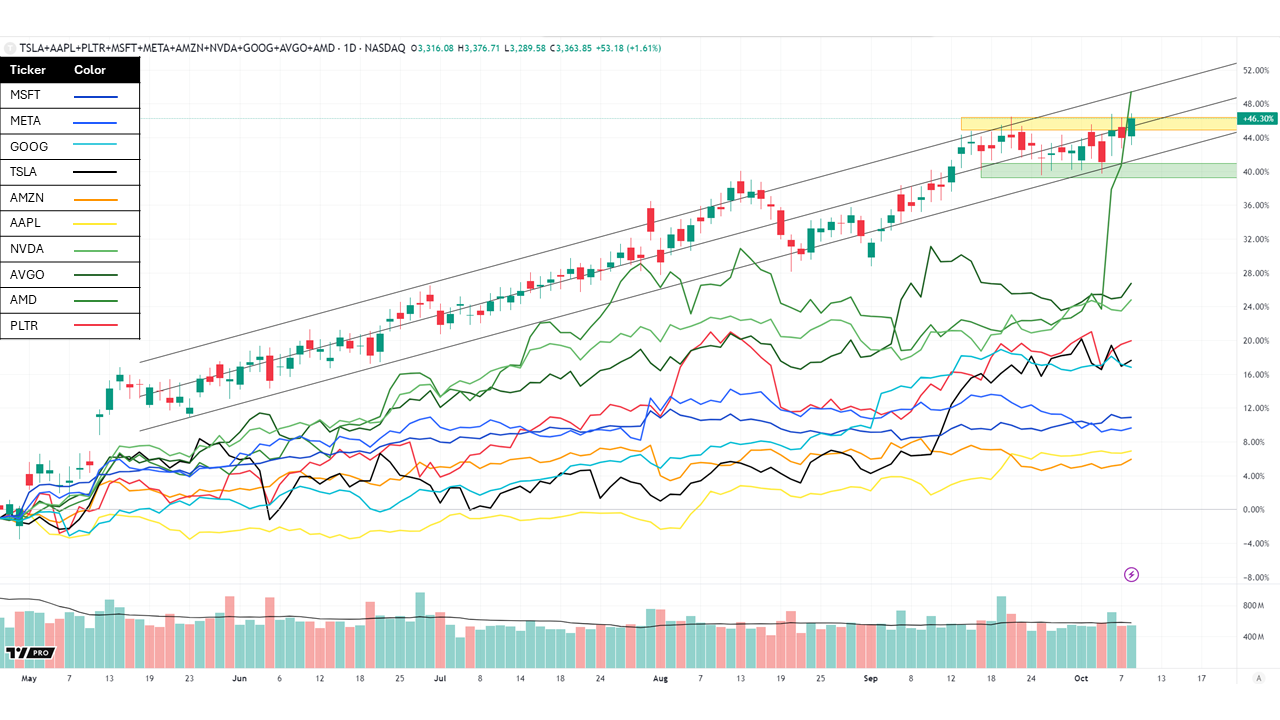
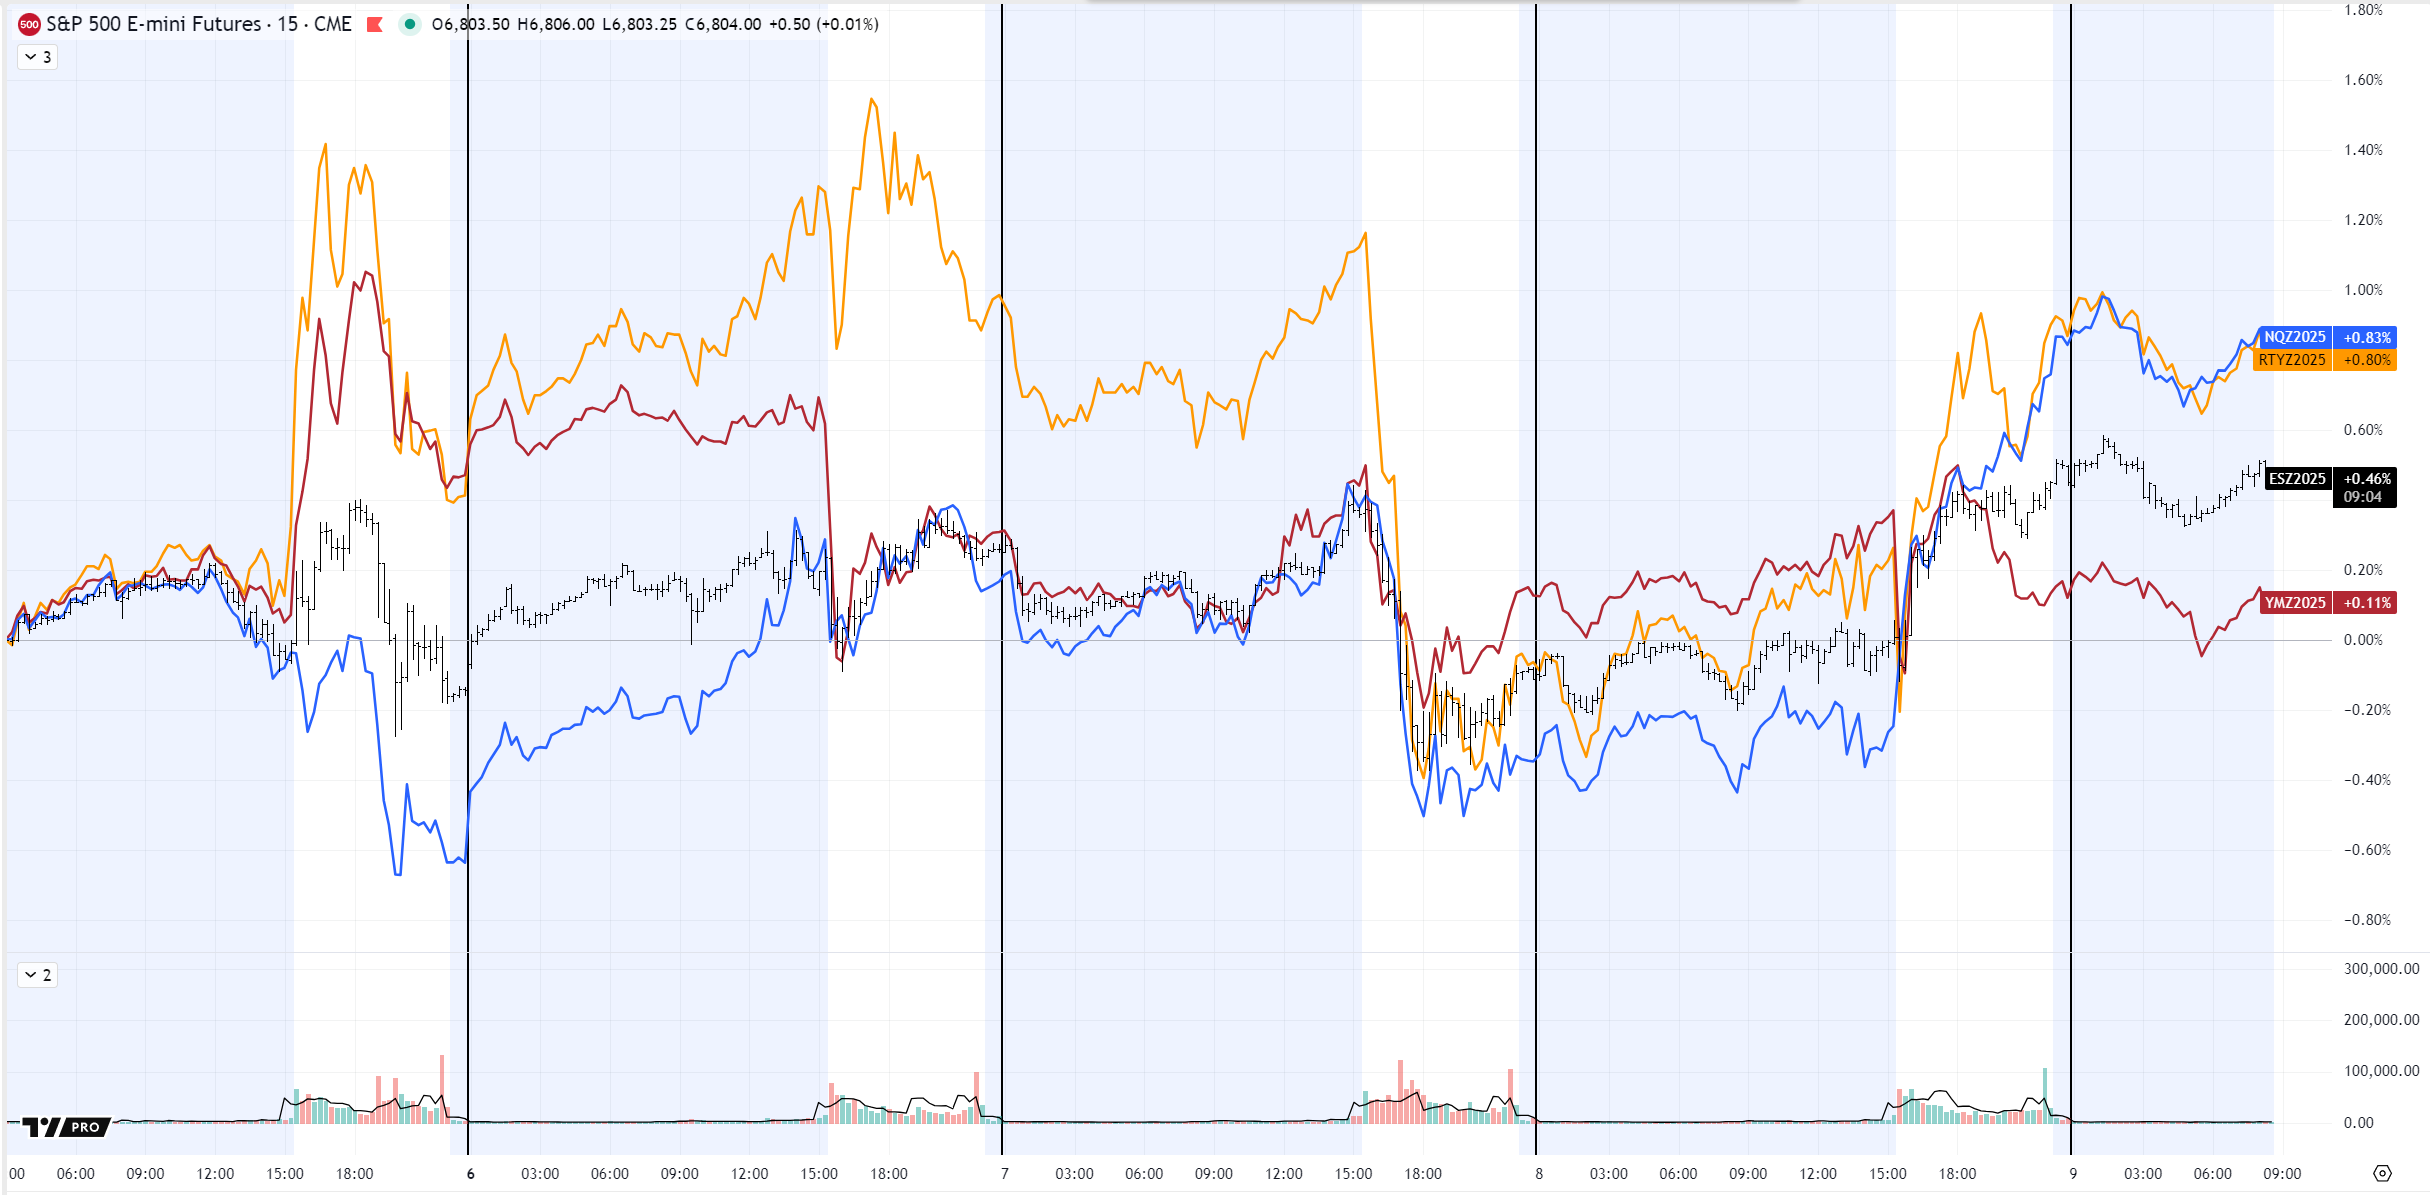
The strongest indices this week are the Nasdaq and the Russell 2000—an intriguing combination suggesting that capital continues to flow into the AI bubble, particularly AMD.
Circular money flows in, out, and around Nvidia maintain investor enthusiasm.
The “scapegoat of the week” is currently AMD, yet despite earlier signs of exhaustion, the MAG10 Composite Index remains in a stable uptrend.
The Russell continues higher in anticipation of further Fed rate cuts, which would benefit small-cap stocks the most.
Sector Rotation
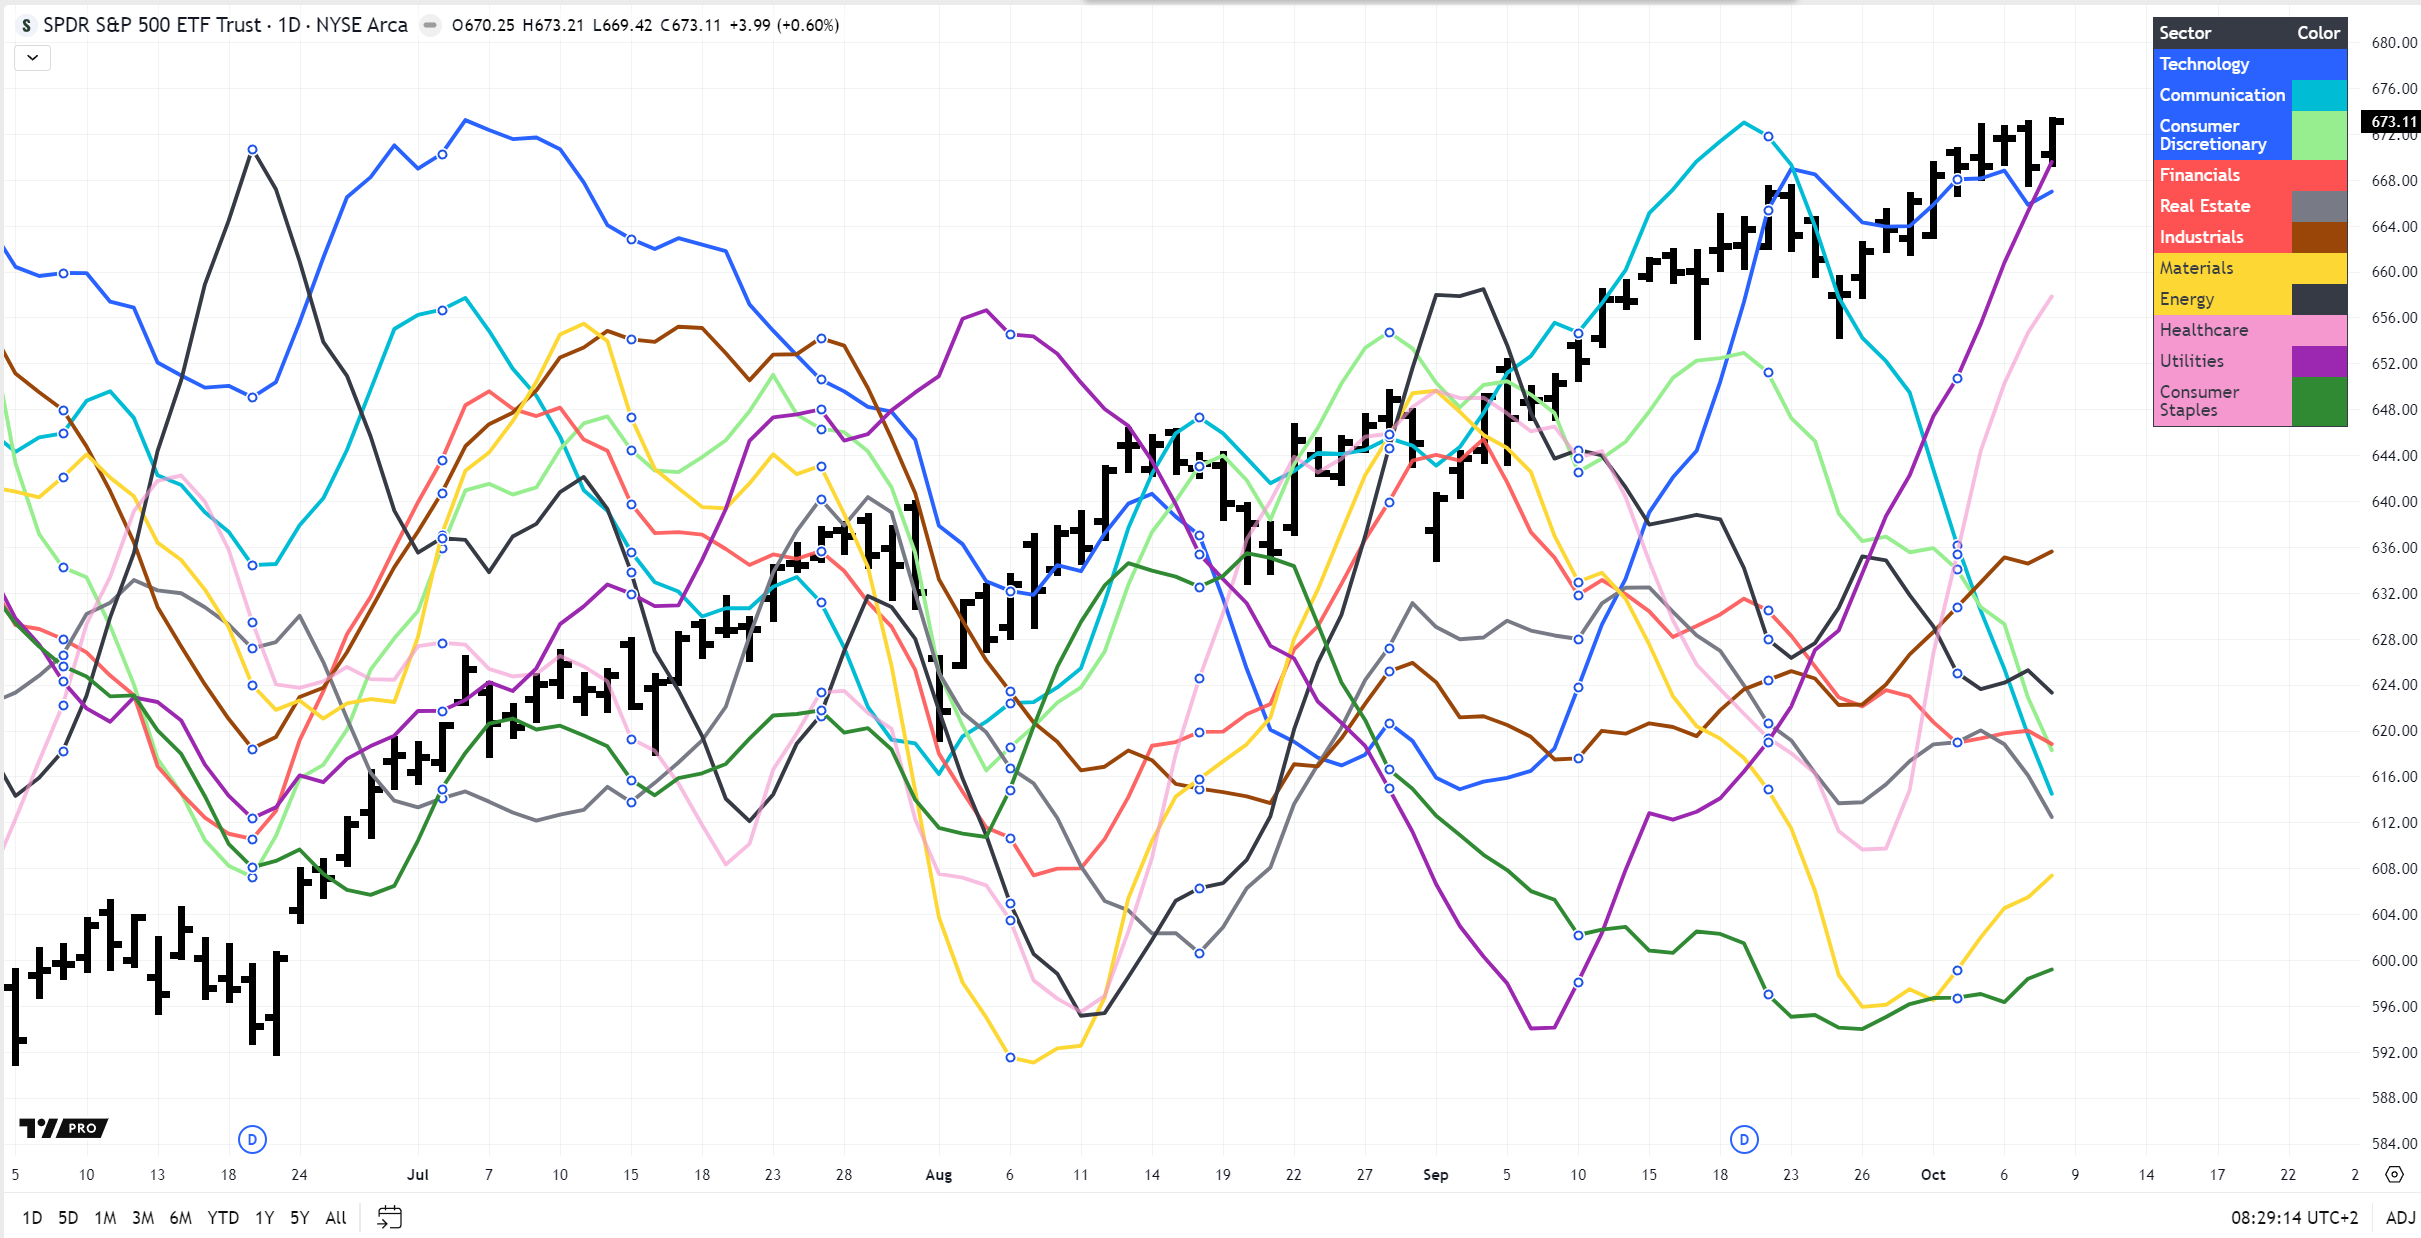
Strong: Utilities, Healthcare, Materials
Rotating In / Bottoming: Consumer Staples, Industrials
Rotating Out / Topping: Technology, Real Estate
Weak: Communication, Consumer Discretionary, Financials, Energy
Observations
Defensive sectors continue to lead — one of the few cautionary signals we currently see.
The Real Estate sector should, in theory, benefit from upcoming Fed rate cuts, yet remains extremely weak — possibly a sign of underlying stress.
With Technology showing fatigue, markets are likely in the final leg of the bull run.
This doesn’t imply an imminent sell-off, but rather a gradual shift in allocations and potential weakness in 2026.
BONUS – Sector Strengths and Stock Picking
Stock selection has become crucial in this market to outperform the S&P 500.
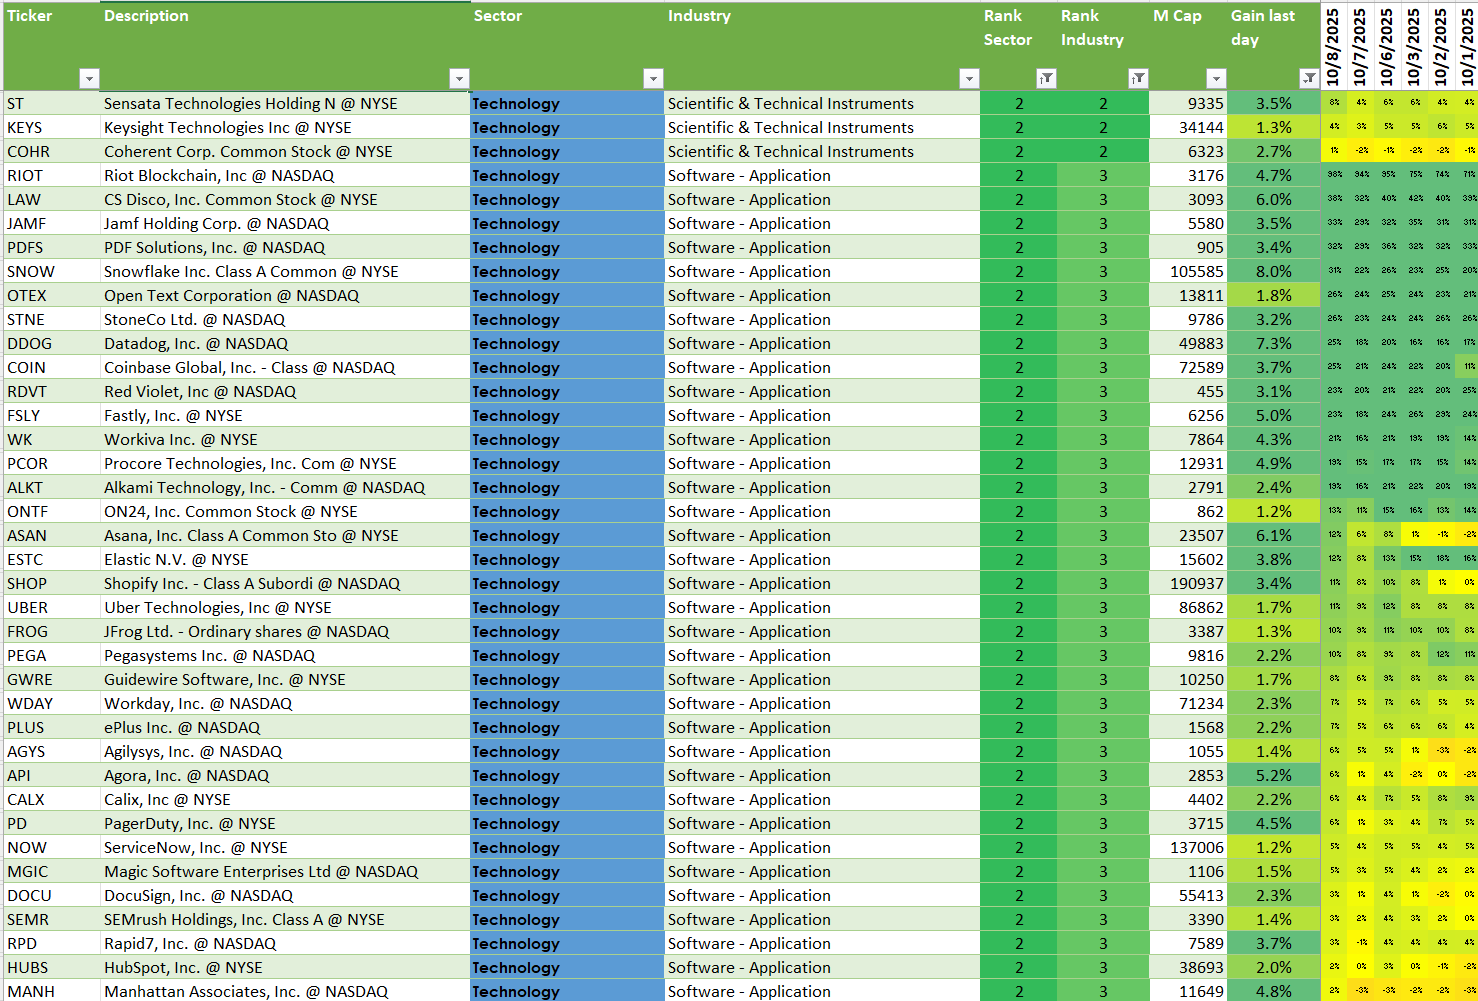
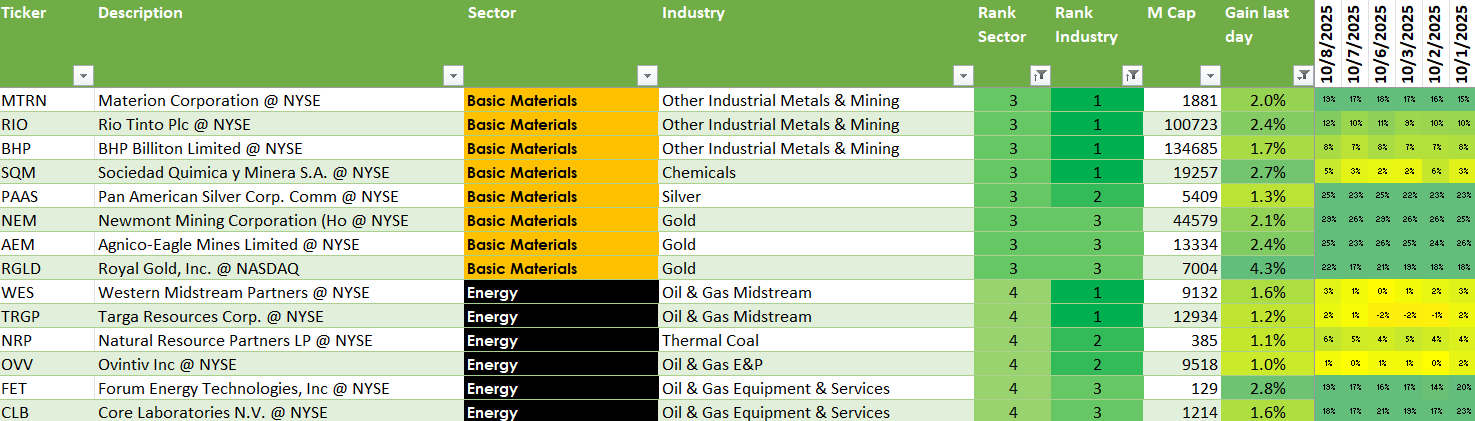
Among the strongest sectors—Utilities, Technology, Energy, and Materials—a deeper look into industries helps identify leadership rotation.
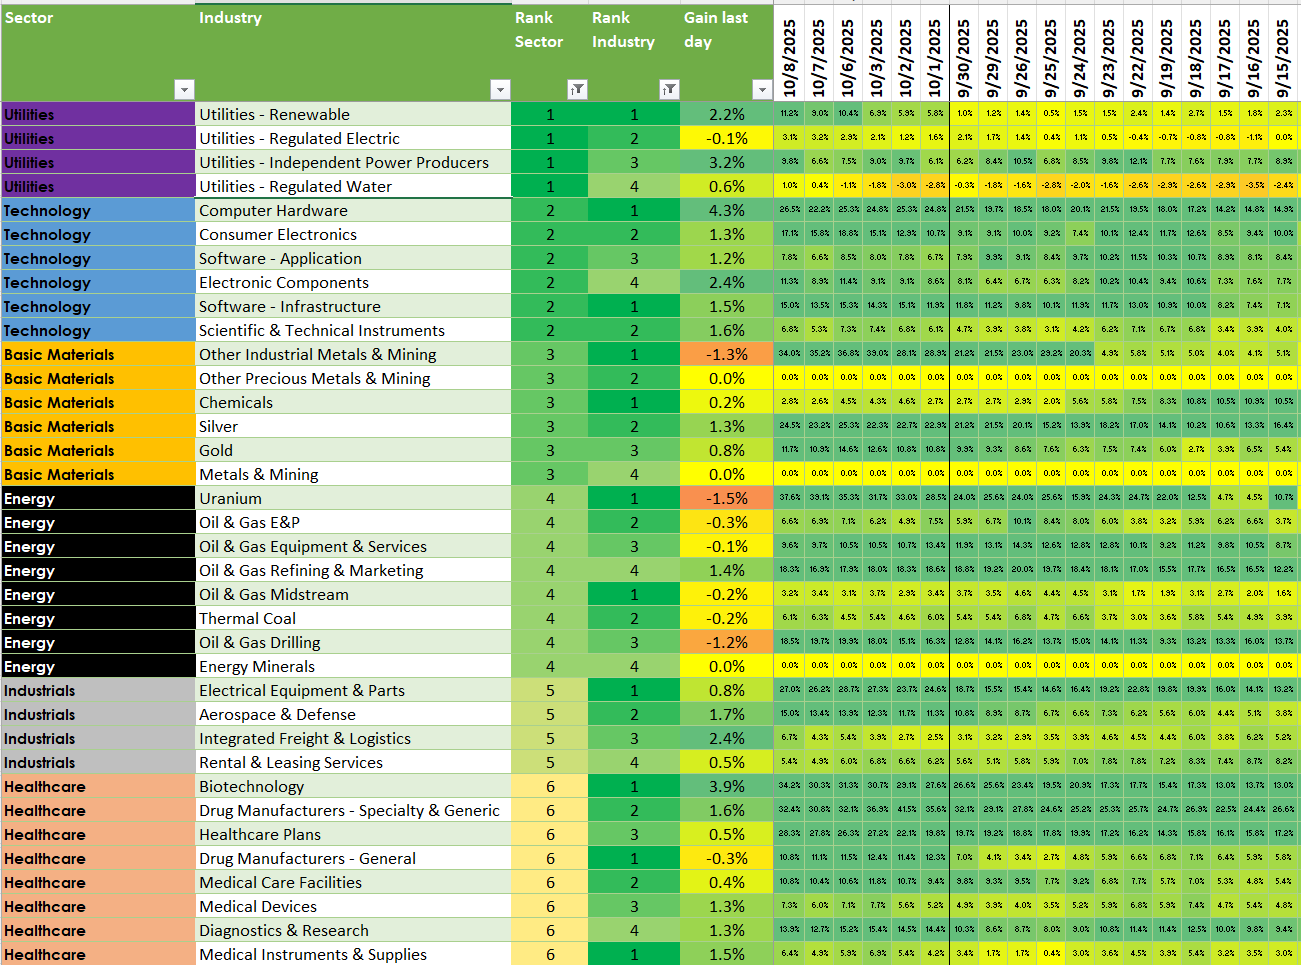
This stepwise approach highlights the strongest stocks within the strongest industries of the strongest sectors:
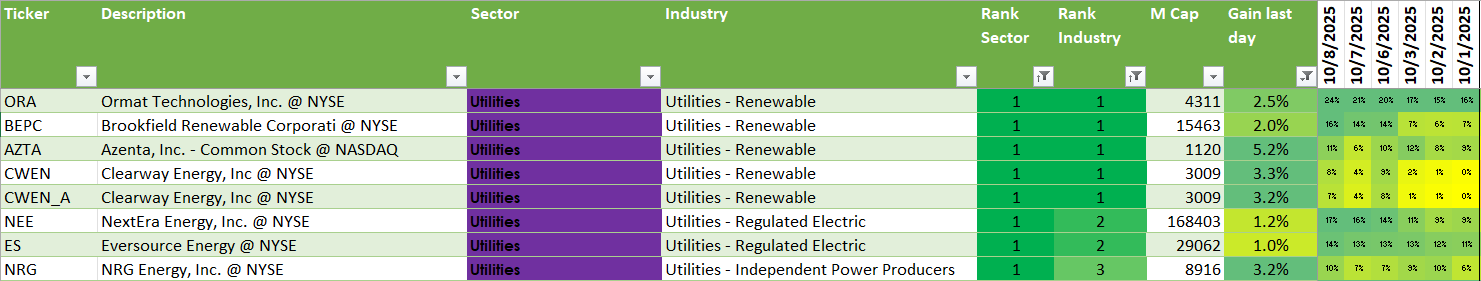
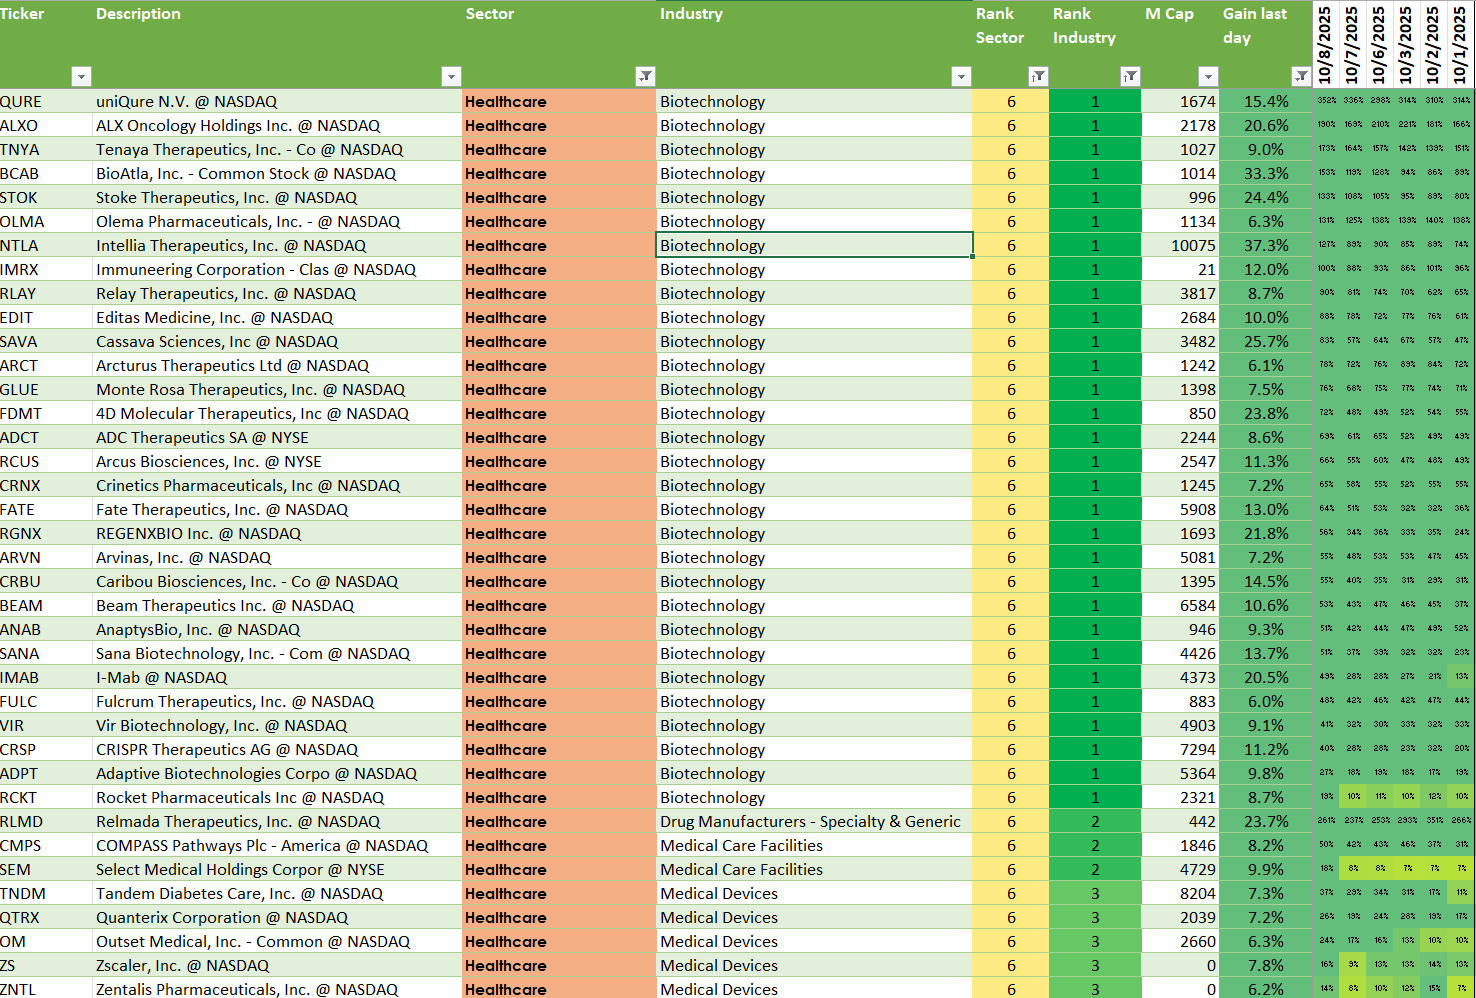
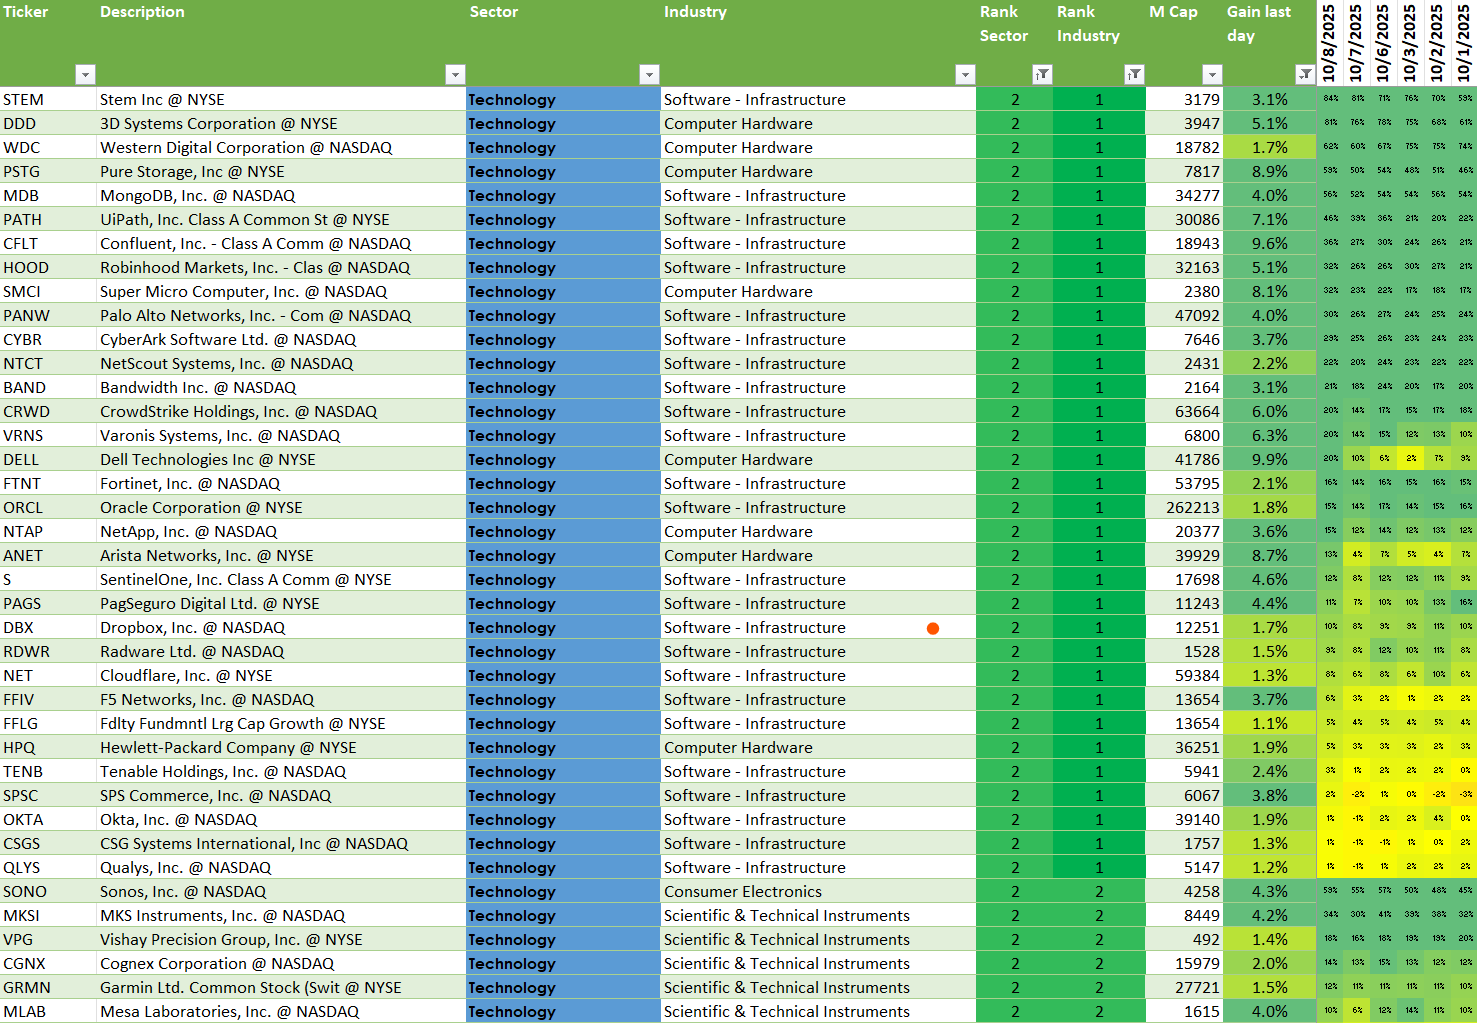
Outlook – What to Expect and Market Reactions
| Theme / Driver | Anticipated Market Reaction | Caveats / Risks |
|---|---|---|
| Fed Speeches / Messaging | 🟢 Dovish tone: equities rally, yields fall. 🔴 Hawkish tone: risk assets sell off, yields rise. |
🟡 With no CPI or jobs data, markets may overreact to wording nuances. |
| Consumer Sentiment (Univ. of Michigan, Oct Prelim) | 🟢 Strong sentiment supports cyclicals and consumer stocks. 🔴 Weak reading drives defensives, bond bids. |
🟡 Survey data are “soft”; reactions may be overstated during the data blackout. |
| Treasury Auctions / Budget Statement | 🟢 Strong demand → yields stabilize, risk appetite improves. 🔴 Weak demand → yields rise, equities pressured. |
🟡 Technical flows dominate while fundamentals stay hidden. |
| Liquidity & Volatility | 🟡 Elevated volatility likely continues — markets react to headlines, not fundamentals. | 🔴 Sudden shocks (budget, geopolitics) could trigger reversals. |
| Equity Market Tone | 🟢 Mild bullish bias if rate-cut narrative holds. 🔴 Fragile sentiment if yields spike or Fed tone hardens. |
🟡 Momentum trades prone to quick reversals; “buy-the-dip” less reliable. |
| Commodities / Precious Metals | 🟢 Gold firm above $4,000 amid uncertainty. 🟢 Energy supported by OPEC+ discipline. 🔴 Profit-taking possible if yields rise. |
🟡 Headline-driven; gold positioning crowded. |
| FX / Dollar | 🟢 Risk-on → weaker USD. 🔴 Risk-off → safe-haven USD rally. |
🟡 Shutdown politics and rate gaps add two-way volatility. |