Market Analysis
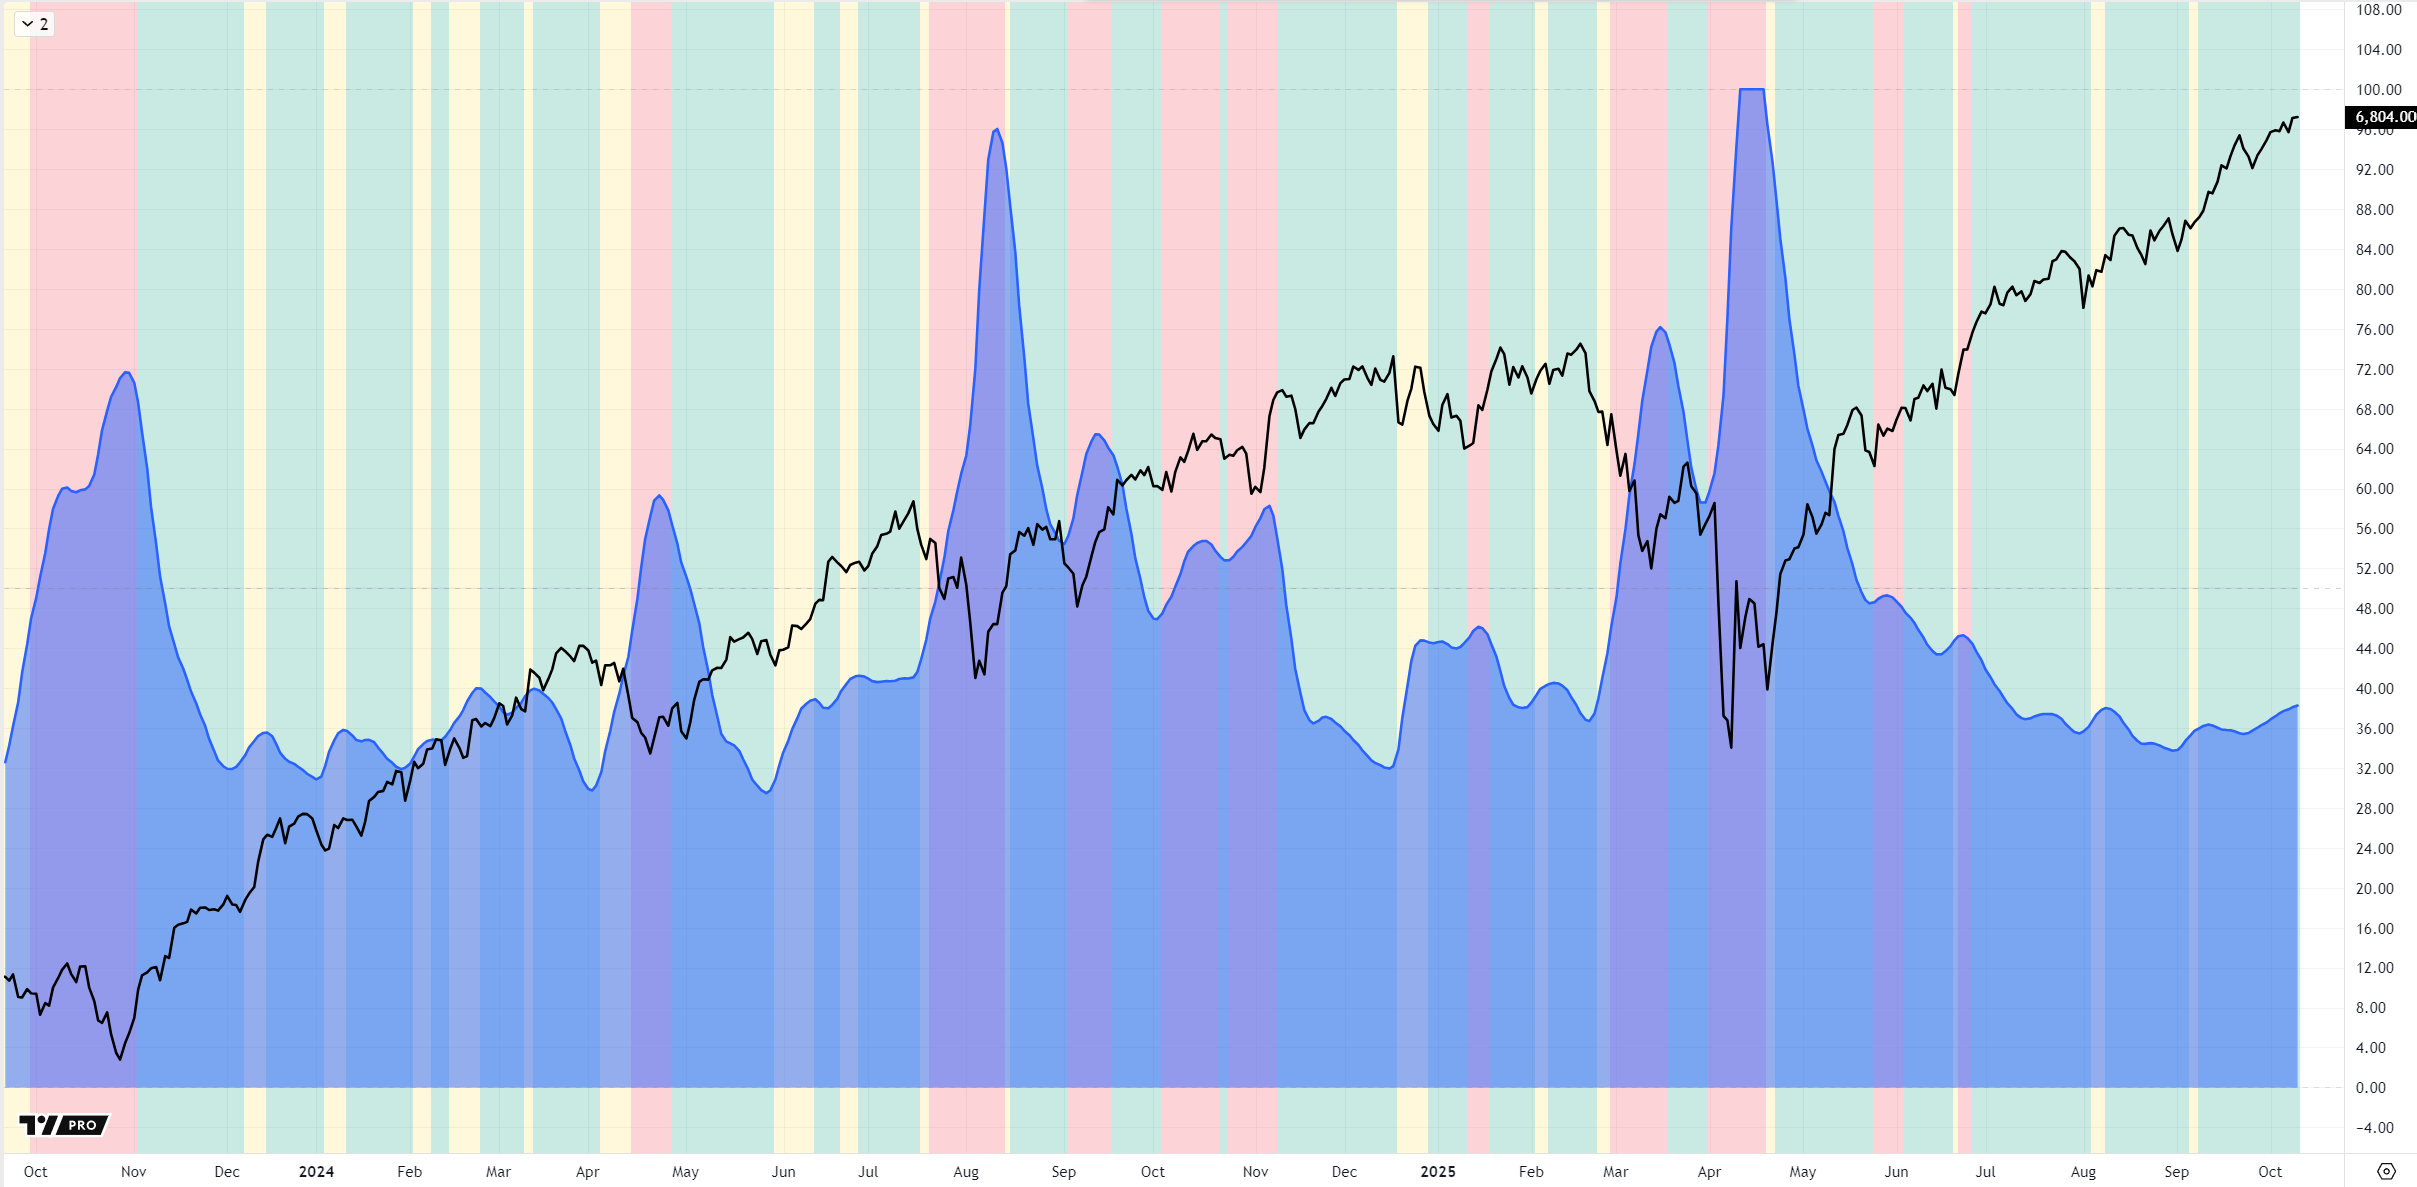
Despite a slowing momentum and big Volume sells occuring the one or the other day, the S&P is moving higher, as pullbacks are purchased. There are no cautionary signs in the Bonds market, nor in the volatility indicators, thus, the percieved market risk remains low. As long as the heavy liquidity generation by the US administration continues, the markets should move up and the USD down. The resulting inflation will only hit with a time delay of several months.
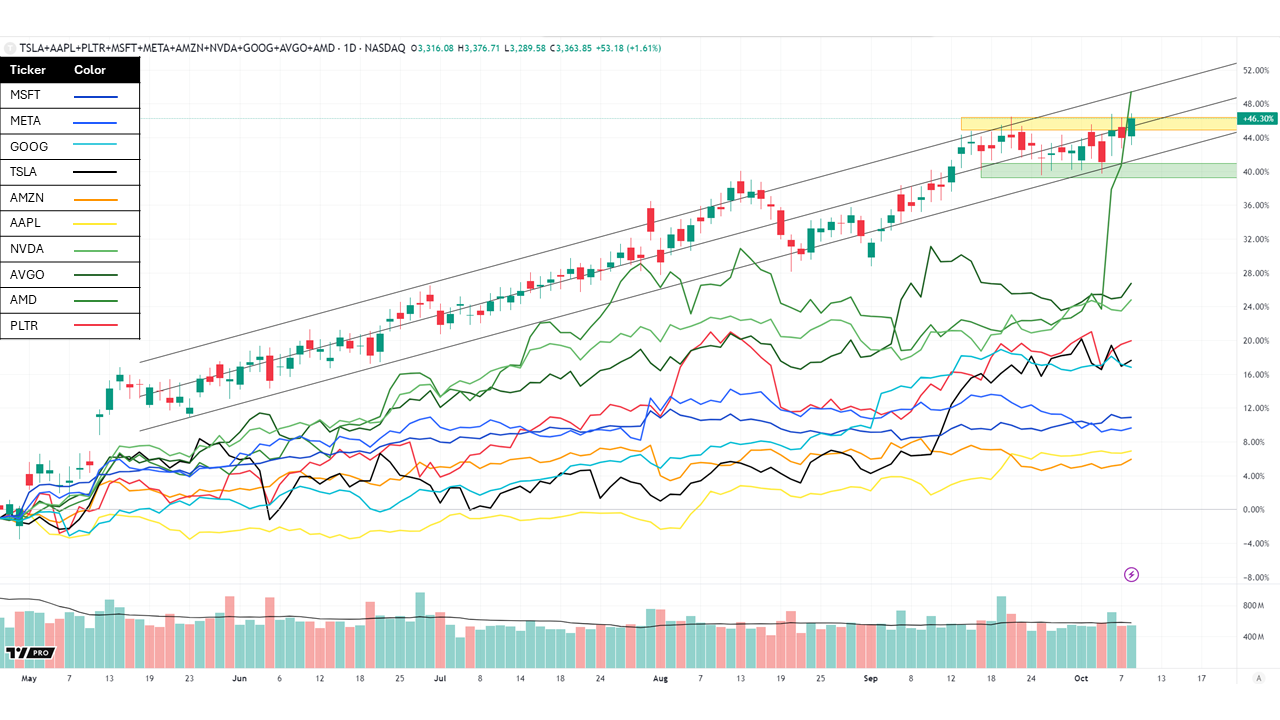
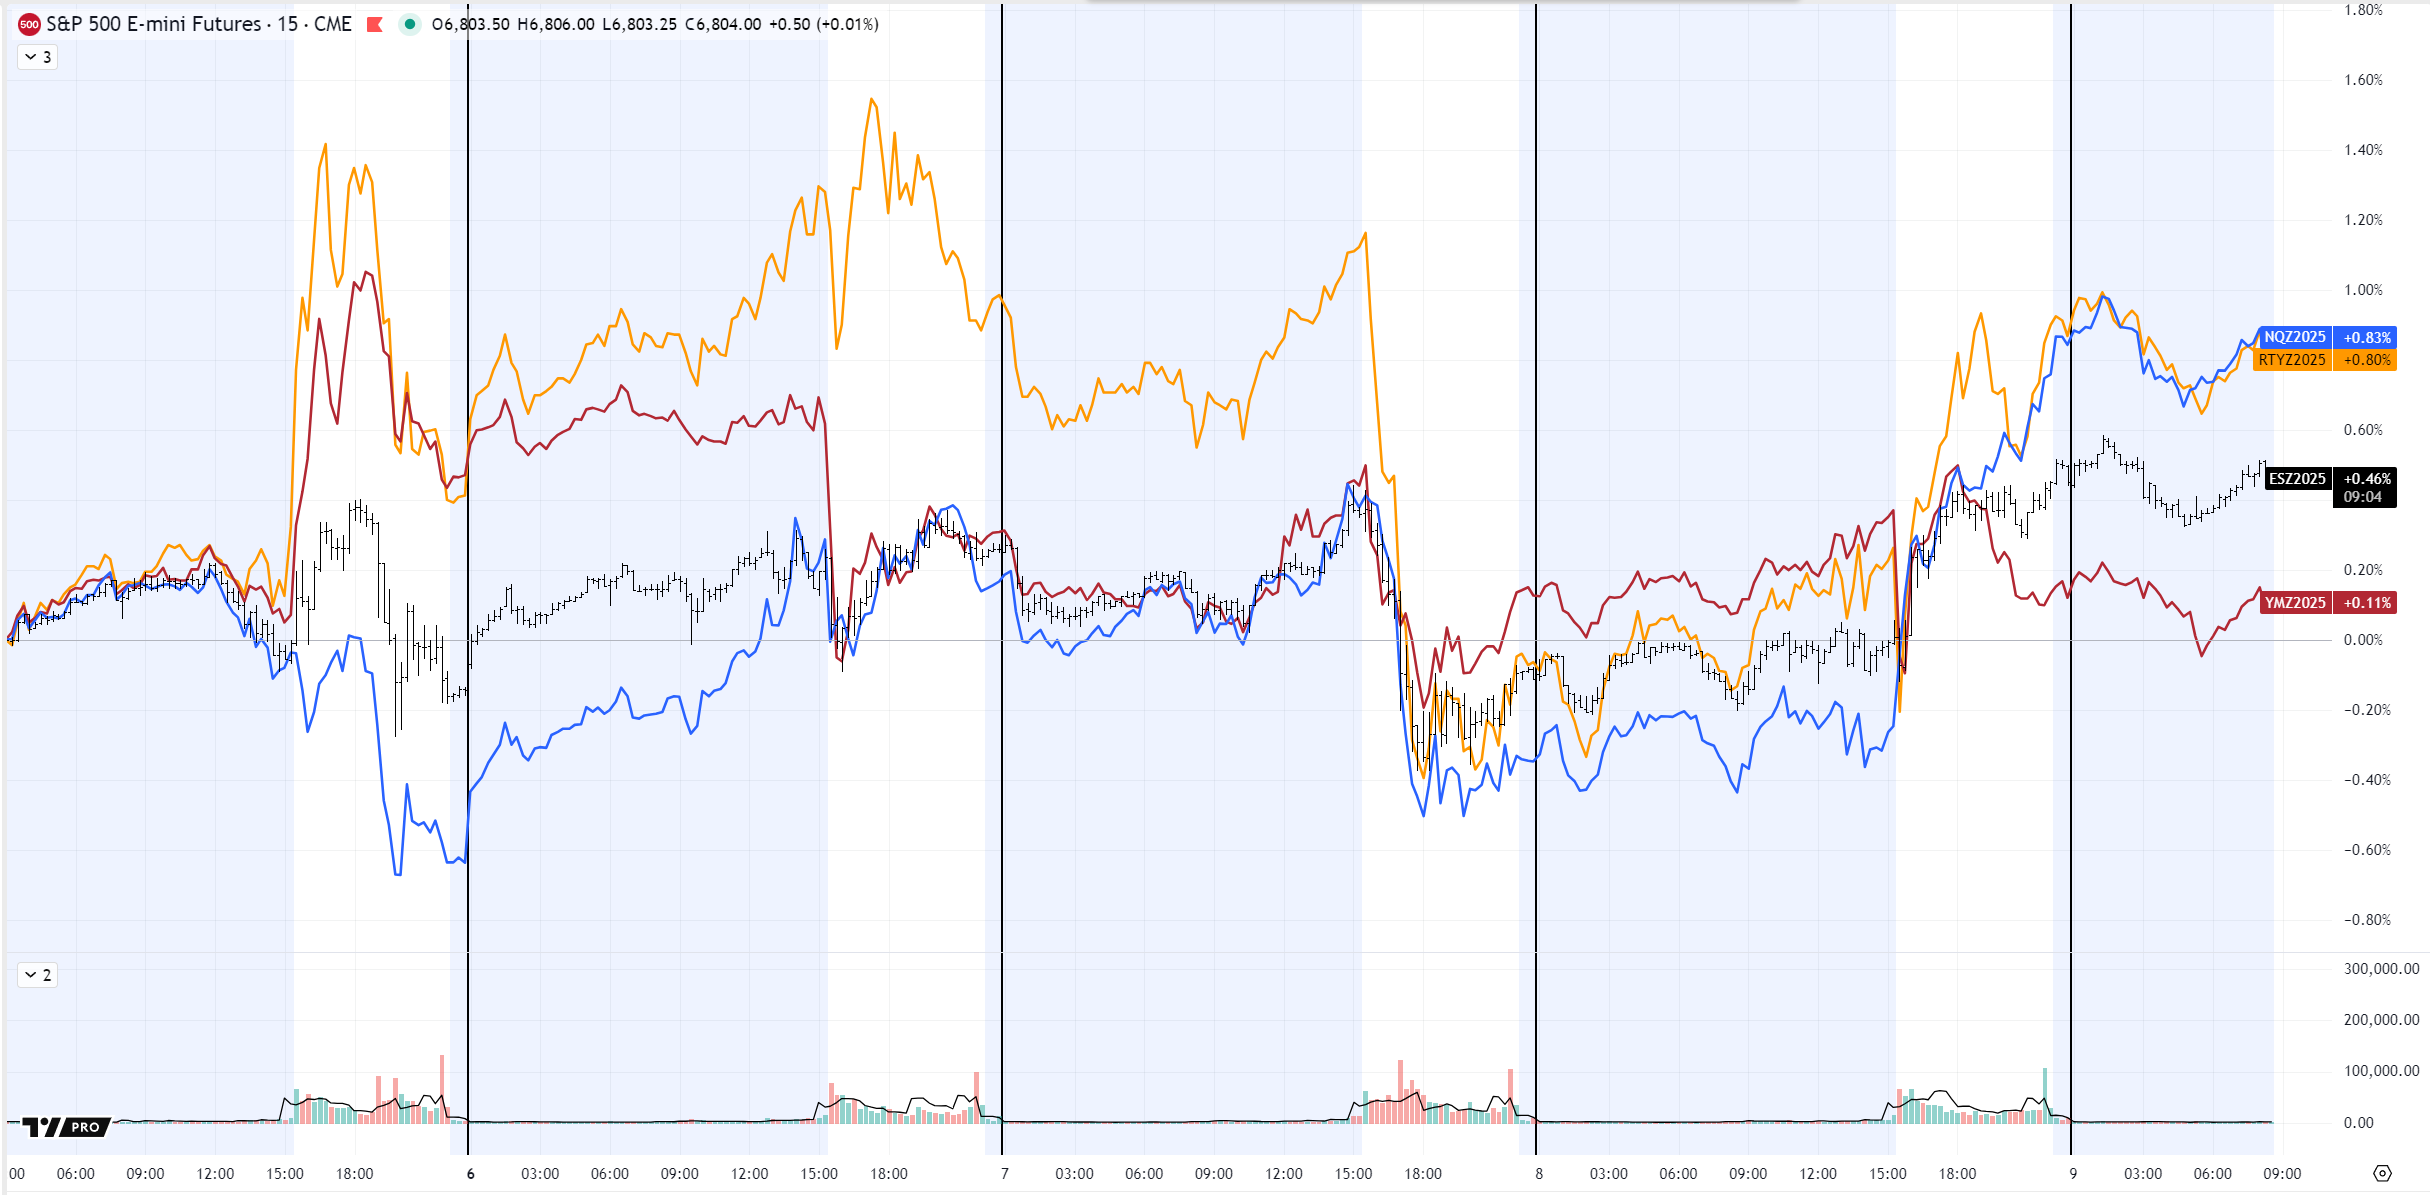
This week’s strongest indices are the Nasdaq and the Russell2000. This, being an interresting combination, suggests that money is still rotating into the AI bubble, especially AMD at the moment. Circular money flows in, out and around Nvidia continue, keeping investors enthusiasm high. The scapegoat of the week is currently AMD. Despite earilier signs of exhaustion, the composite MAG10 Index is in a stable uptrend.
 The Russel is pushing higher in anticipation of further rate cuts by the FED, which should benbefit Small-Caps the most.
Sector Rotation
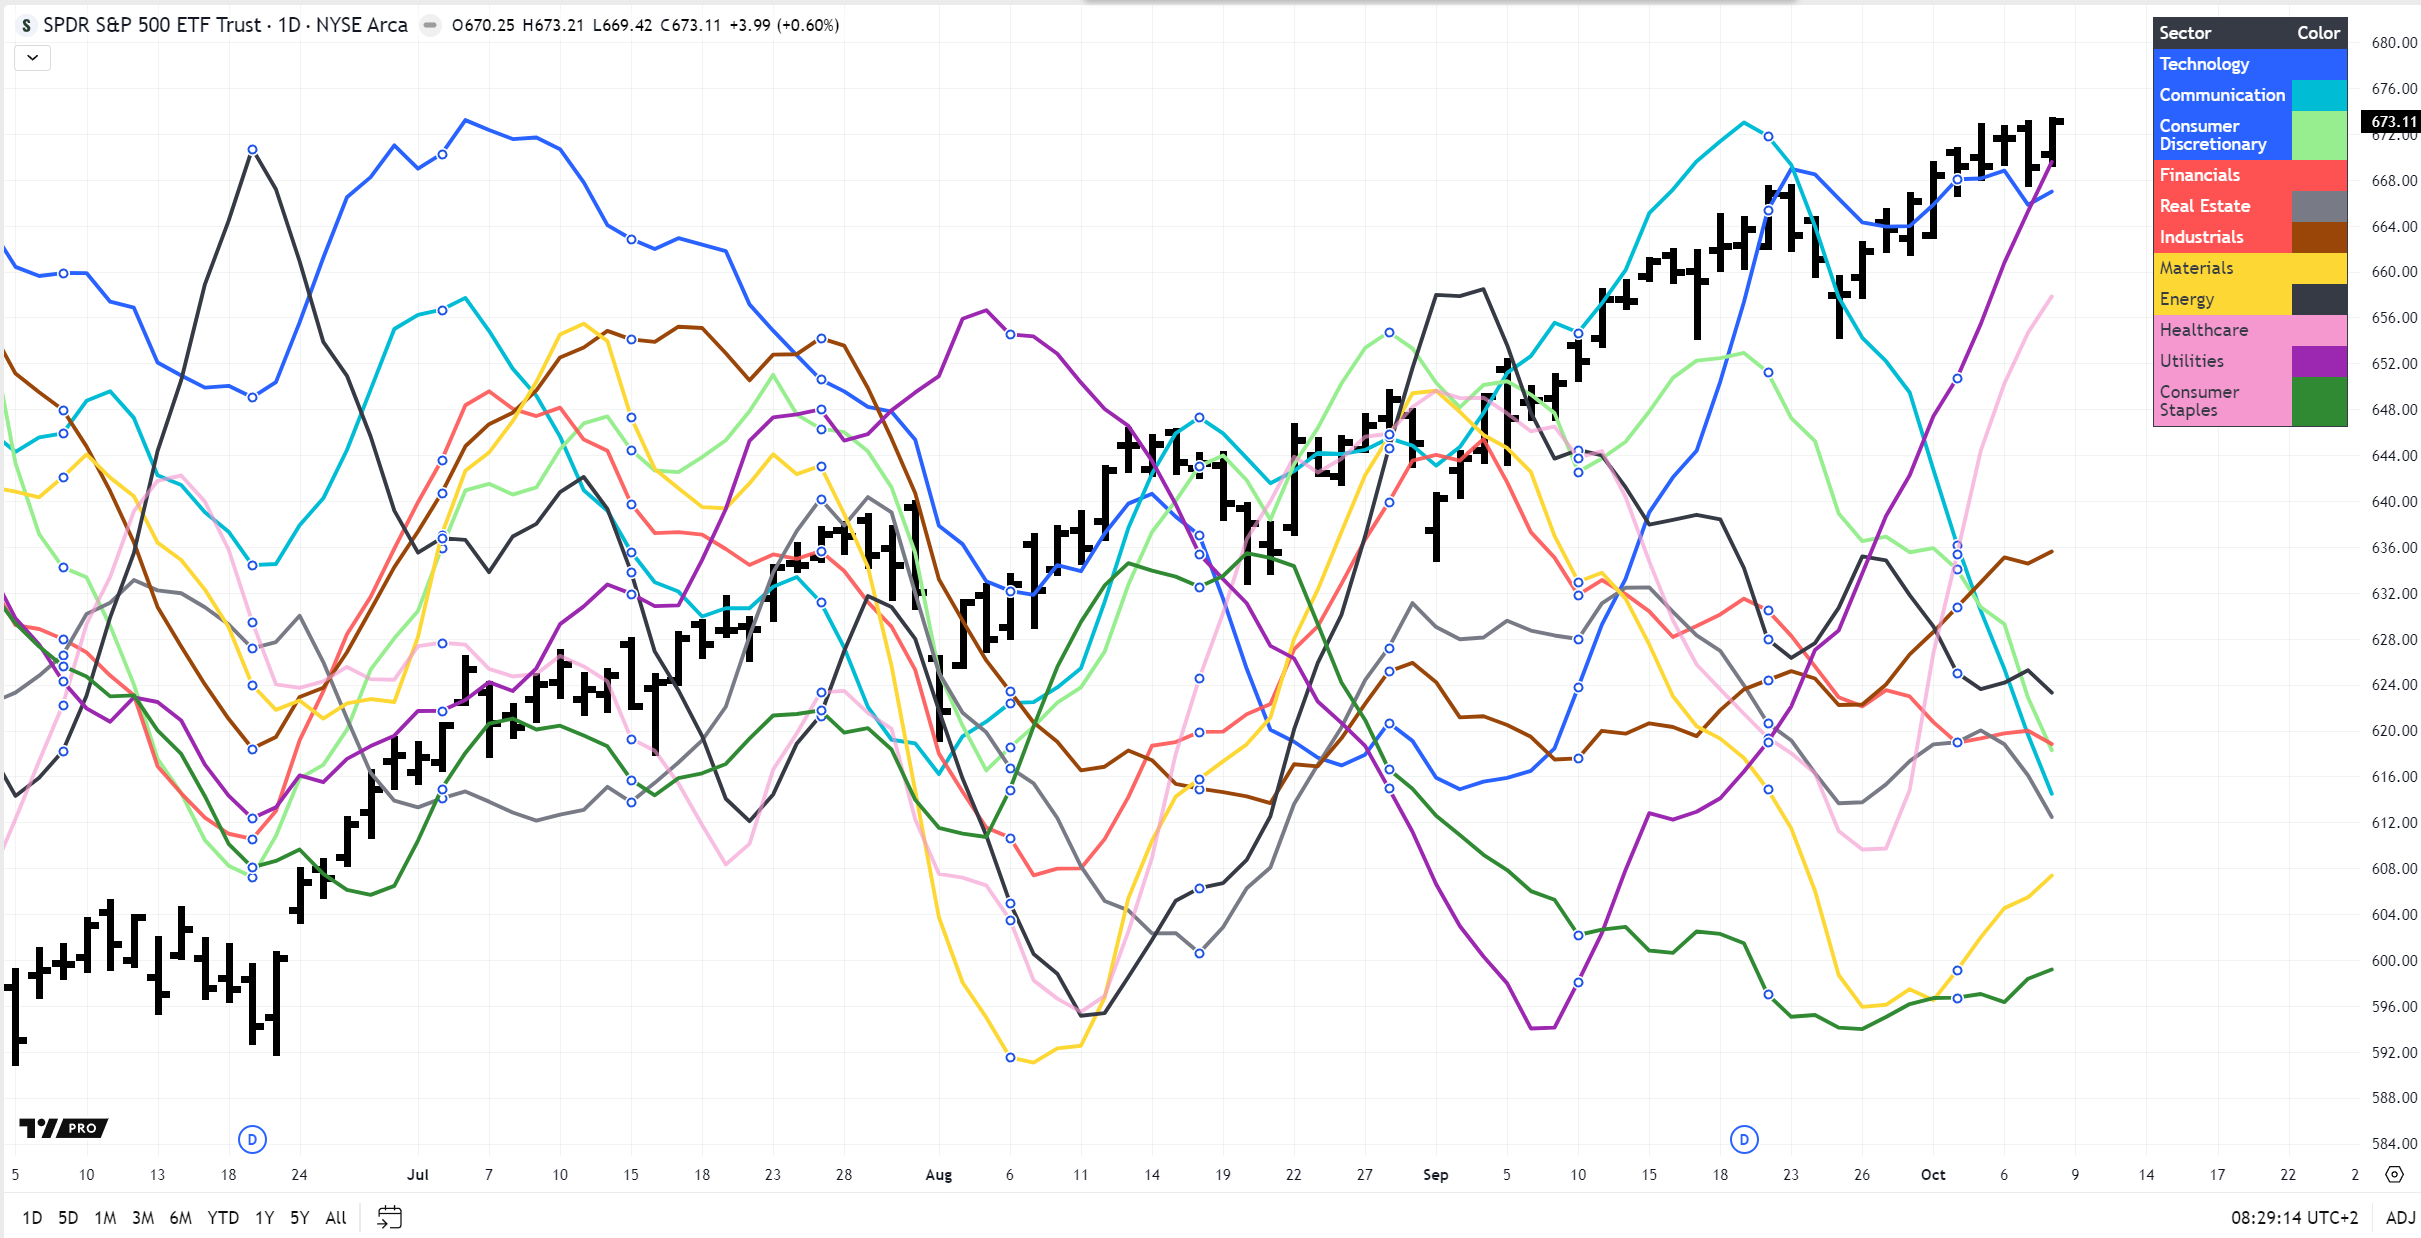 Strong: Utilities, Healthcare, Materials
Rotating In, Bottoming: Consumer Staples, Industrials
Rotating Out, Topping: Technology, Real Estate
Weak: Communication, Consumer Discretionary, Financials, Energy
Observations
Defensive sectors continue to lead and this is probably one of the few warning signals we have. The Real Estate sector should benefit from upcoming FED rate cuts, but it is extremely weak. Does this signal a potential crisis brewing in the sector? With technology being weak, we find ourselves clearly in the last leg of the bull market. This does not imply an imminent Sell-Off, but a shift in allocation and possible weakness in 2026.
BONUS - Sector Strenghts Stockpicking
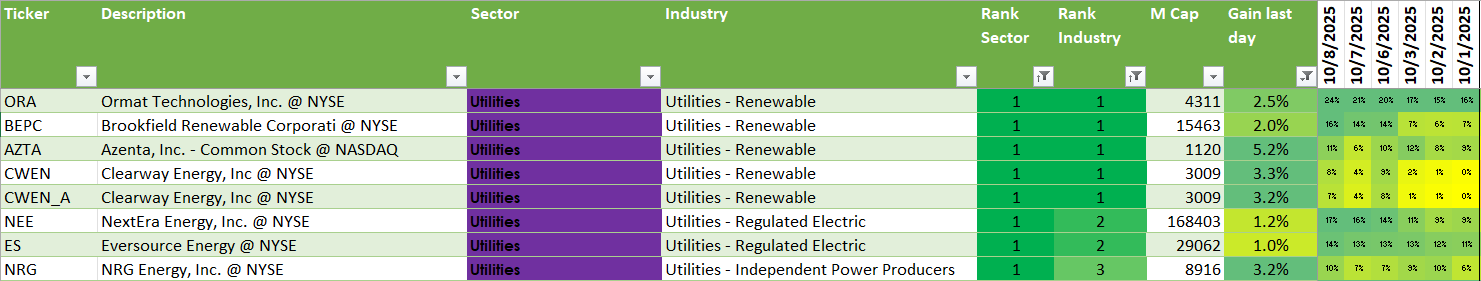
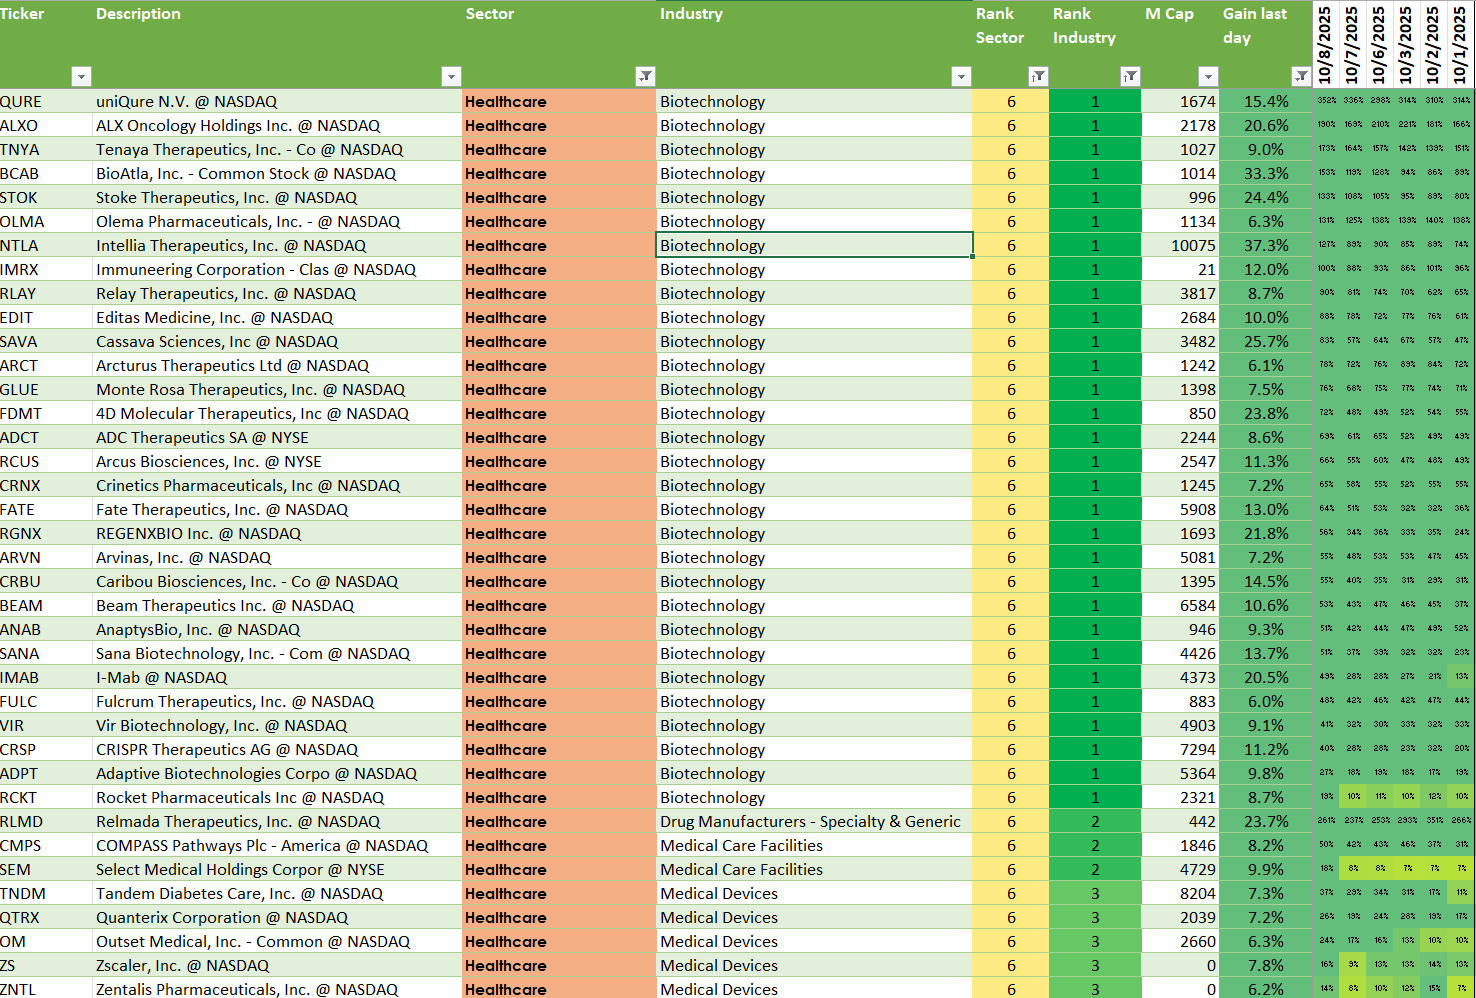
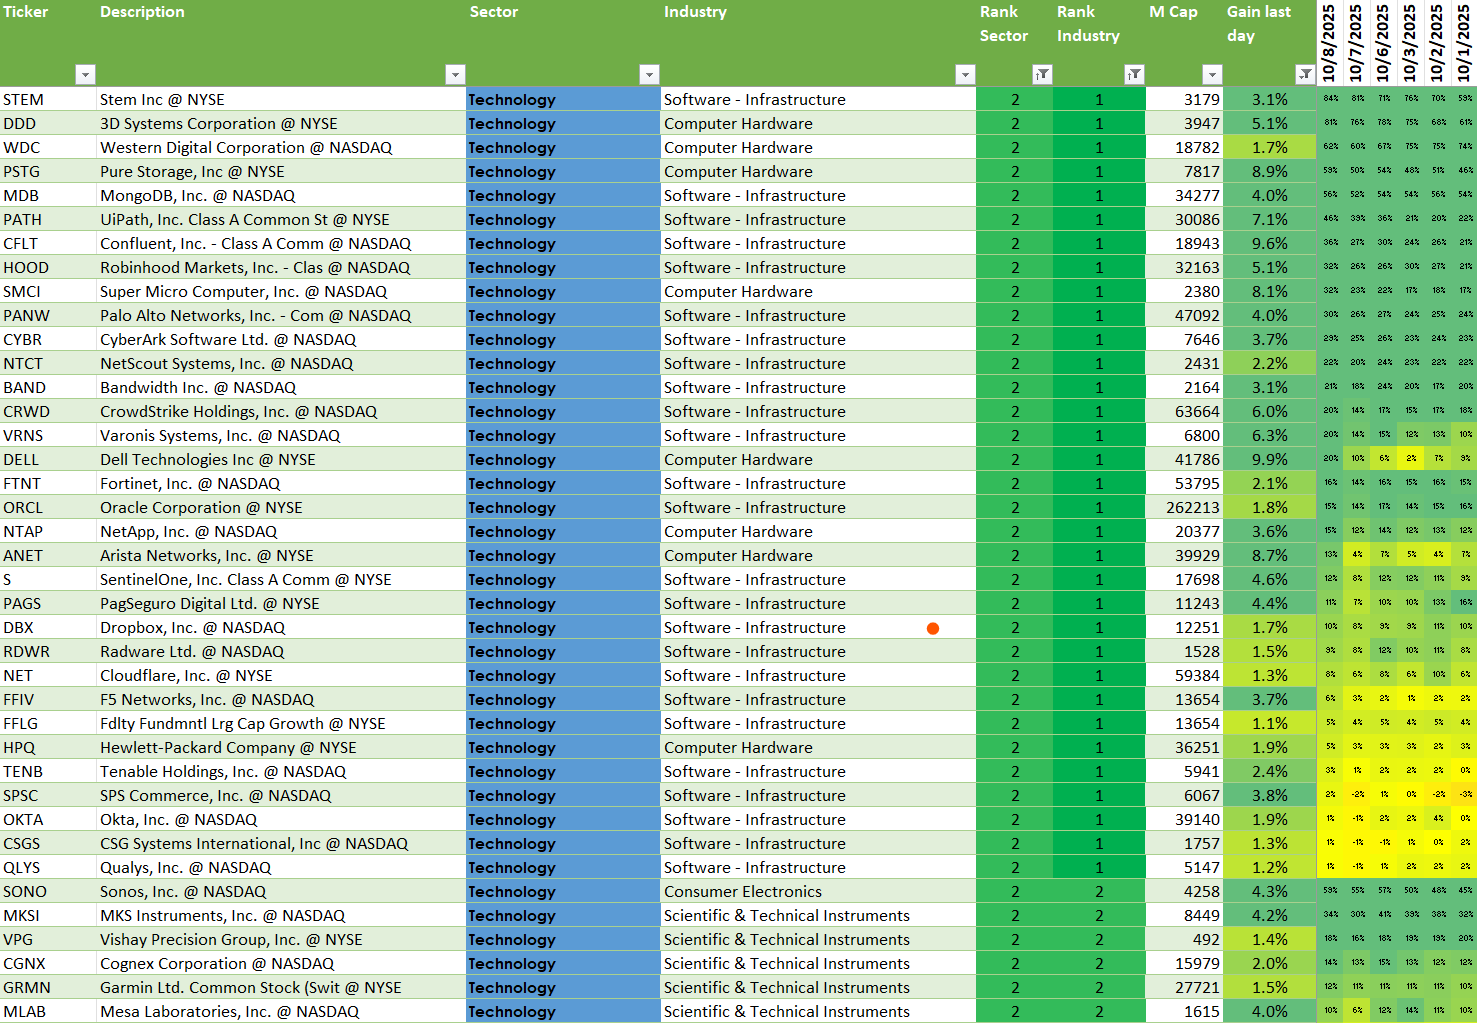
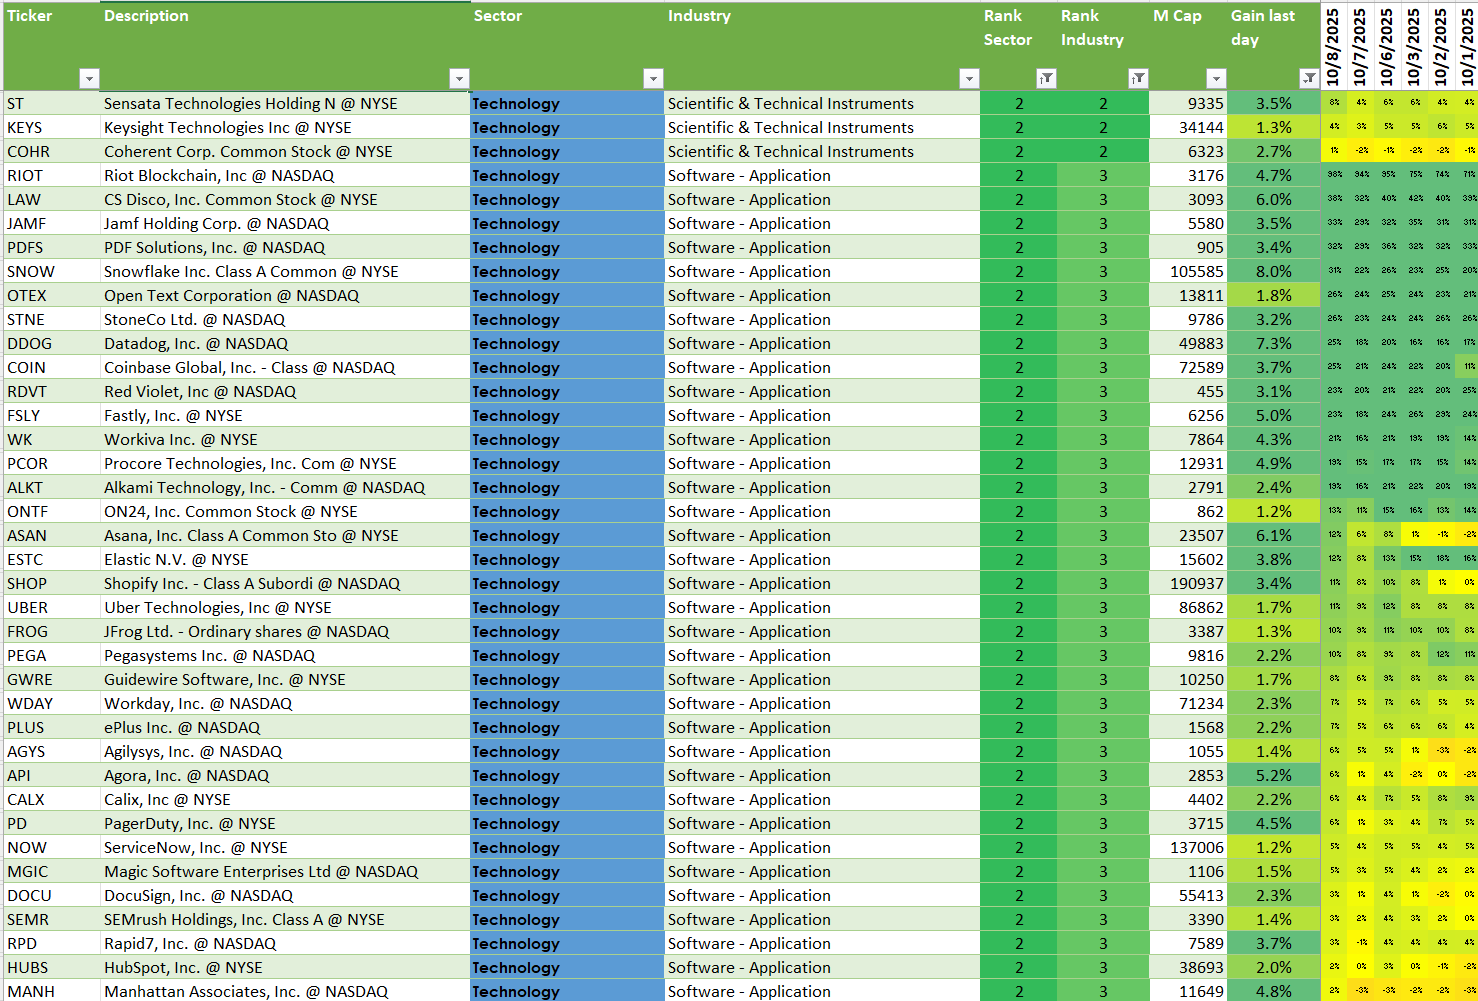
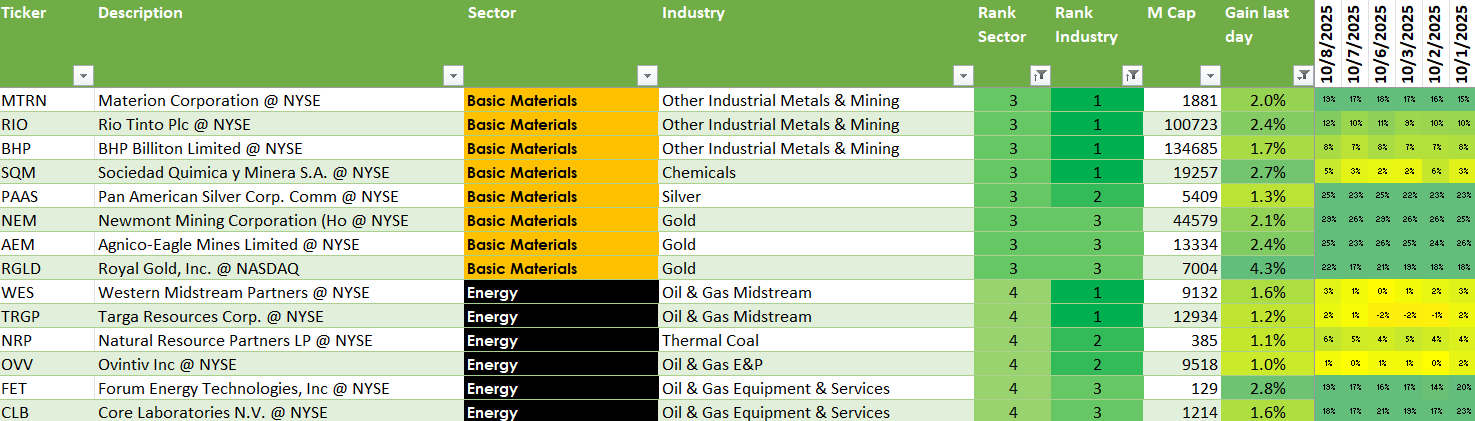
Stockpicking has become crucial in this market, in order to outperform the S&P. With Utilities, Technology, Energy and Materials being among the strongest sectors, it makes sense to breake this further down by branches and Industries.
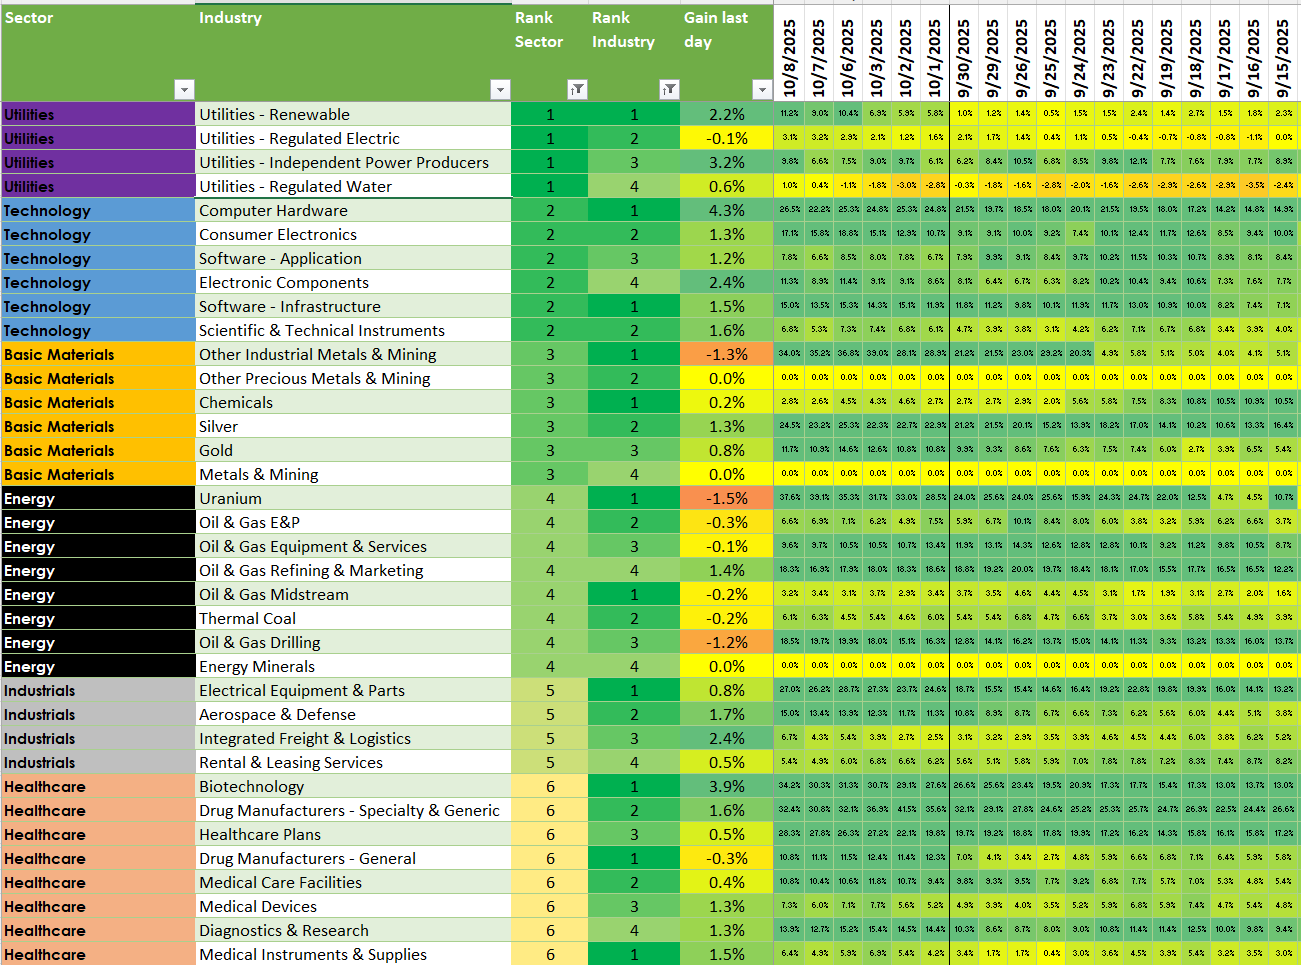
Finally, this approach allows to determine the strongest stocks among the strongest Industries of the strongest Sectors. And here we go:
Outlook - What to Expect and Market Reactions
| Theme / Driver | Anticipated Market Reaction | Caveats / Risks |
|---|---|---|
| Fed Speeches / Messaging | 🟢 Dovish tone: equities rally, yields fall. 🔴 Hawkish tone: risk assets sell off, yields rise. |
🟡 Without CPI or jobs data, traders may overinterpret minor wording changes — leading to exaggerated swings. |
| Consumer Sentiment (Univ. of Michigan, Oct Prelim) | 🟢 Strong sentiment supports cyclicals and consumer stocks. 🔴 Weak reading fuels defensives, bond bids. |
🟡 Survey data are “soft”; reactions may be overstated during the data blackout. |
| Treasury Auctions / Budget Statement | 🟢 Strong demand → yields stabilize, risk appetite improves. 🔴 Weak demand → yields rise, equities pressured. |
🟡 Technical flows may dominate while fundamentals remain opaque. |
| Liquidity & Volatility | 🟡 Elevated volatility likely continues — markets react to headlines, not fundamentals. | 🔴 Sudden political or geopolitical shocks can trigger sharp reversals. |
| Equity Market Tone | 🟢 Mild bullish bias if rate-cut narrative holds. 🔴 Fragile sentiment if yields spike or Fed tone hardens. |
🟡 Momentum trades prone to quick reversals; “buy-the-dip” less reliable. |
| Commodities / Precious Metals | 🟢 Gold stays firm above $4 000 as uncertainty lingers. 🟢 Energy supported by OPEC+ discipline. 🔴 Profit-taking possible if rates rise. |
🟡 Highly headline-driven; positioning crowded in gold. |
| FX / Dollar | 🟢 Risk-on → weaker USD. 🔴 Risk-off → safe-haven USD rally. |
🟡 Shutdown politics and global rate gaps create two-way volatility. |