Market Analysis
The sharp rise of the SP500 Indicator to nearly 30 is remarkable, yet the S&P 500 itself continues to lag, with rally attempts quickly being sold into. Overnight moves in the ES futures market appear disconnected from the cash session, creating a sideways trading range between 6600–6650 and 6700–6750.
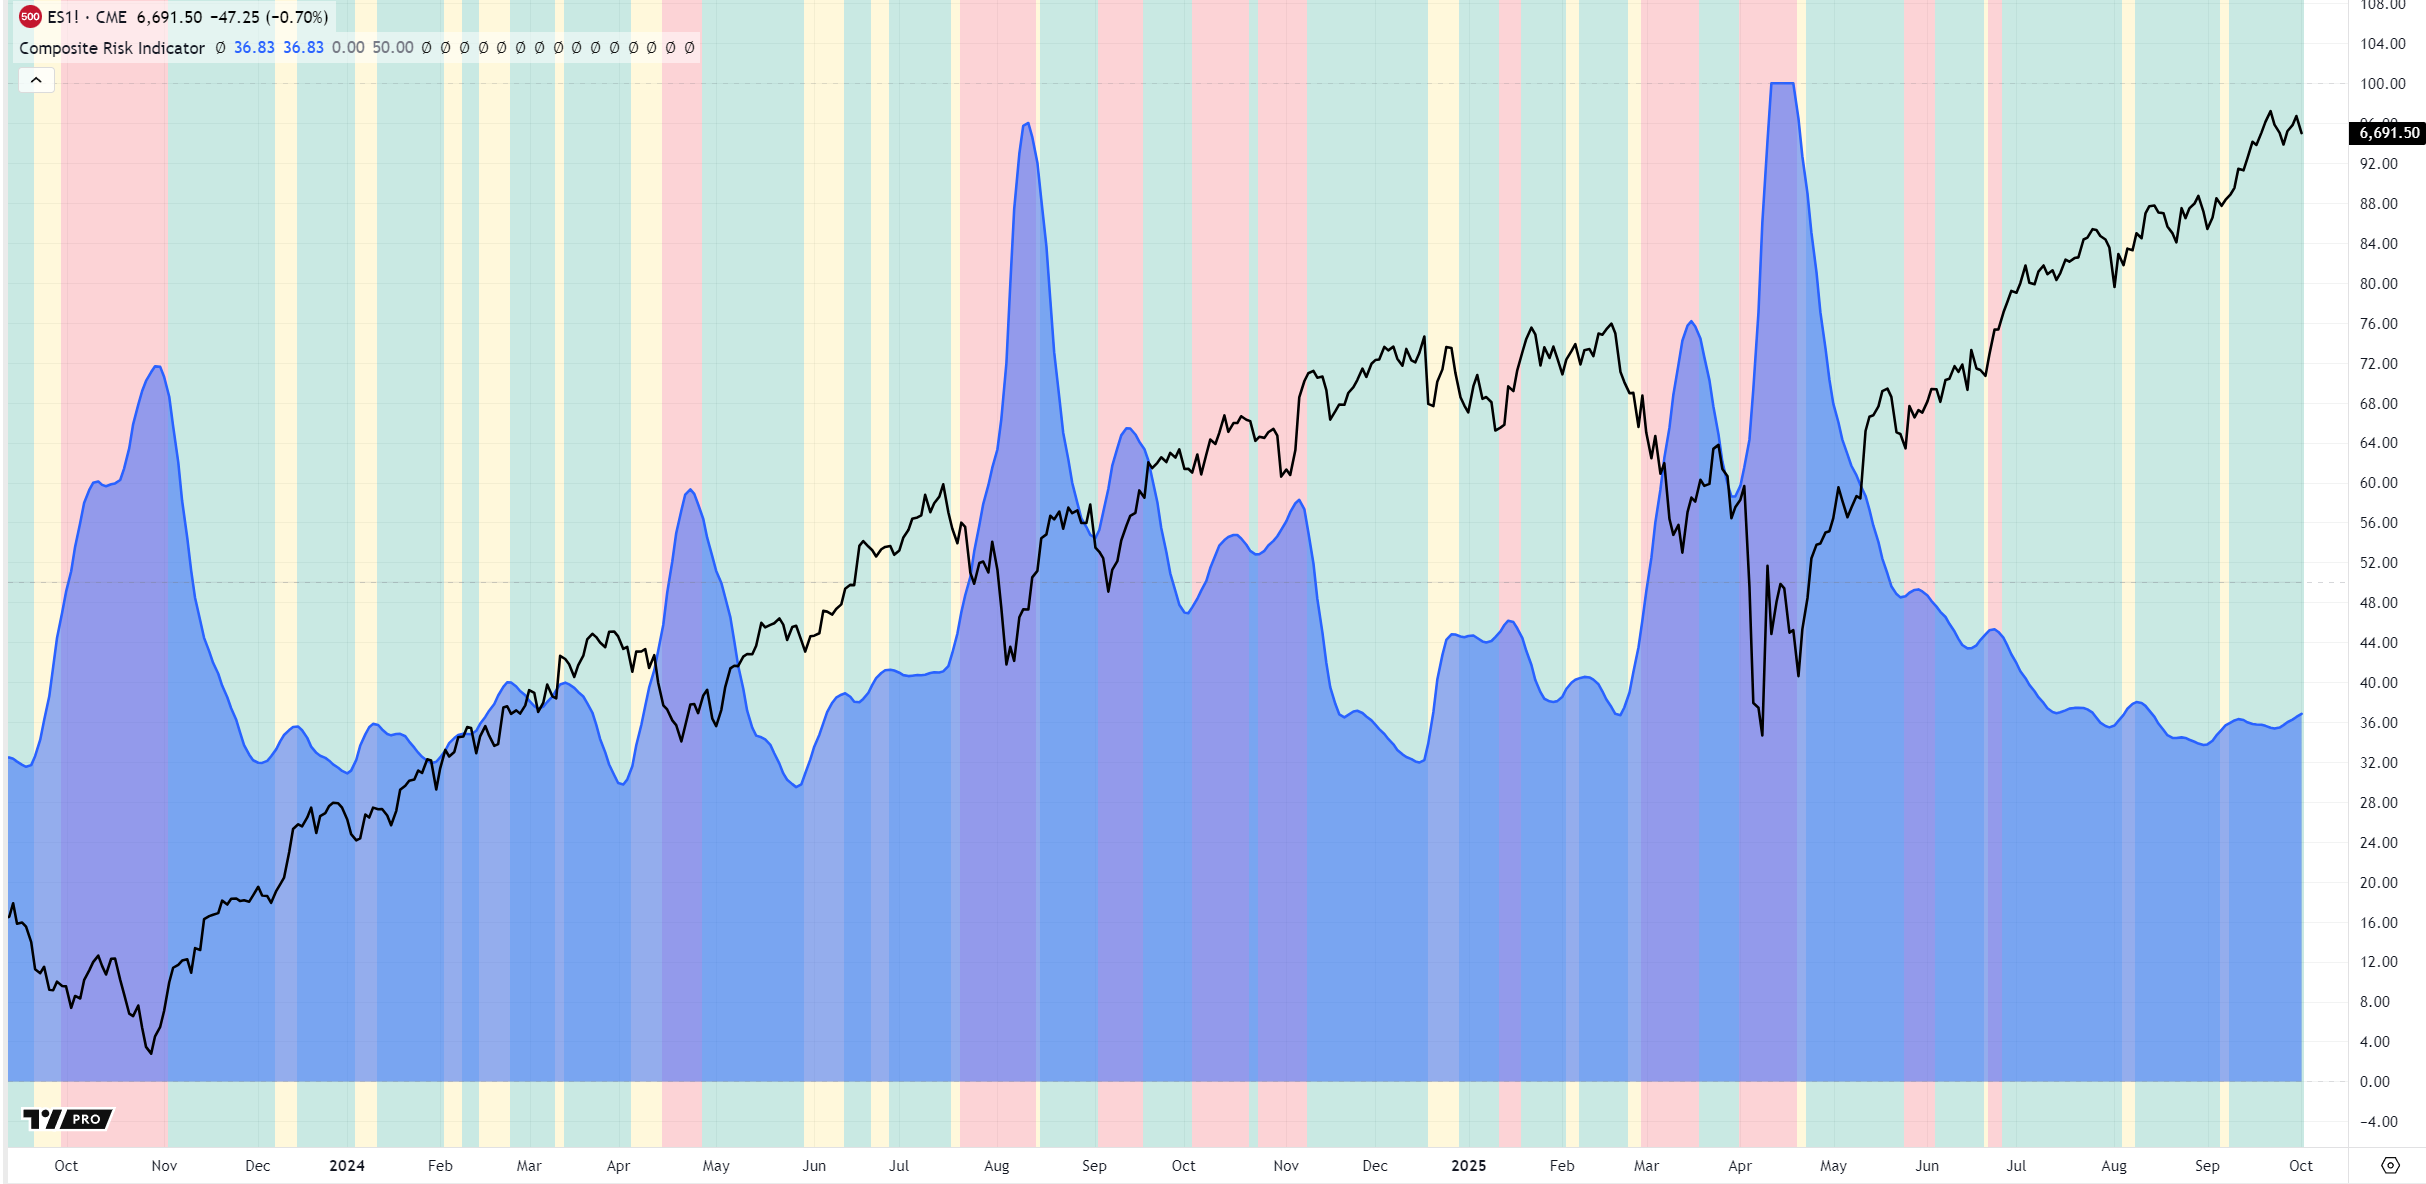
Meanwhile, perceived composite market risks — measured by gauges such as the VIX, MOVE Index, and credit spreads — remain strikingly low, though they have started to creep higher in recent days.
Sector Rotation
Sector rotation shows notable shifts: Consumer Discretionary, Communications, and large parts of Technology (NVDA being a partial exception) are significantly underperforming. On the flip side, Utilities continue to lead, while fresh money flows point to emerging opportunities in:
- Healthcare
- Real Estate
- Materials
- Consumer Staples
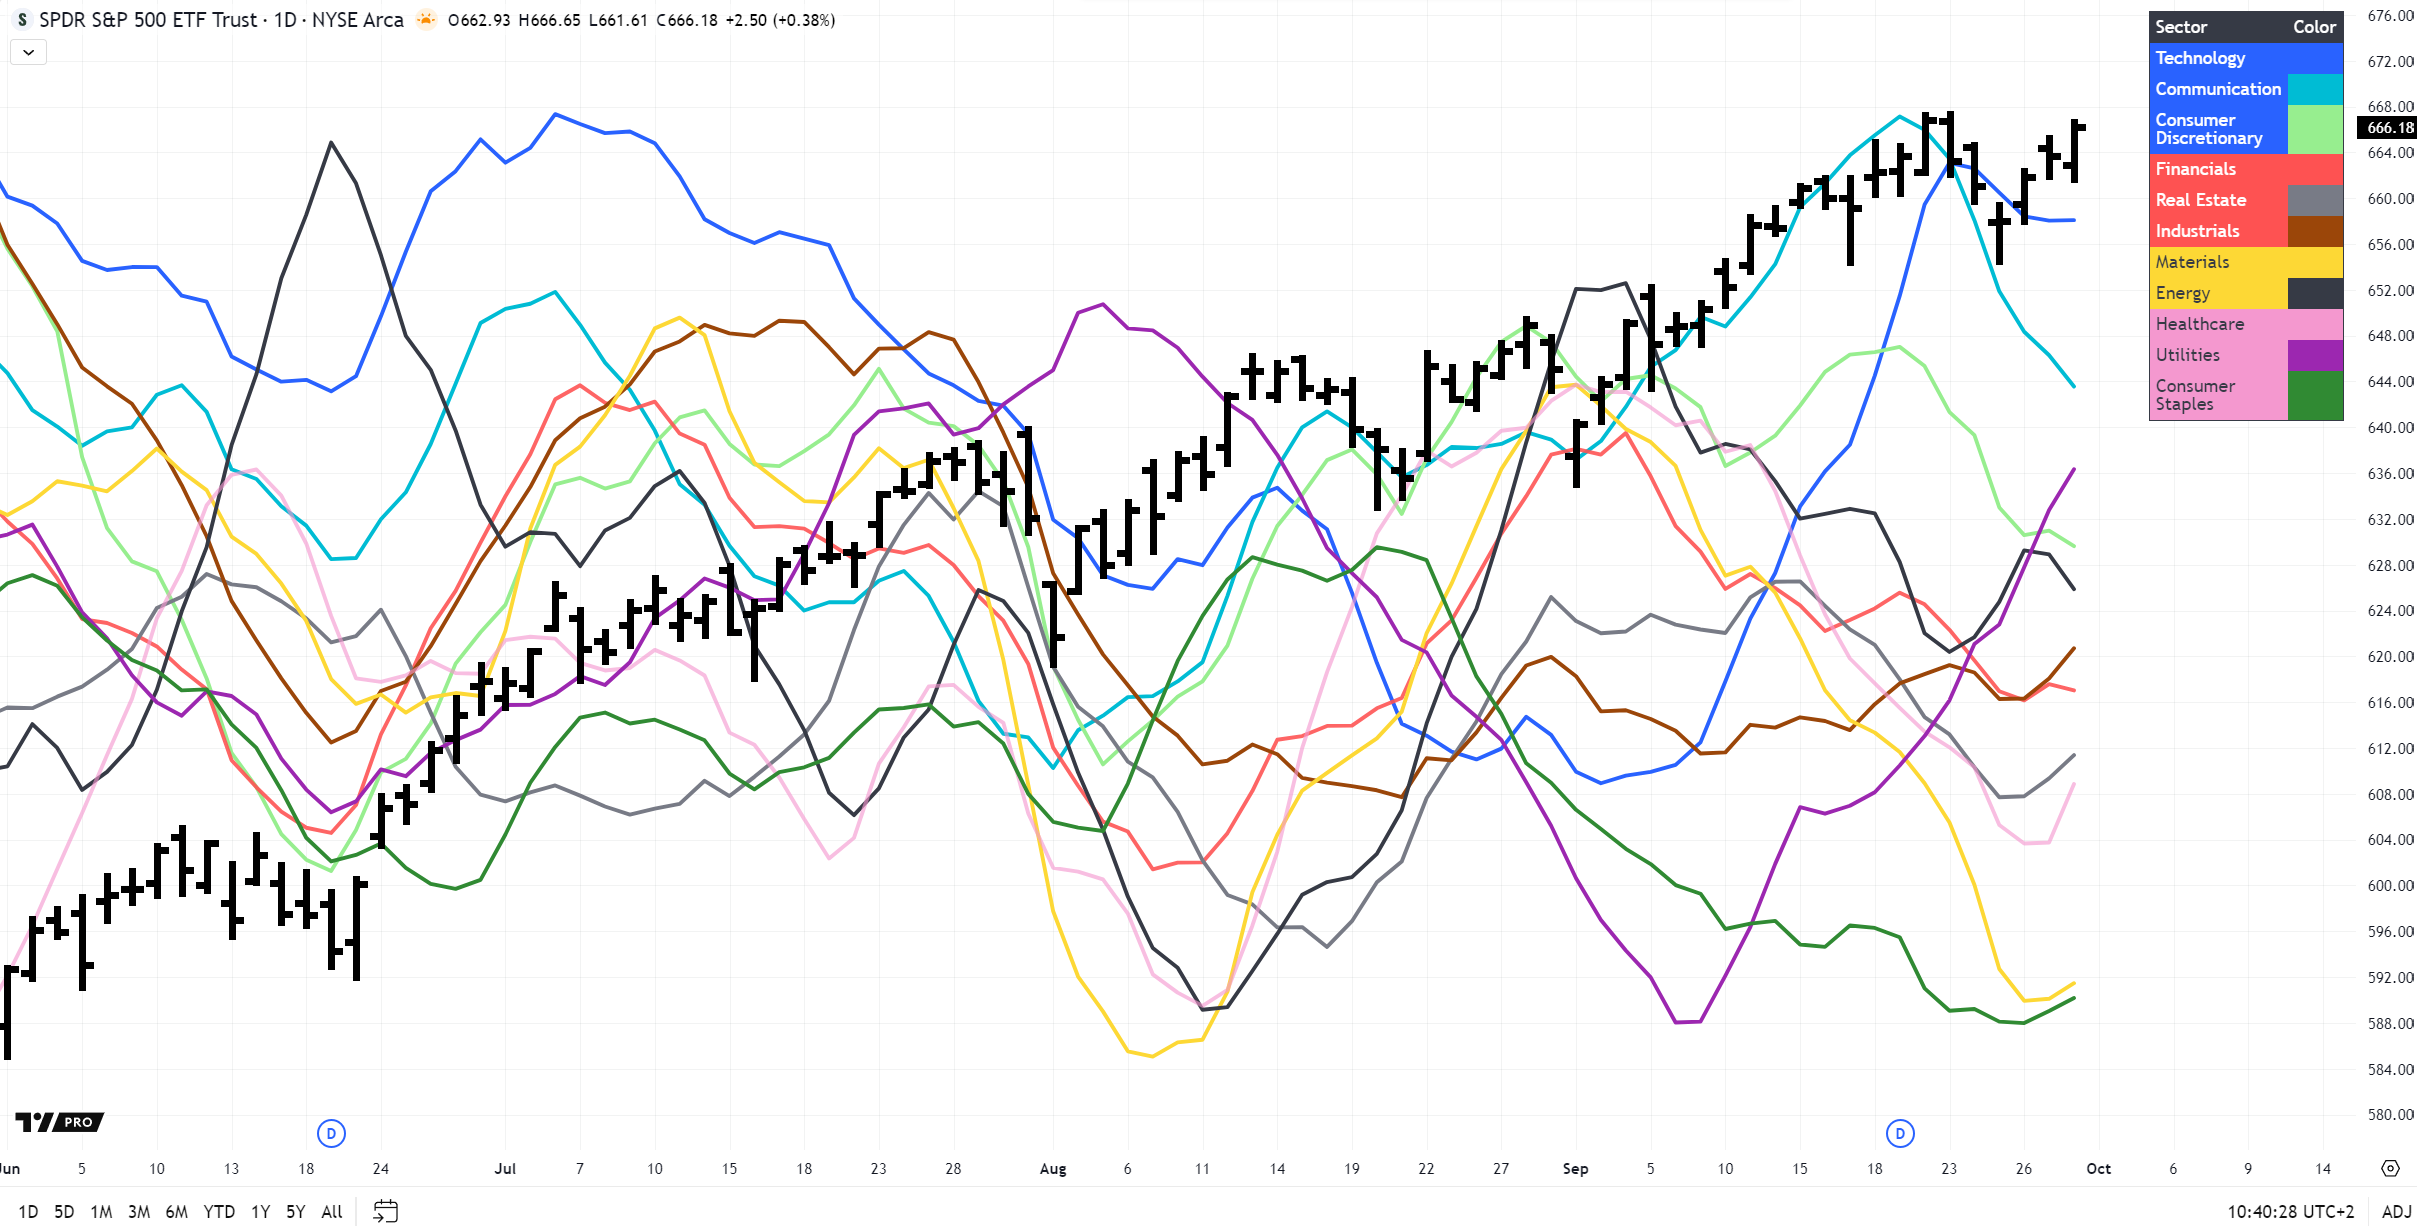
Healthcare, in particular, has seen a wave of insider buying and strong stock moves after years of underperformance since Trump took office.
Outlook
October, historically the weakest month of the year, is shaping up to be volatile. Conflicting forces are at play: a slowing economy, government shutdown risks, declining job openings, and rising unemployment stand against Fed-driven liquidity injections and ballooning U.S. government debt.
Not only gold, but also equities, are showing symptoms of excessive liquidity creation, which weakens the U.S. dollar and eventually fuels inflation. Trump’s renewed tariffs will likely accelerate this once companies begin passing higher costs through to consumers.
Short term: Sideways, with a potential bullish tilt.
Long term: High uncertainty, with rising risks of a bearish turn.