Market Analysis
The S&P 500 Indicator has slipped into caution territory after two consecutive declines and signals a potential mid-range breakout today. That’s unsurprising with the Fed’s rate decision looming.
Sector Rotation
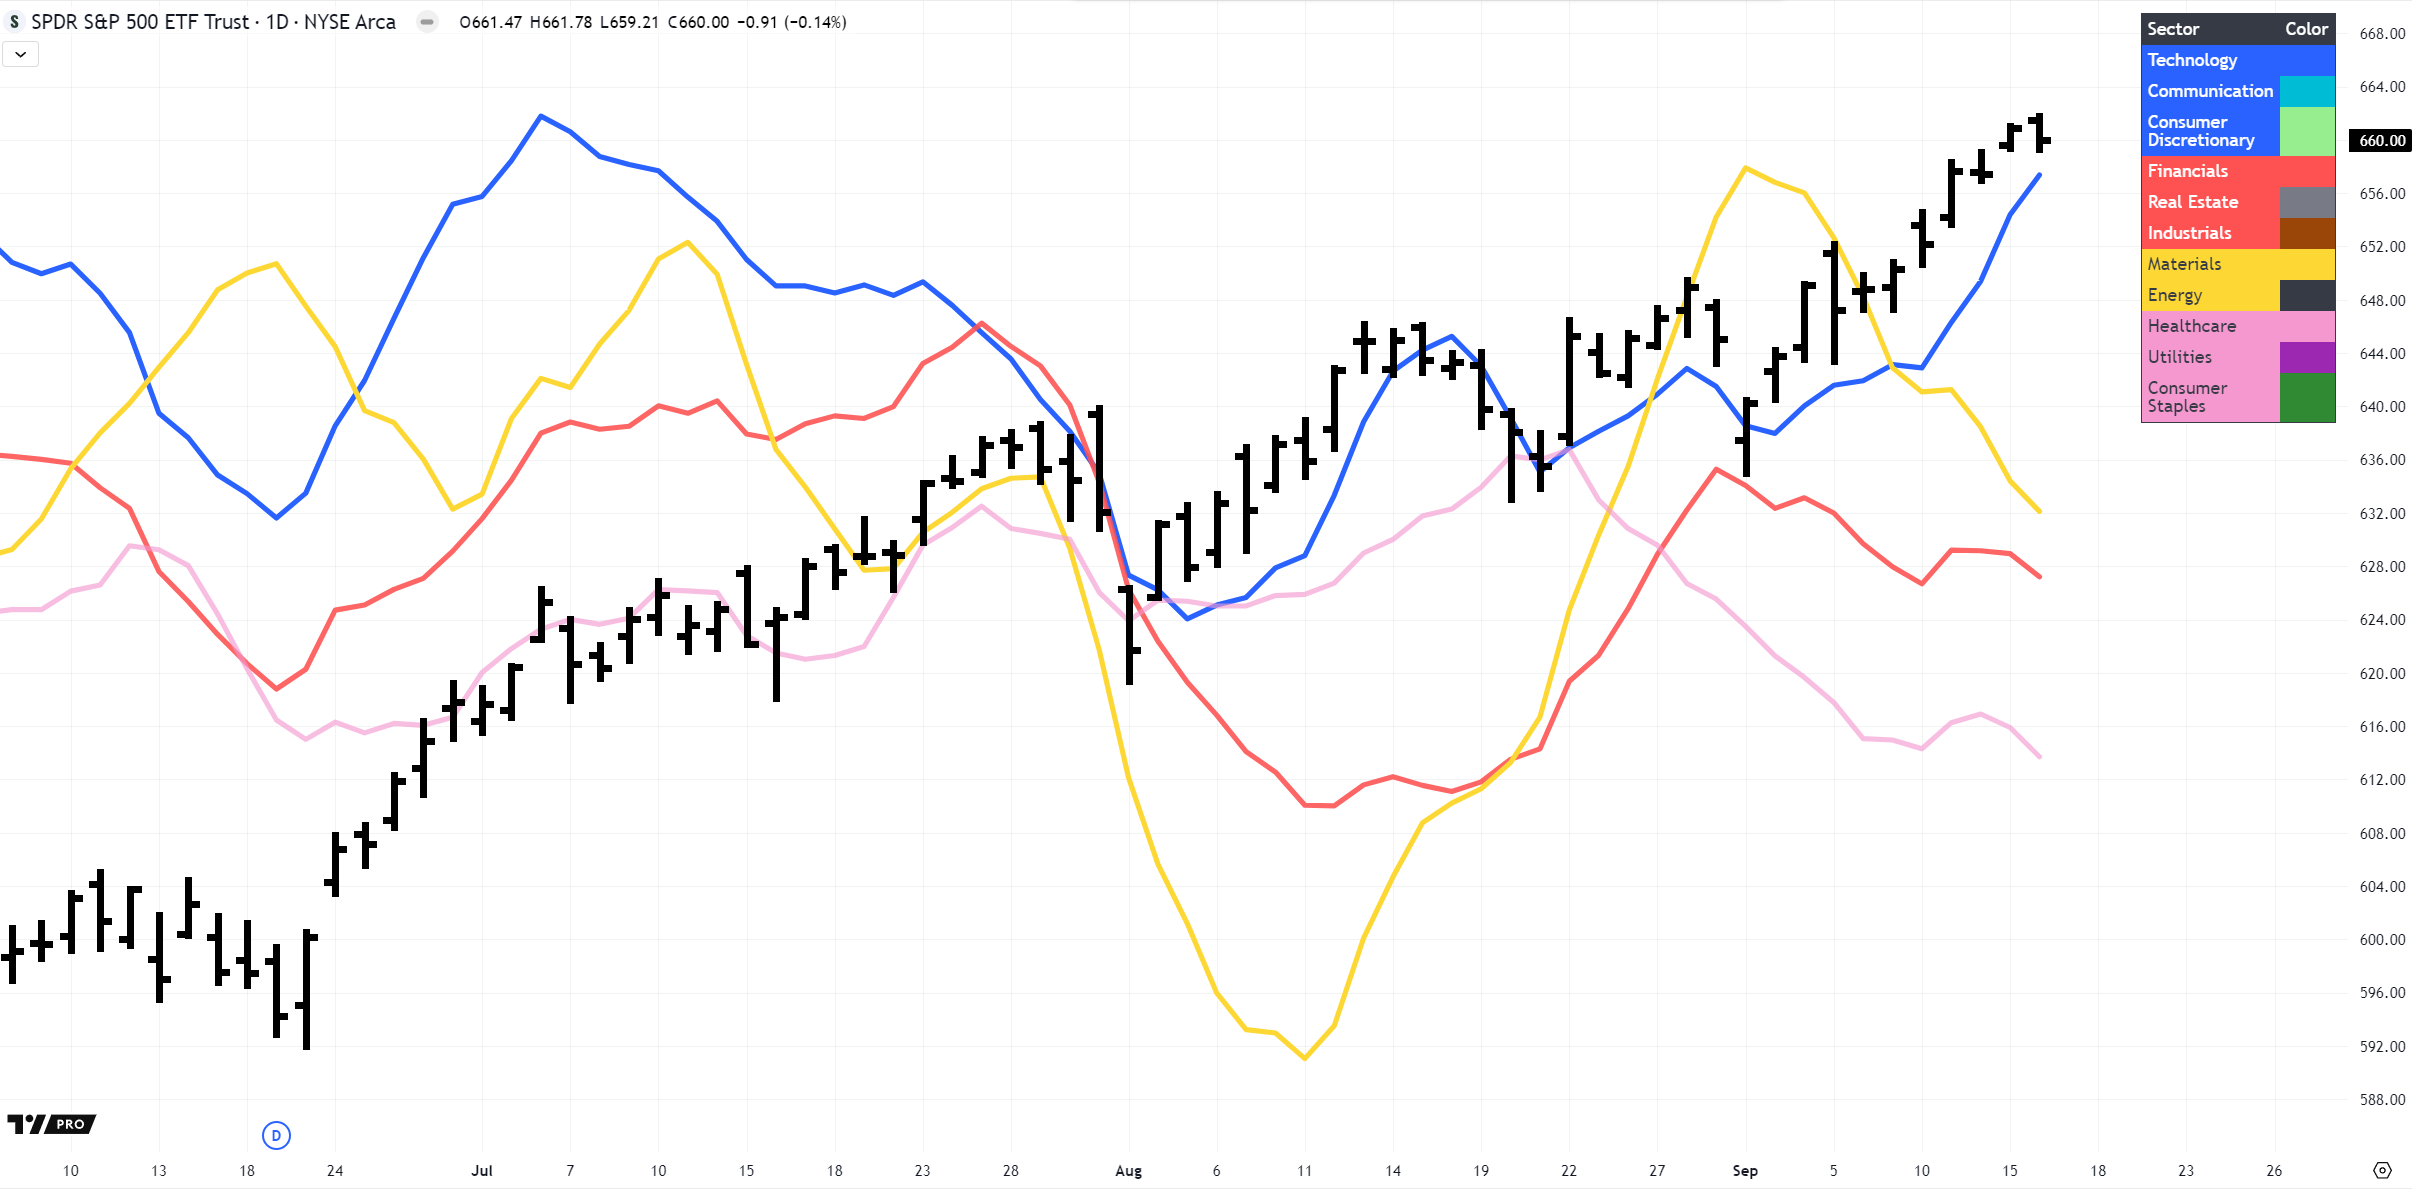
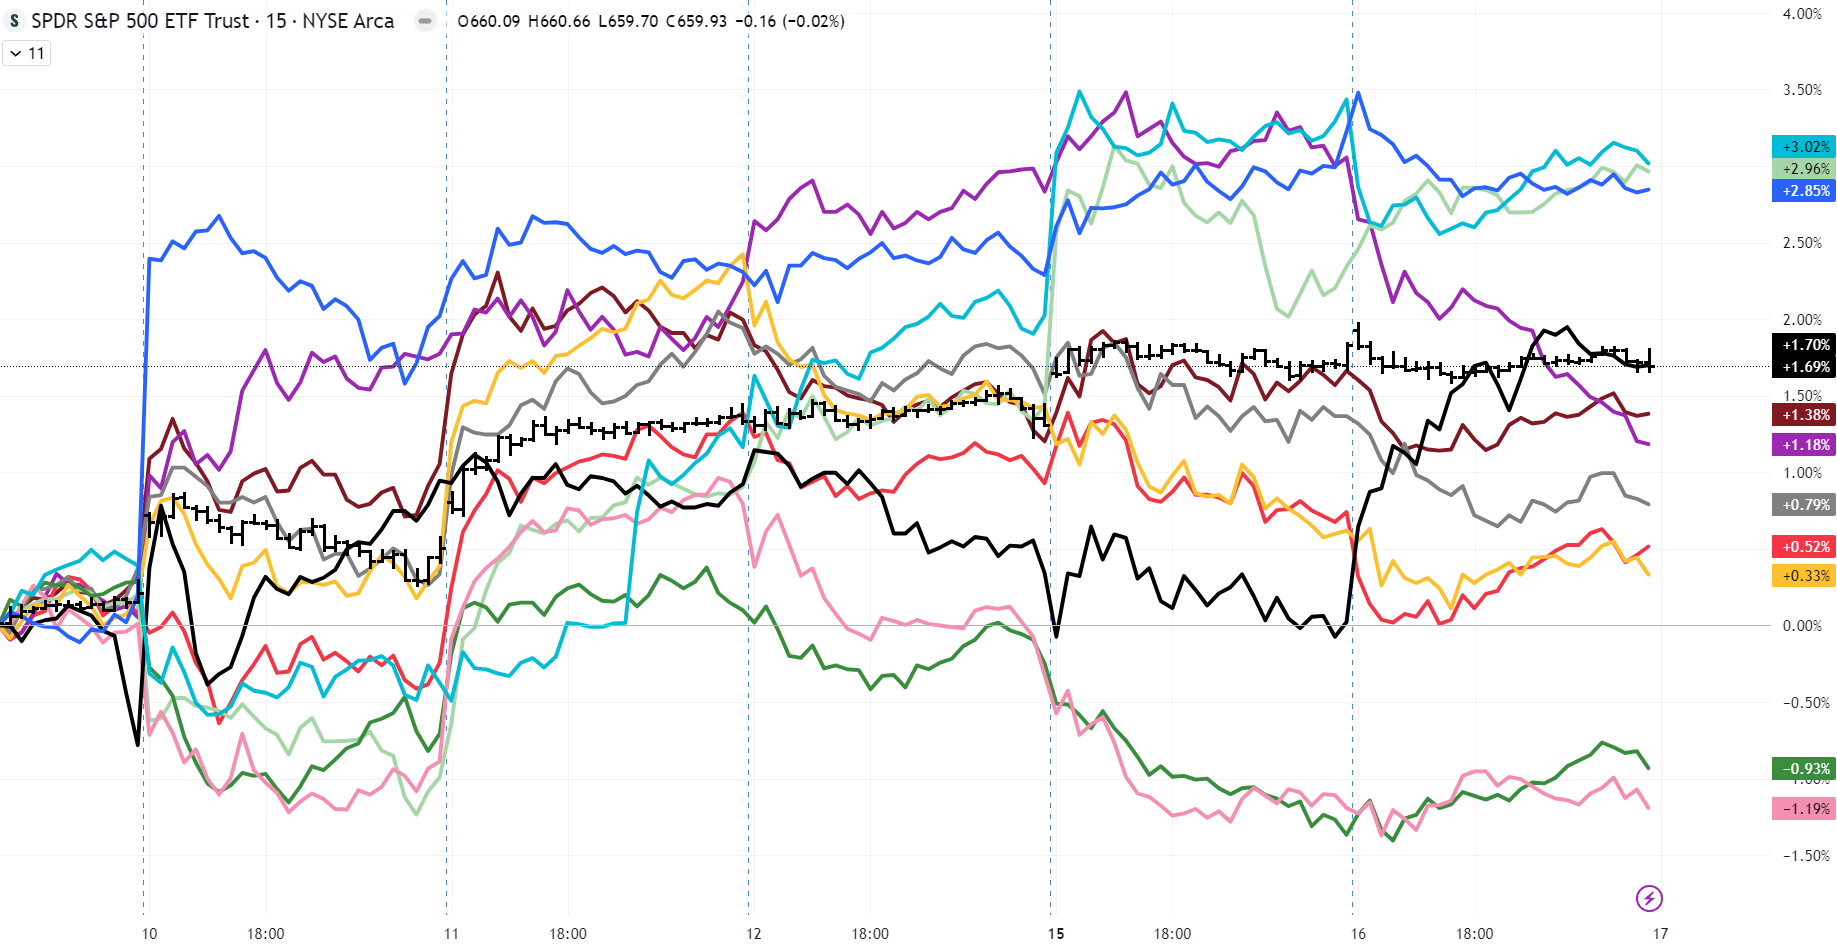
In the days leading up to the Fed, flows rotated into Growth sectors. This can be read as a move into perceived pre-Fed safety, since mega-cap U.S. tech firms with large cash balances are generally less sensitive to interest-rate moves than smaller or more leveraged companies.
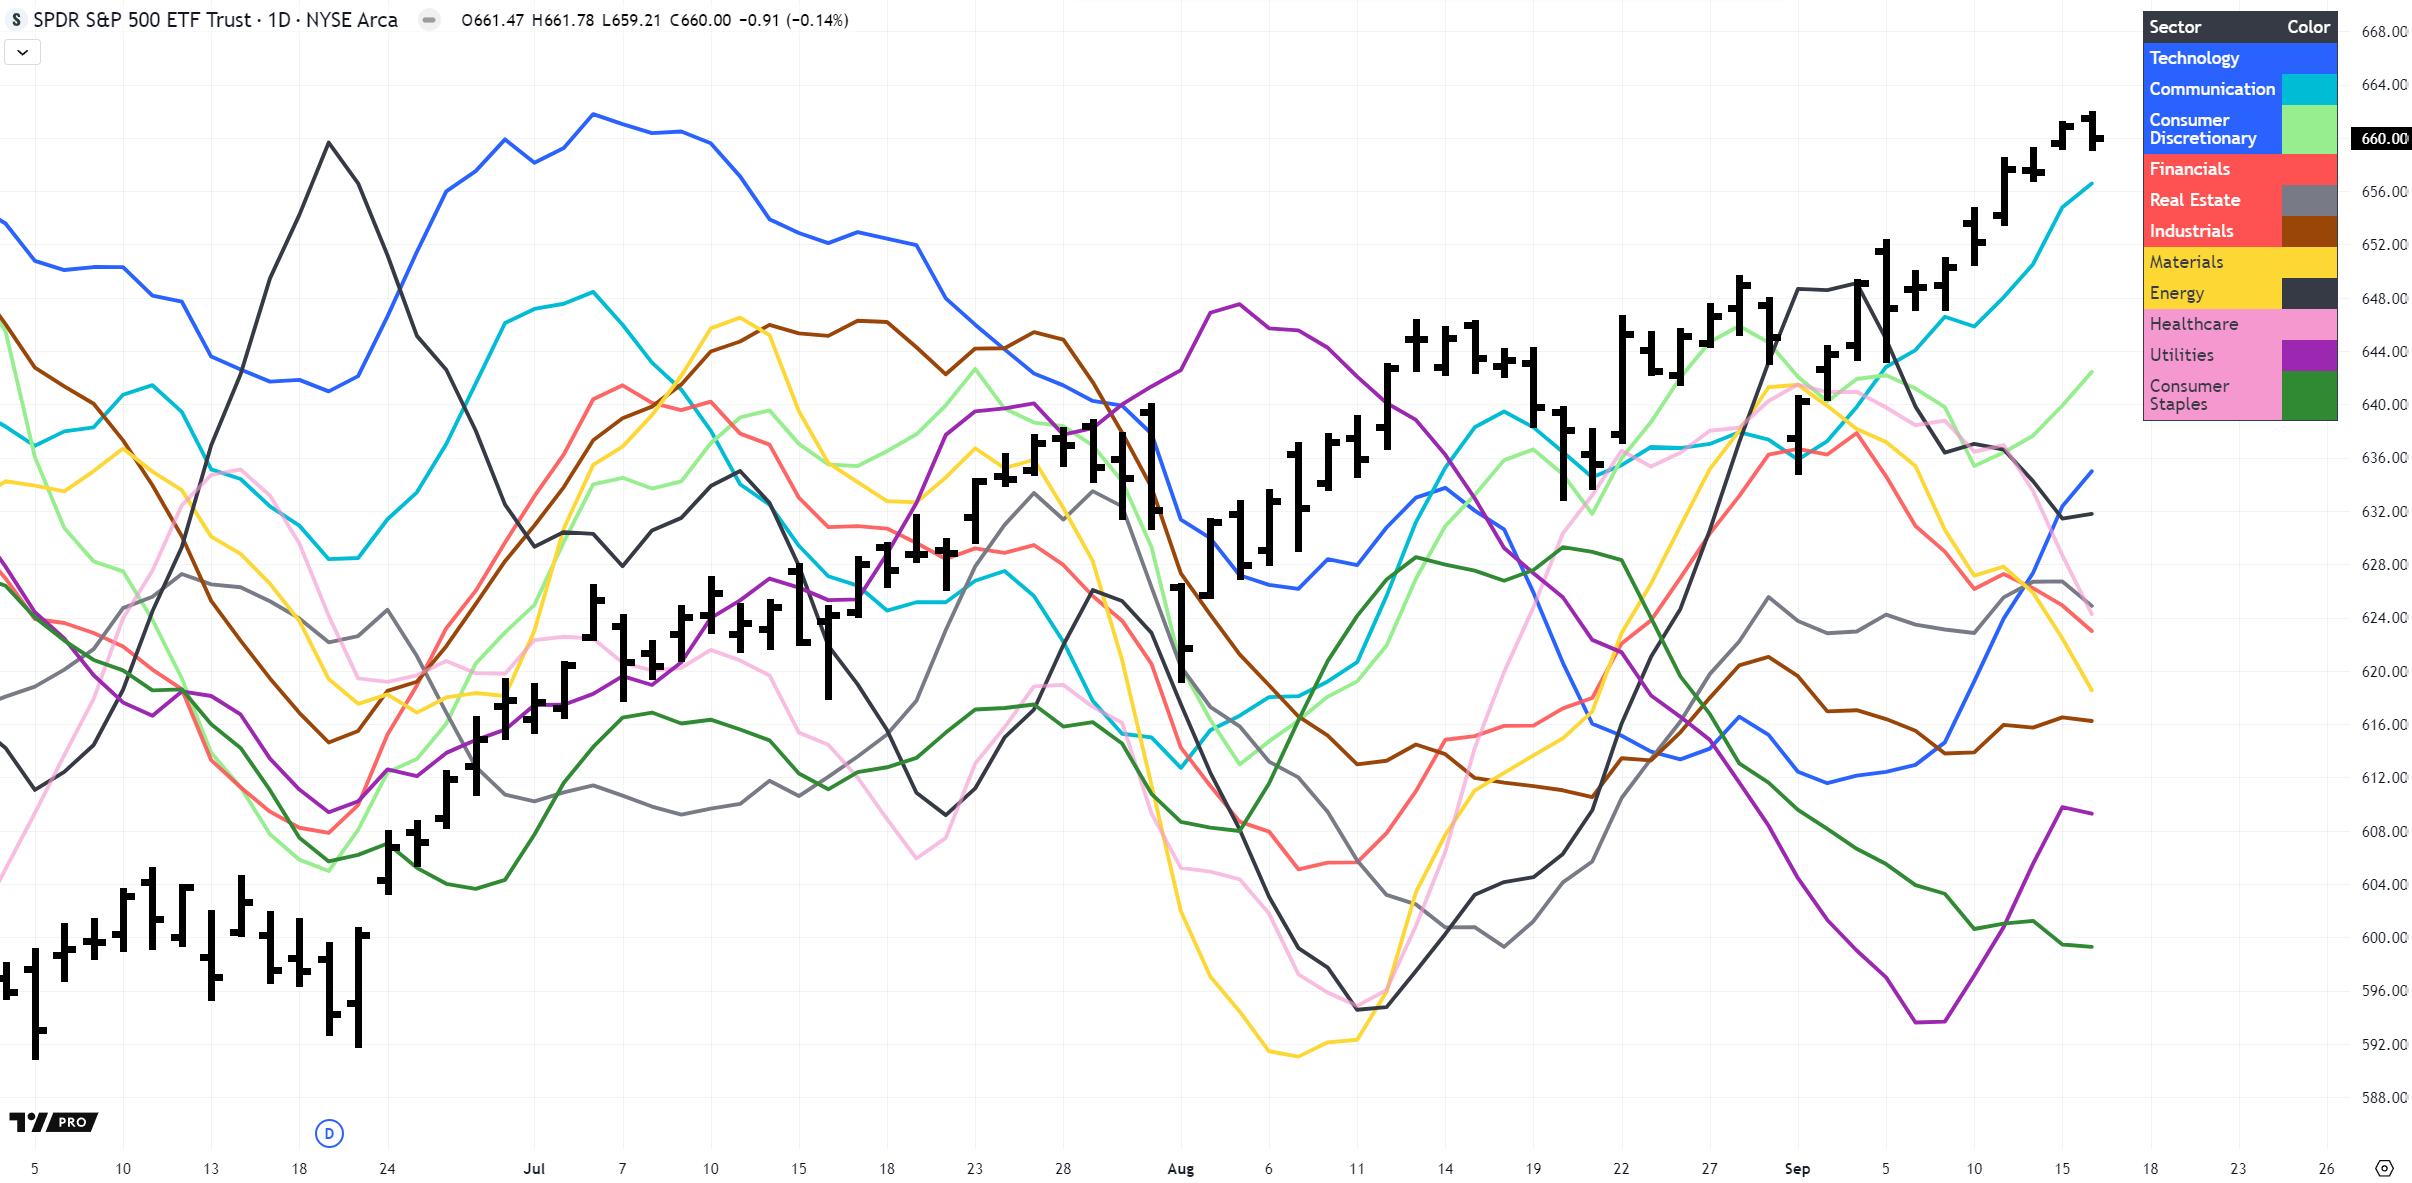
Financials, Value, and Defensives have lagged lately, but they could regain momentum once a rate cut is confirmed.
Mag10 Futures
Cboe announced the launch of new Mag10 futures and options, which may have supported the latest uptrend in these names. The upcoming Mag10 (MGTEN) contracts track ten highly influential U.S. tech/growth stocks (Alphabet, Apple, Amazon, Meta, Microsoft, Nvidia, Tesla, AMD, Broadcom, Palantir) in an equal-weighted index that represents a large slice of the S&P 500. Contracts are cash-settled, European-style, trade nearly 24×5, and include monthly, weekly, and 0DTE expirations, cleared via OCC.
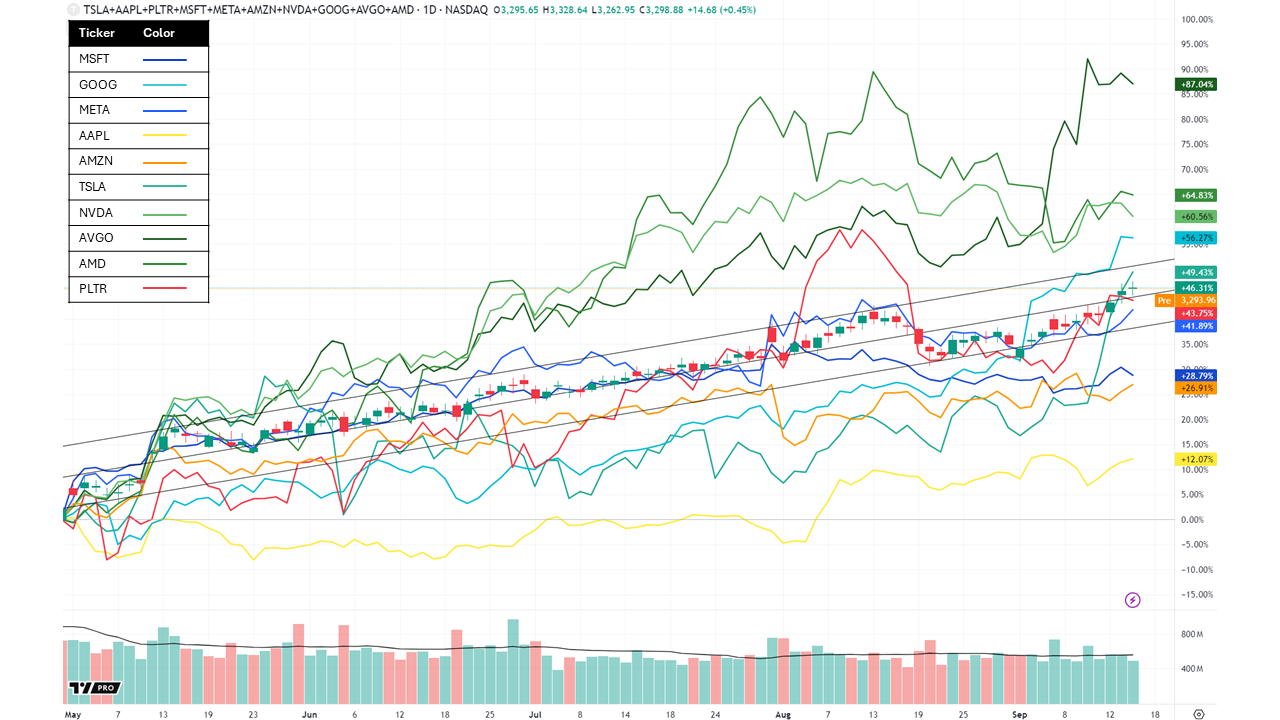
Within the Mag10, leadership has rotated: GOOGL, AVGO, and TSLA have recently outperformed, while NVDA, PLTR, and META lagged. Tesla rallied despite limited evidence of improving sales; if fundamentals do not follow through, the downtrend could resume. Nvidia has underperformed lately, and Apple continues to lag amid questions around product-cycle momentum.
Implications of Fed Rate Cuts for Mag10 Concentration
History suggests that Fed rate cuts can reduce market concentration by broadening participation toward smaller caps, cyclicals, and value. But context matters: a soft-landing cut tends to dilute mega-cap dominance, while a recession-driven cut can keep investors anchored in cash-rich tech.
Latest Drivers
- AI/Cloud CapEx: MSFT, AMZN, and META raised AI/cloud spending, reinforcing NVDA’s chip-demand outlook.
- Product Cycles: Apple’s iPhone/AI updates aided sentiment despite softer hardware trends.
- Competition Risks: AMZN’s pricing undercut on AI chips stoked margin concerns for NVDA.
- Regulatory Headwinds: U.S.–China export controls remain a drag for NVDA, AMD, and AVGO.
- Market Infrastructure: Cboe’s Mag10 contracts add new avenues to trade/hedge the basket.
- Flows to AI Enablers: NVDA and AVGO still benefit most from AI-driven CapEx.
- Cloud Platforms Rising: MSFT, AMZN, and META drew inflows on recurring AI-service revenue.
- Mixed Hardware Demand: AAPL and TSLA showed weaker momentum versus software/cloud leaders.
- Speculative Interest: PLTR saw renewed flows on AI + government-contract themes; AMD lagged NVDA in GPUs.
Market Outlook: What to Expect from the Fed
The Fed’s decision is the pivotal near-term driver. According to the CME FedWatch Tool, a 25 bp cut is the strong base case. Anything else would catch markets off guard.
🔴 No Rate Cut (unlikely)
- Market Reaction: Hawkish surprise; yields up, front-end steepening, equities sell off.
- S&P 500 Outlook: Possible sharp pullback toward 6,300–6,350; growth/high-beta hit hardest.
- Narrative: Inflation risks still dominate growth concerns.
- 🔴 Long-Term Effects: A decision to hold rates could strengthen the Fed’s inflation-fighting credibility but risks tightening financial conditions too far. Corporate refinancing costs would remain elevated, credit stress could rise, and equity market breadth may weaken further as smaller firms struggle. This path could raise the odds of a harder landing in 2026.
- Beneficiaries: Utilities, Staples, Healthcare (defensives)
Laggards: Tech, Growth, Small Caps
🟡 0.25 bp Cut (base case)
- Market Reaction: Largely priced; initial volatility likely fades.
- S&P 500 Outlook: Near recent highs (6,600) with modest upside; expectations cap the move.
- Narrative: A steady-hand adjustment acknowledging slower growth.
- 🟡 Long-Term Effects: A gradual cutting cycle may encourage a soft landing, with improved credit conditions helping small and mid-cap firms. Market concentration in the Mag10 could slowly ease as capital rotates into cyclicals and value. Still, if inflation proves sticky, the Fed risks being forced into a stop-start cycle, creating longer-term uncertainty.
Beneficiaries: Financials, Industrials, Value stocks
Laggards: Pure defensives, late-cycle growth names
🟢 0.50 bp Cut (tail risk)
- Market Reaction: Dovish surprise; yields drop, USD softens, risk assets rally.
- S&P 500 Outlook: Potential break above 6,600 to new highs, but raises questions about underlying growth.
- Narrative: Aggressive easing hints at deeper economic cracks.
- 🟡 Long-Term Effects: While liquidity-sensitive assets would benefit initially, such an aggressive move could be read as a signal that the Fed sees hidden fragilities in the economy. If growth does weaken sharply, defensive sectors and mega-cap tech may retain dominance as investors seek safety. Over time, this could entrench market concentration and fuel renewed volatility if confidence erodes.
Beneficiaries: Tech, Growth, High-Beta, Real Estate
Laggards: Energy (if recession fears dominate), some cyclicals