Market Analysis
The Indicator edged lower but remains firmly in positive territory. Despite persistent selling pressure, the S&P 500 advanced within the 6,400–6,500 range, closing just above its 20-day moving average (MA20). The market continues to display remarkable resilience, with every dip swiftly absorbed. Although no clear accumulation patterns were detected, price action suggests a potential base-building phase around the MA20. This strengthens the case for a short-term rally toward the 6,500 resistance zone and potentially a fresh all-time high (ATH).
Market Influencers
What moved markets
- Tech rebound led by Alphabet: A double-digit surge in Alphabet lifted the broader tech sector, helping the S&P 500 and Nasdaq recover part of Tuesday’s losses.
- Yields eased: A decline in Treasury yields supported risk assets by boosting expectations for Fed rate cuts.
- Earnings beats in consumer names: Macy’s and Campbell’s delivered strong results and upbeat guidance, lifting discretionary and staples.
- Idiosyncratic losers: Dollar Tree slid despite beating expectations, with investors focused on tariff and margin risks.
Context from the prior day (Sep 2)
- Tariff uncertainty + bond volatility: Renewed tariff headlines and perceived Fed independence risks triggered a sharp, rates-driven equity sell-off.
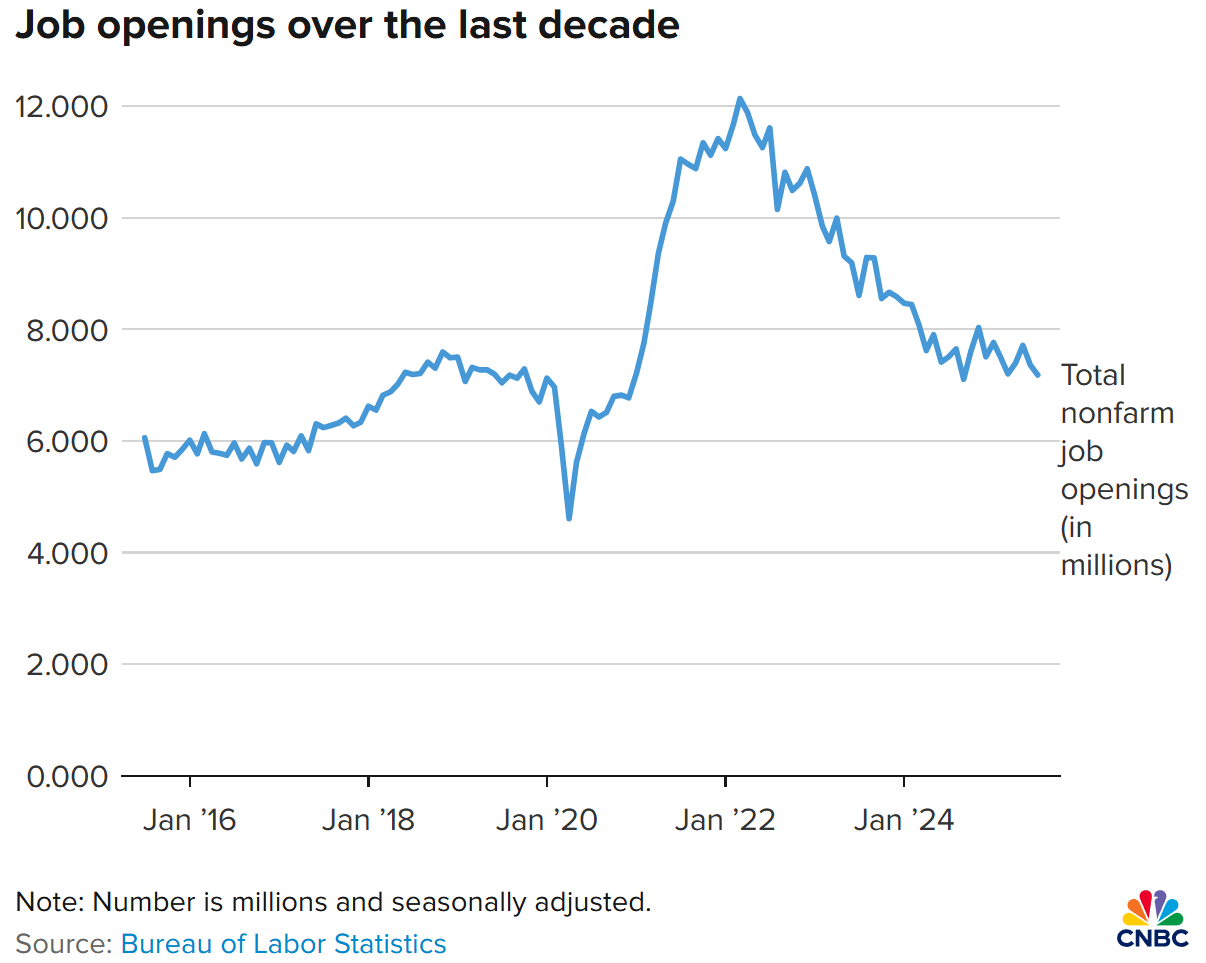
While falling yields might appear constructive, the underlying driver is less comforting: U.S. Treasuries surged (CNBC) after the latest JOLTS report showed a sharp drop in job openings—levels rarely seen since the pandemic. This rekindled concerns over a slowing labor market and intensified speculation that the Federal Reserve may need to cut rates more aggressively. The 30-year yield retreated from the symbolic 5% threshold to 4.9% as investors repriced policy expectations.
The buying wave was broad-based, with pension funds, insurers, and asset managers leading demand for long-duration Treasuries. Foreign central banks were also seen as likely participants, reinforcing the global bond rally. Even without direct Fed intervention, the combination of rate-cut speculation and a flight-to-safety narrative anchored Treasuries at the center of global risk-off positioning.
Takeaway and Outlook
- Breadth remains narrow and rates-sensitive: Mega-cap tech leadership and bond-market dynamics continue to dictate index direction.
- Immediate catalysts: This week’s ADP employment, ISM Services PMI, and Balance of Trade (Sep 4), followed by the critical Nonfarm Payrolls, unemployment rate, and average hourly earnings (Sep 5), will set the tone for near-term positioning.
- Strategic view: A “Goldilocks” mix of modest job growth and cooling wage pressures could fuel a breakout toward new highs. Conversely, a weak labor print or re-accelerating inflation signals could revive recession fears and reintroduce downside volatility.
| Weekday | Event | Expectations / Previous Data | Expected S&P 500 Move |
|---|---|---|---|
| Thu, Sep 4 | ADP Employment Change (Aug) | Forecast: +104K · Prev: +104K | Bullish: +0.3% to +0.6% if ADP ≥ 140K (labor soft-landing narrative). Bearish: −0.3% to −0.8% if ≤ 60K (growth scare). |
| Thu, Sep 4 | ISM Services PMI (Aug) | Forecast: 51.0 · Prev: 50.1 | Bullish: +0.4% to +0.8% if ≥ 52 with firm new orders. Bearish: −0.5% to −1.0% if ≤ 49.5 (contraction signal). |
| Thu, Sep 4 | Balance of Trade (Jul) | Forecast: USD −77.7B deficit · Prev: USD −60.2B | Bullish: +0.1% to +0.3% if deficit narrows materially vs. forecast. Bearish: −0.1% to −0.3% if deficit widens sharply. |
| Fri, Sep 5 | Nonfarm Payrolls (Aug) | Forecast: +75K · Prev: +73K | Bullish: +0.7% to +1.3% if 50–100K with tame wages (cut-friendly “Goldilocks”). Bearish: −1.0% to −1.8% if < 25K (hard-landing) or > 150K with hot wages (rate fears). |
| Fri, Sep 5 | Unemployment Rate (Aug) | Forecast: 4.2% · Prev: 4.2% | Bullish: +0.3% to +0.7% if ≤ 4.1% with soft wages. Bearish: −0.4% to −0.9% if ≥ 4.3% and weak payrolls (trend deterioration). |
| Fri, Sep 5 | Avg. Hourly Earnings (MoM, Aug) | Forecast: +0.3% MoM (YoY 3.9%) · Prev: +0.3% MoM | Bullish: +0.4% to +1.0% if ≤ 0.2% MoM / YoY cools. Bearish: −0.6% to −1.2% if ≥ 0.4–0.5% MoM or YoY re-accelerates. |