Market Recap
With the Indicator trending lower, investor enthusiasm for AI appears to be fading. Despite decent earnings from NVIDIA, the ES future slipped after the close and NVIDIA stock dropped around 3%—a smaller move than the ±6% implied by options. The decline reflected concerns over weaker-than-expected data center revenue growth, ongoing geopolitical risks tied to China export restrictions, and doubts about the sustainability of AI-driven demand. With valuations already stretched and implied volatility high, even strong headline numbers triggered profit-taking. Slowing revenue momentum, regulatory overhangs, and mounting “AI bubble” concerns weighed on sentiment and pushed the stock lower.
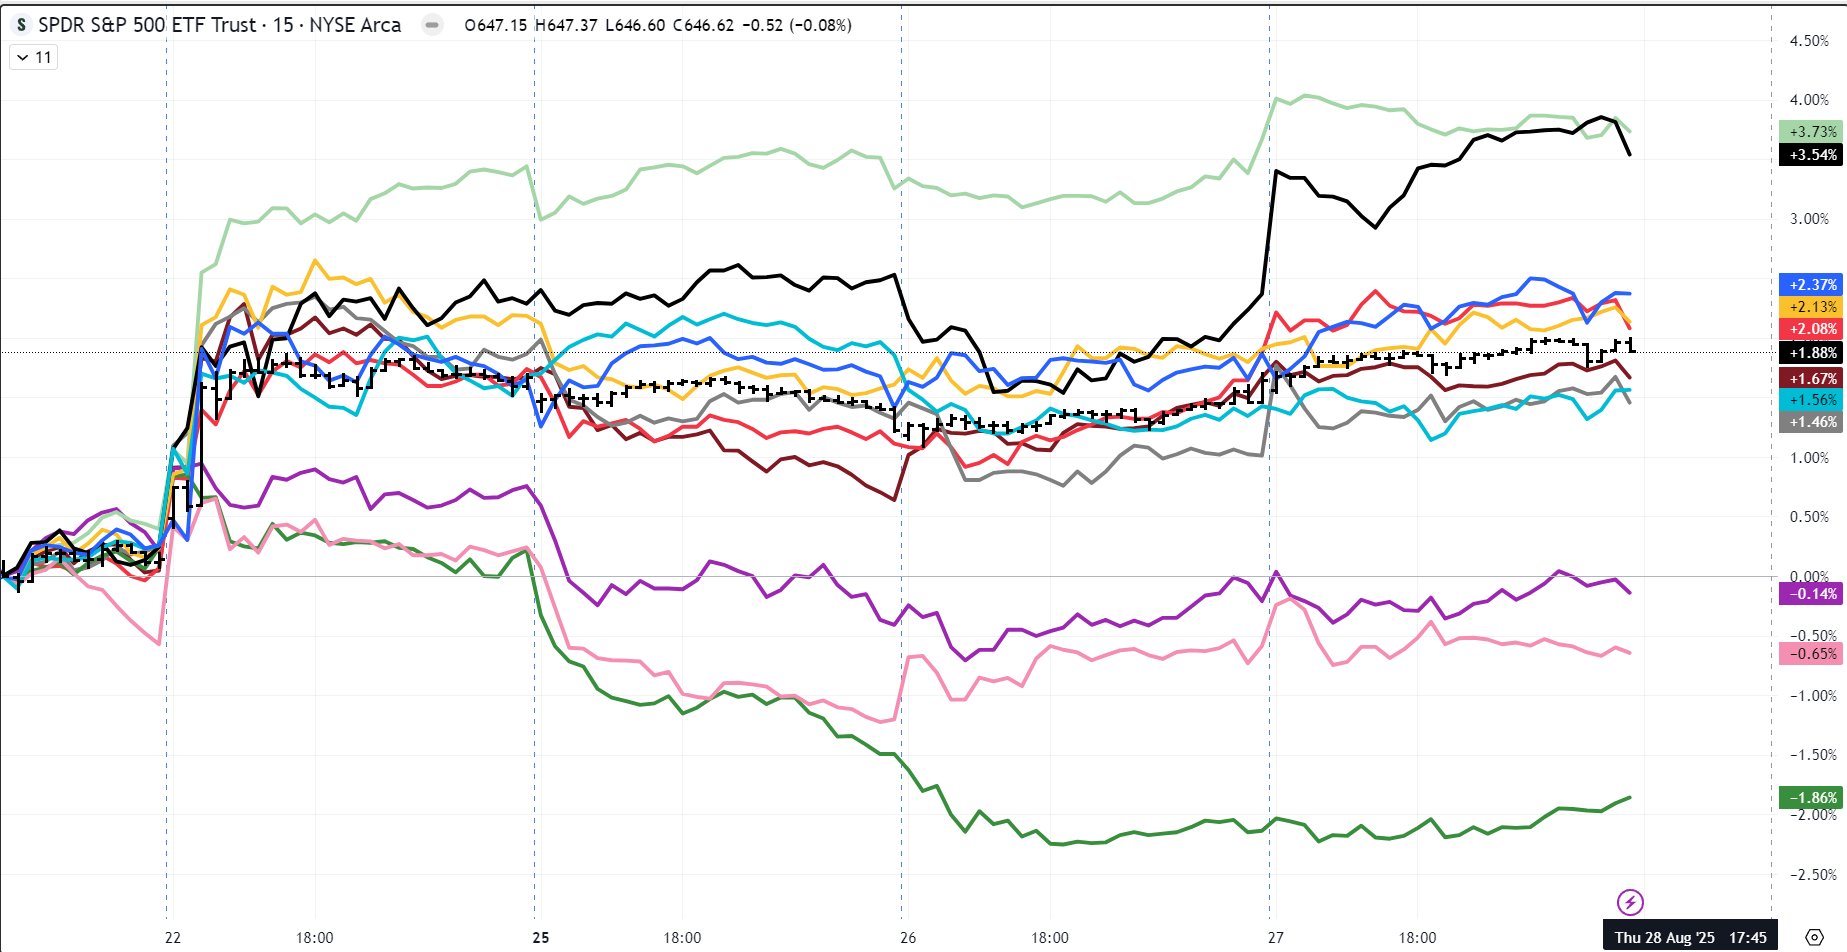
The clear winner yesterday was once again the Russell 2000, underscoring that the so-called “Big Beautiful Rotation”—driven by anticipated rate cuts—remains in motion.
Sector Rotation
The market of recent days is best described as a potential Bullish Impulse following a Bearish one: the ES trades sideways on light volume, while the Big Beautiful Rotation out of Big Tech into Value and Small-Caps continues. As a result, the S&P drifts sideways, the Nasdaq edges lower, and the Russell trends higher.
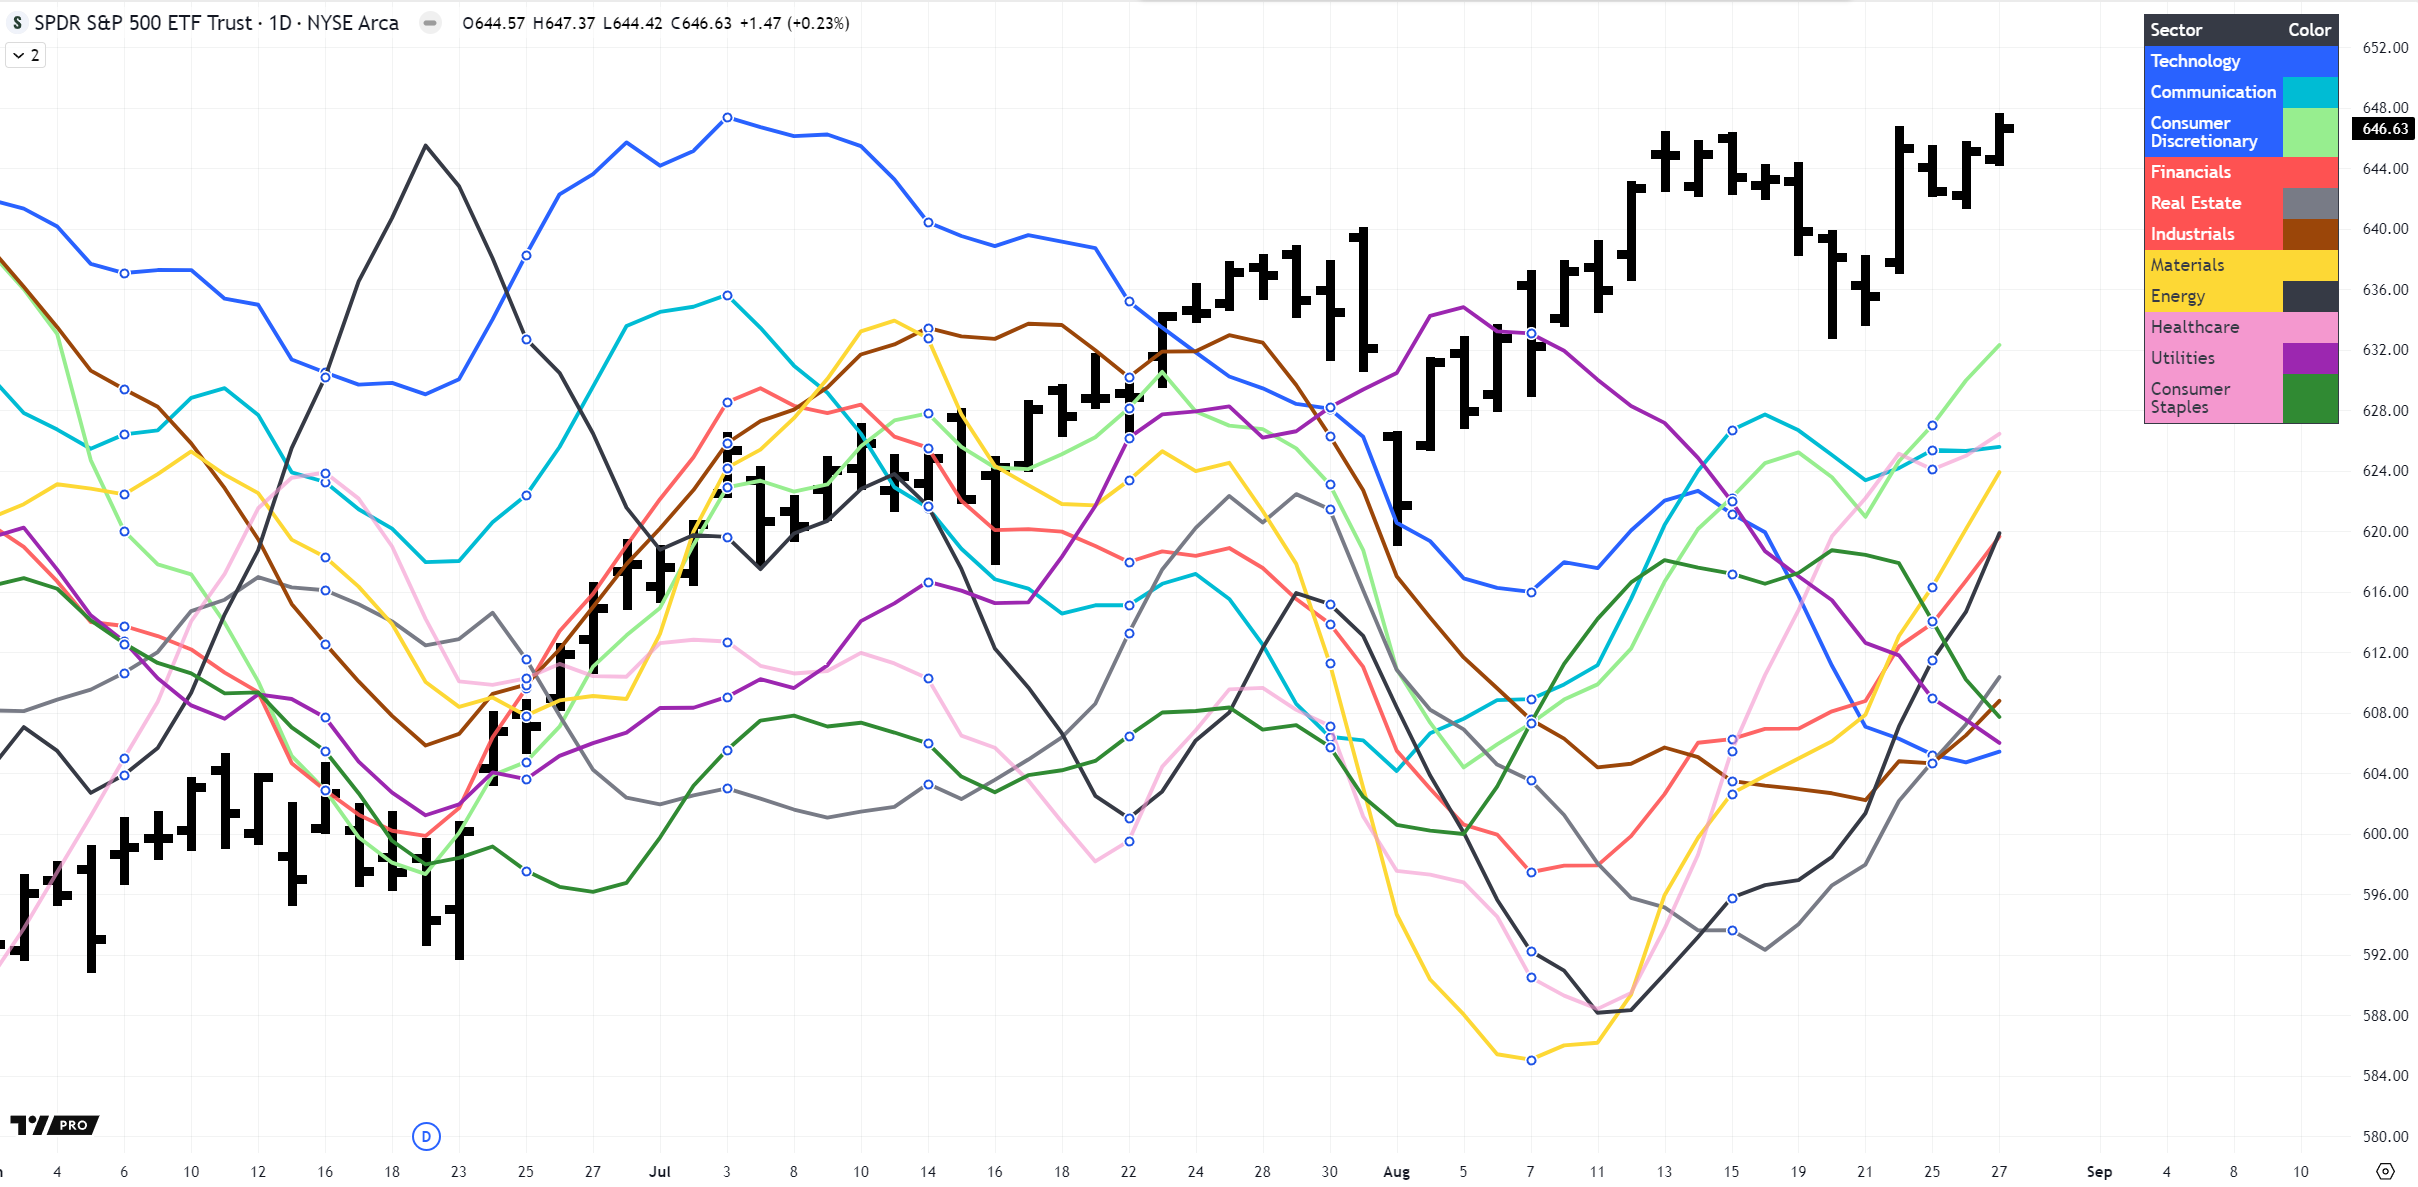
Energy, Materials, Financials, Real Estate, Industrials, and Consumer Cyclicals show the strongest momentum, while Utilities, Staples, and Technology are losing steam. Healthcare seems to have peaked for now, while Technology may be bottoming. These rotational dynamics are most visible on daily charts but can also be observed intraday.
Market Outlook
Despite a pick-up in daily volatility, NVIDIA earnings failed to spark a directional move. Markets are transitioning from AI hype to data-driven dynamics. The key focus now is Friday’s release of the July PCE inflation report, the Fed’s preferred inflation gauge. Consensus expects Core PCE YoY at 2.7%, headline PCE MoM at 0.2%, and core PCE MoM at 0.3%. With futures already pricing nearly a 90% chance of a September rate cut, deviations from these expectations could significantly shift market sentiment:
Below expectations (softer inflation)
- Equities: Rally, led by rate-sensitive sectors (Tech, Real Estate, Utilities)
- Bonds: Yields fall as dovish bets strengthen
- USD: Weakens on lower rate outlook
- Gold: Gains on lower real yields and weaker dollar
In line with expectations (2.7% YoY, 0.2–0.3% MoM)
- Equities: Mildly supportive, focus stays on September cut
- Bonds: Yields stable to slightly lower
- USD: Neutral to modestly weaker
- Gold: Steady with upside bias
Above expectations (hotter inflation)
- Equities: Sell-off, especially in high-duration growth stocks
- Bonds: Yields rise as rate-cut odds fade
- USD: Strengthens on hawkish shift
- Gold: Pressured lower by stronger dollar and higher real yields
Sources:
- Investopedia – PCE Inflation July Preview
- Financial Times – Will US inflation data support investor hopes of a rate cut?
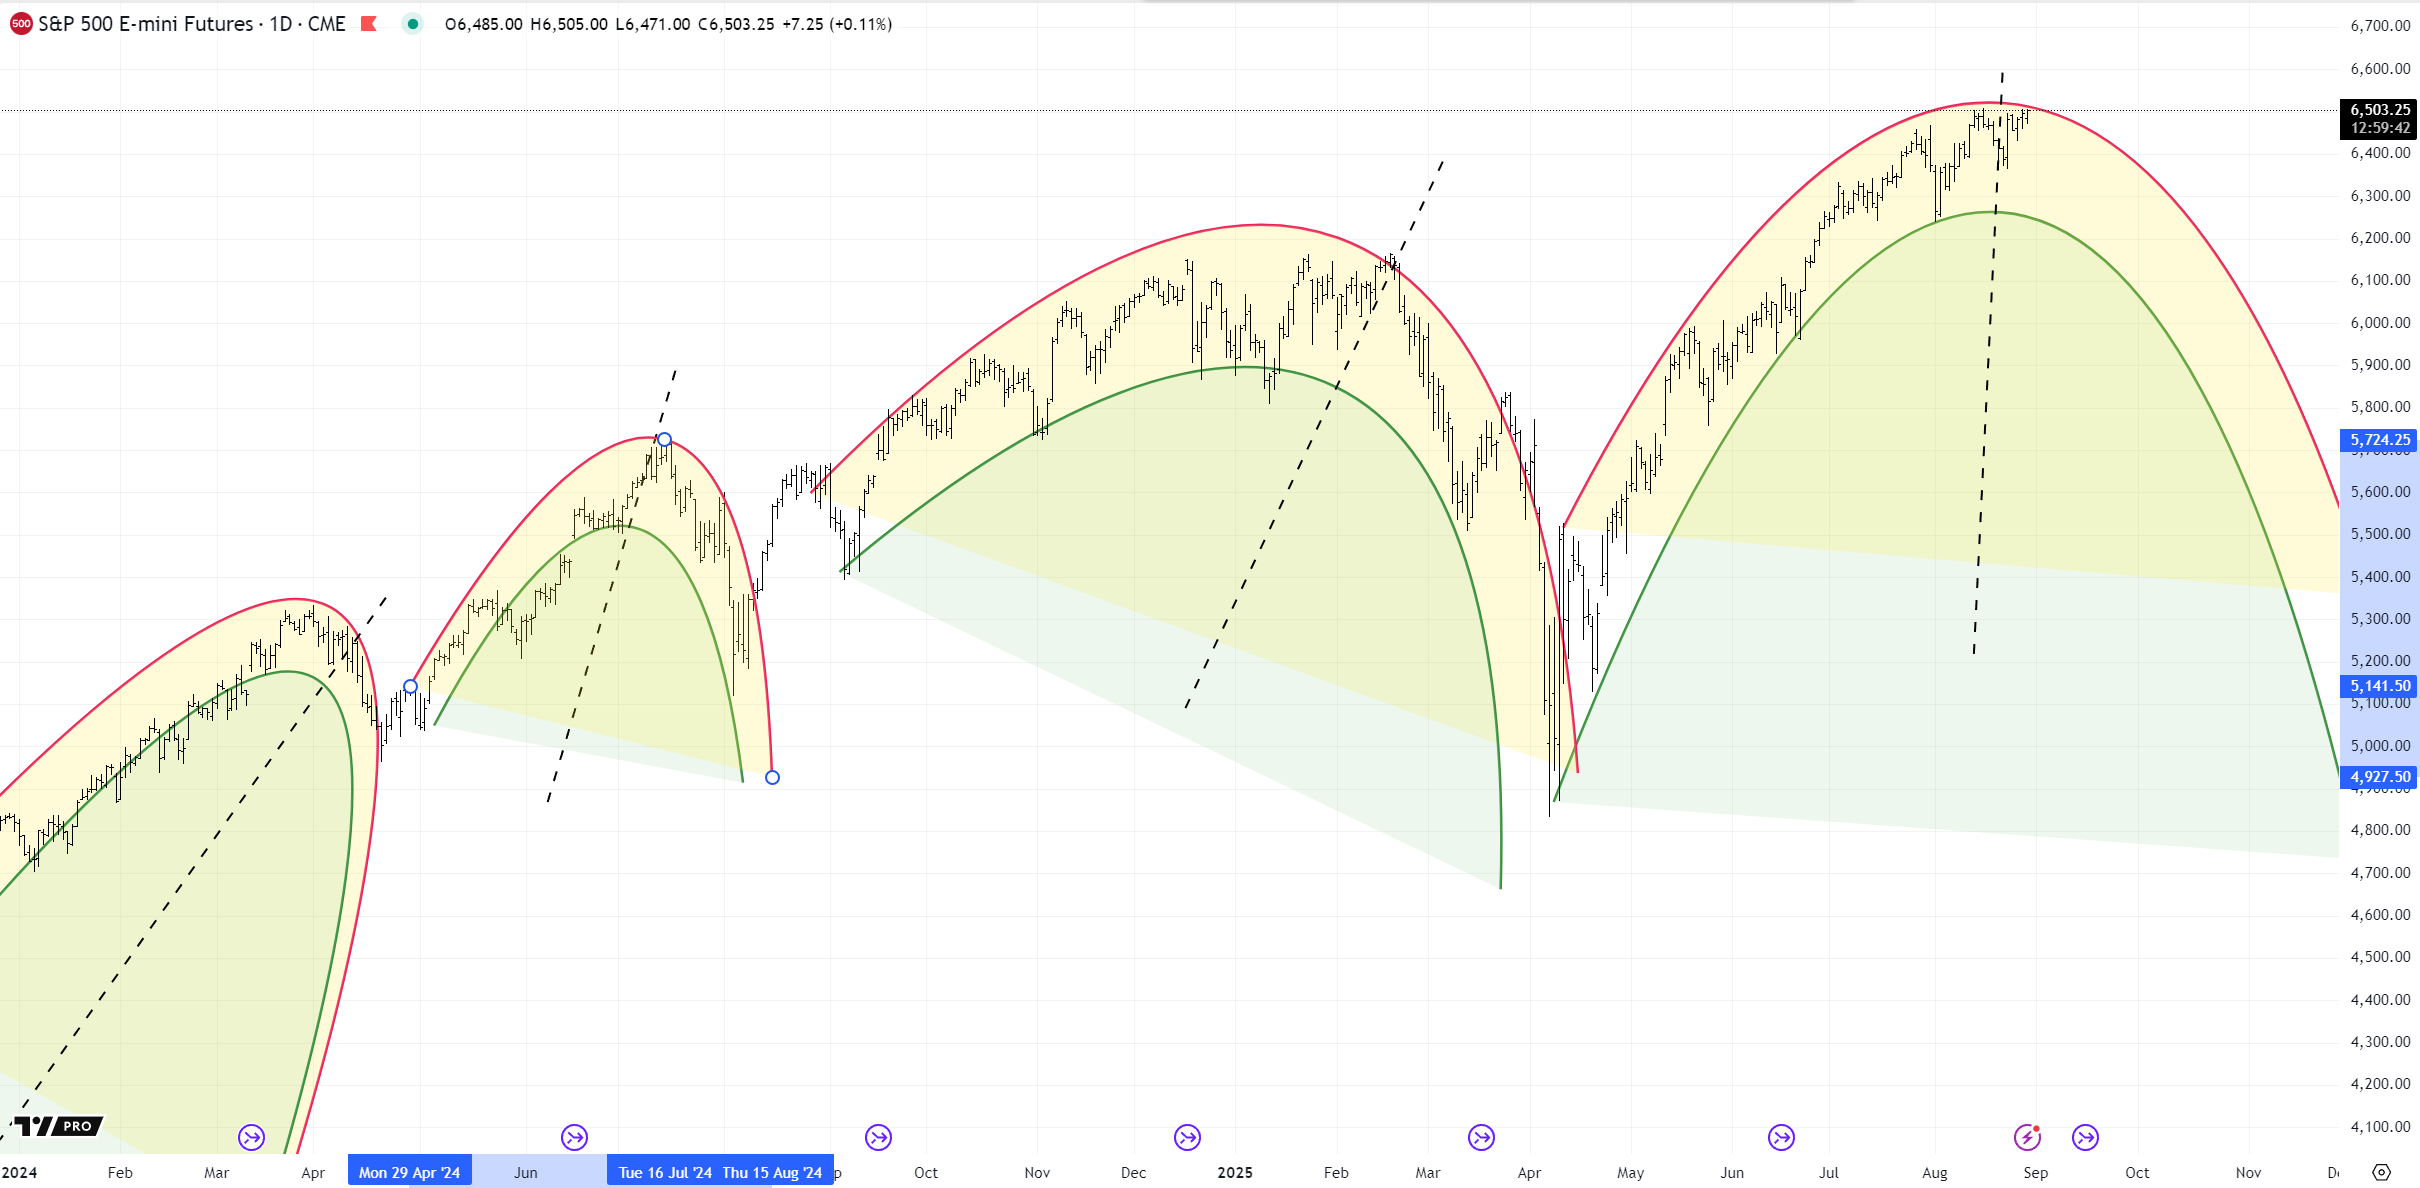
PS: I wanted to share this thought experiment simply to open the mind to potential scenarios shaped by the cyclical nature of markets. It is not the most likely outcome at this stage, but neither can it be ruled out. The last fitted cycle, in particular, remains highly uncertain until we see a clear lower pivot in the ES.