Market Analysis
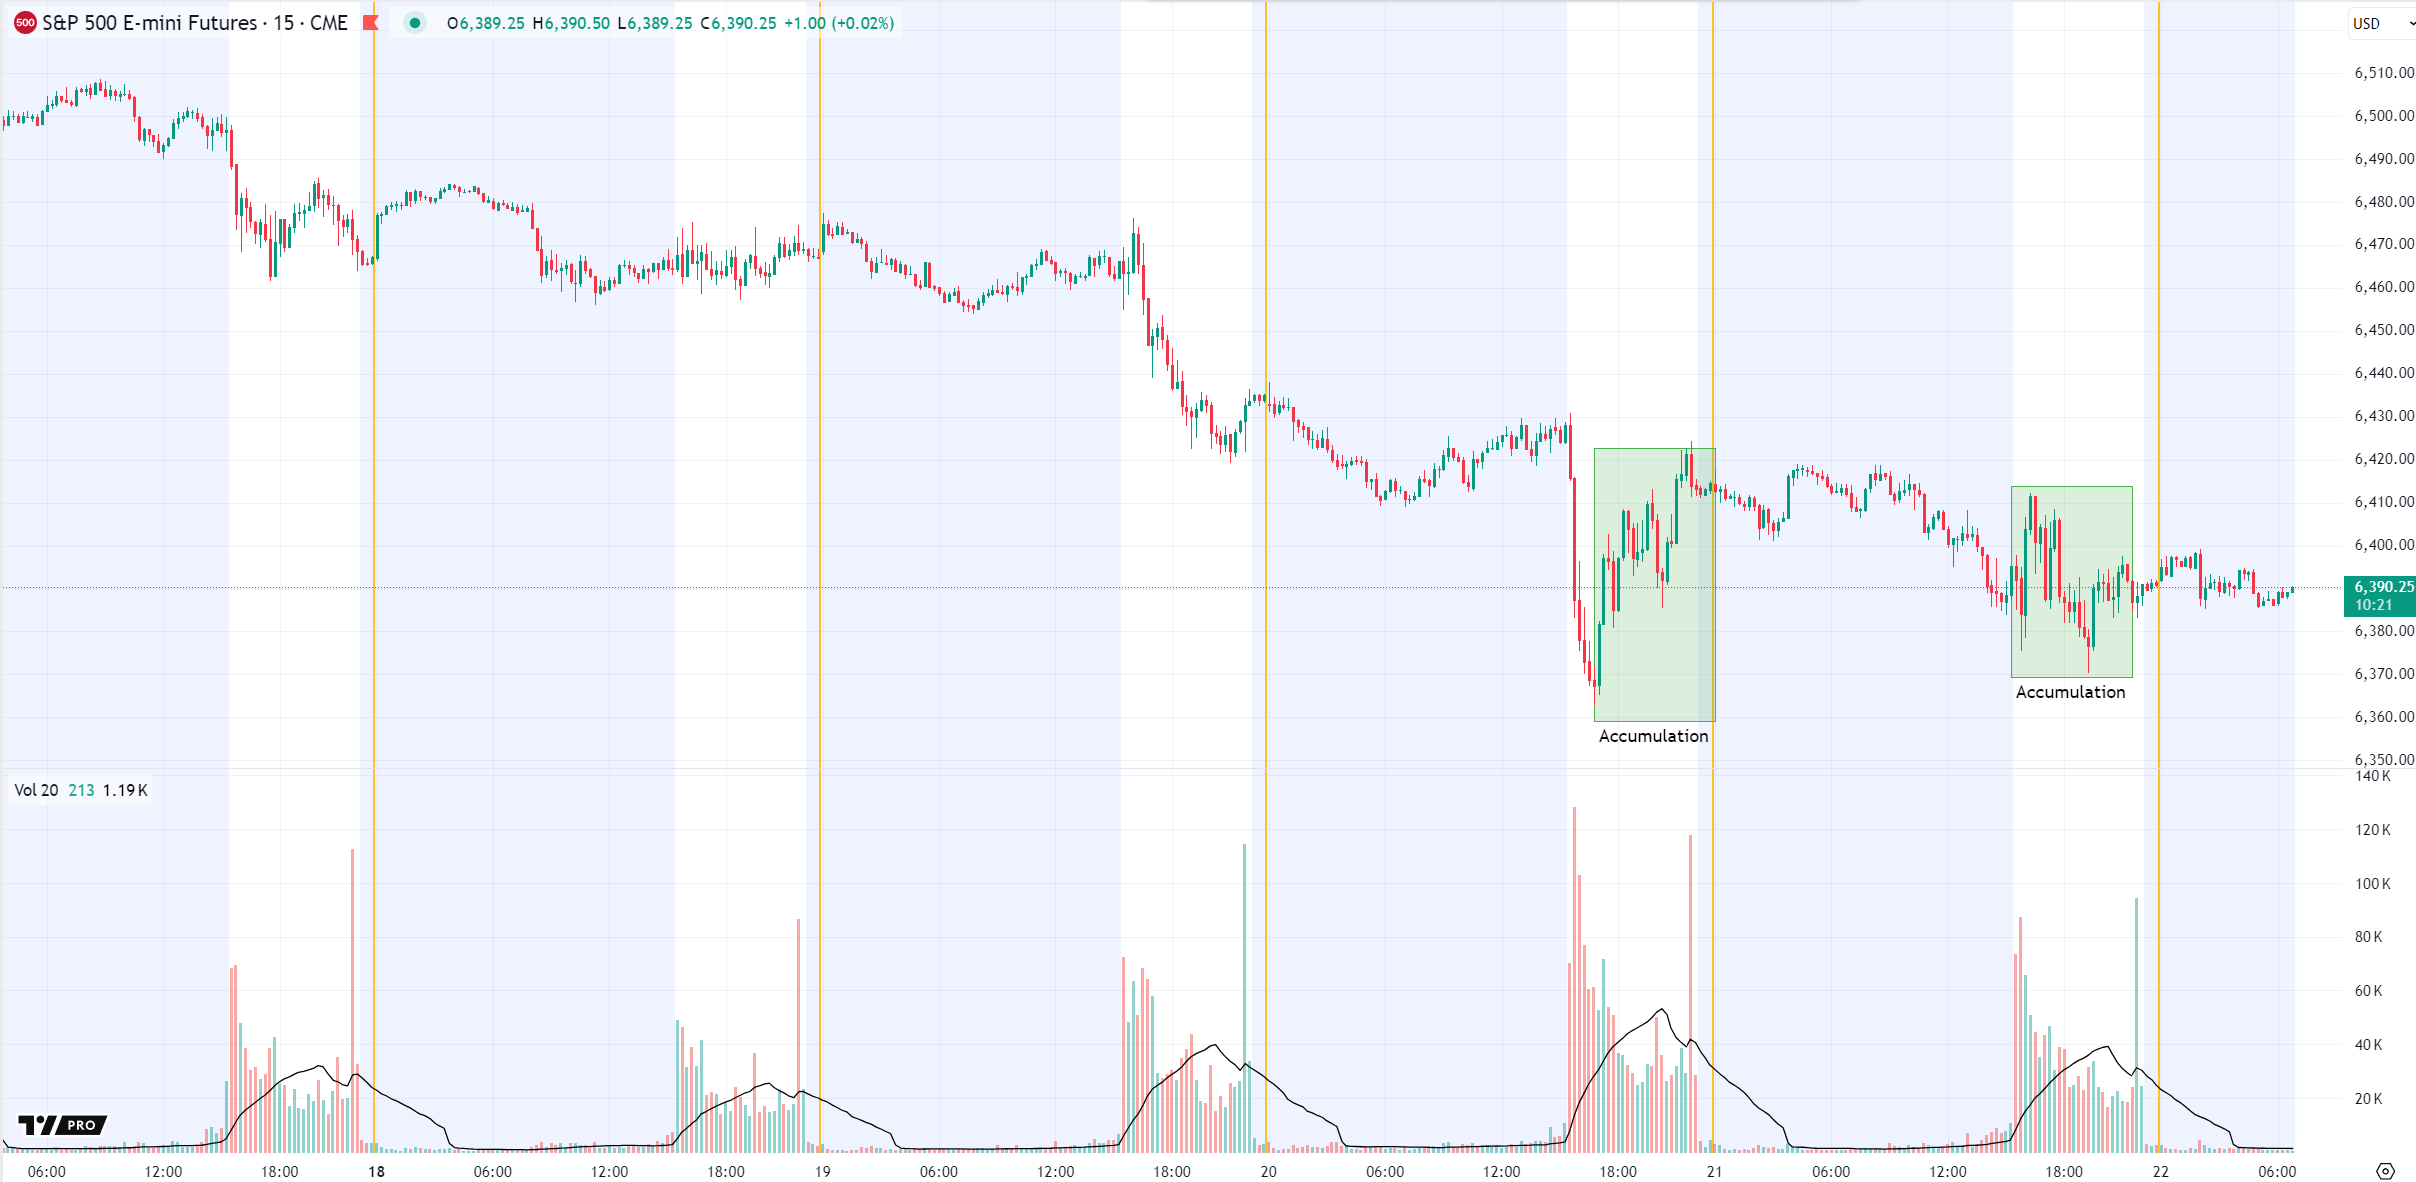
The SP500 Indicator weakened further and, given the current uncertainty, may already be turning slightly red. Beneath the surface, however, a potential Bullish Impulse was detected, suggesting that yesterday’s session saw quick accumulation. The daily ES candle printed an Inside Bar, avoiding a new low. Based on the SP500 Indicator and current volatility and price-action structures, a breakout appears likely today, with Jackson Hole serving as the potential trigger. The combination of a Bullish Impulse and short-term whipsaw patterns in ES—likely accumulations—suggests that informed money is preparing for an upside move.
Sector Rotation
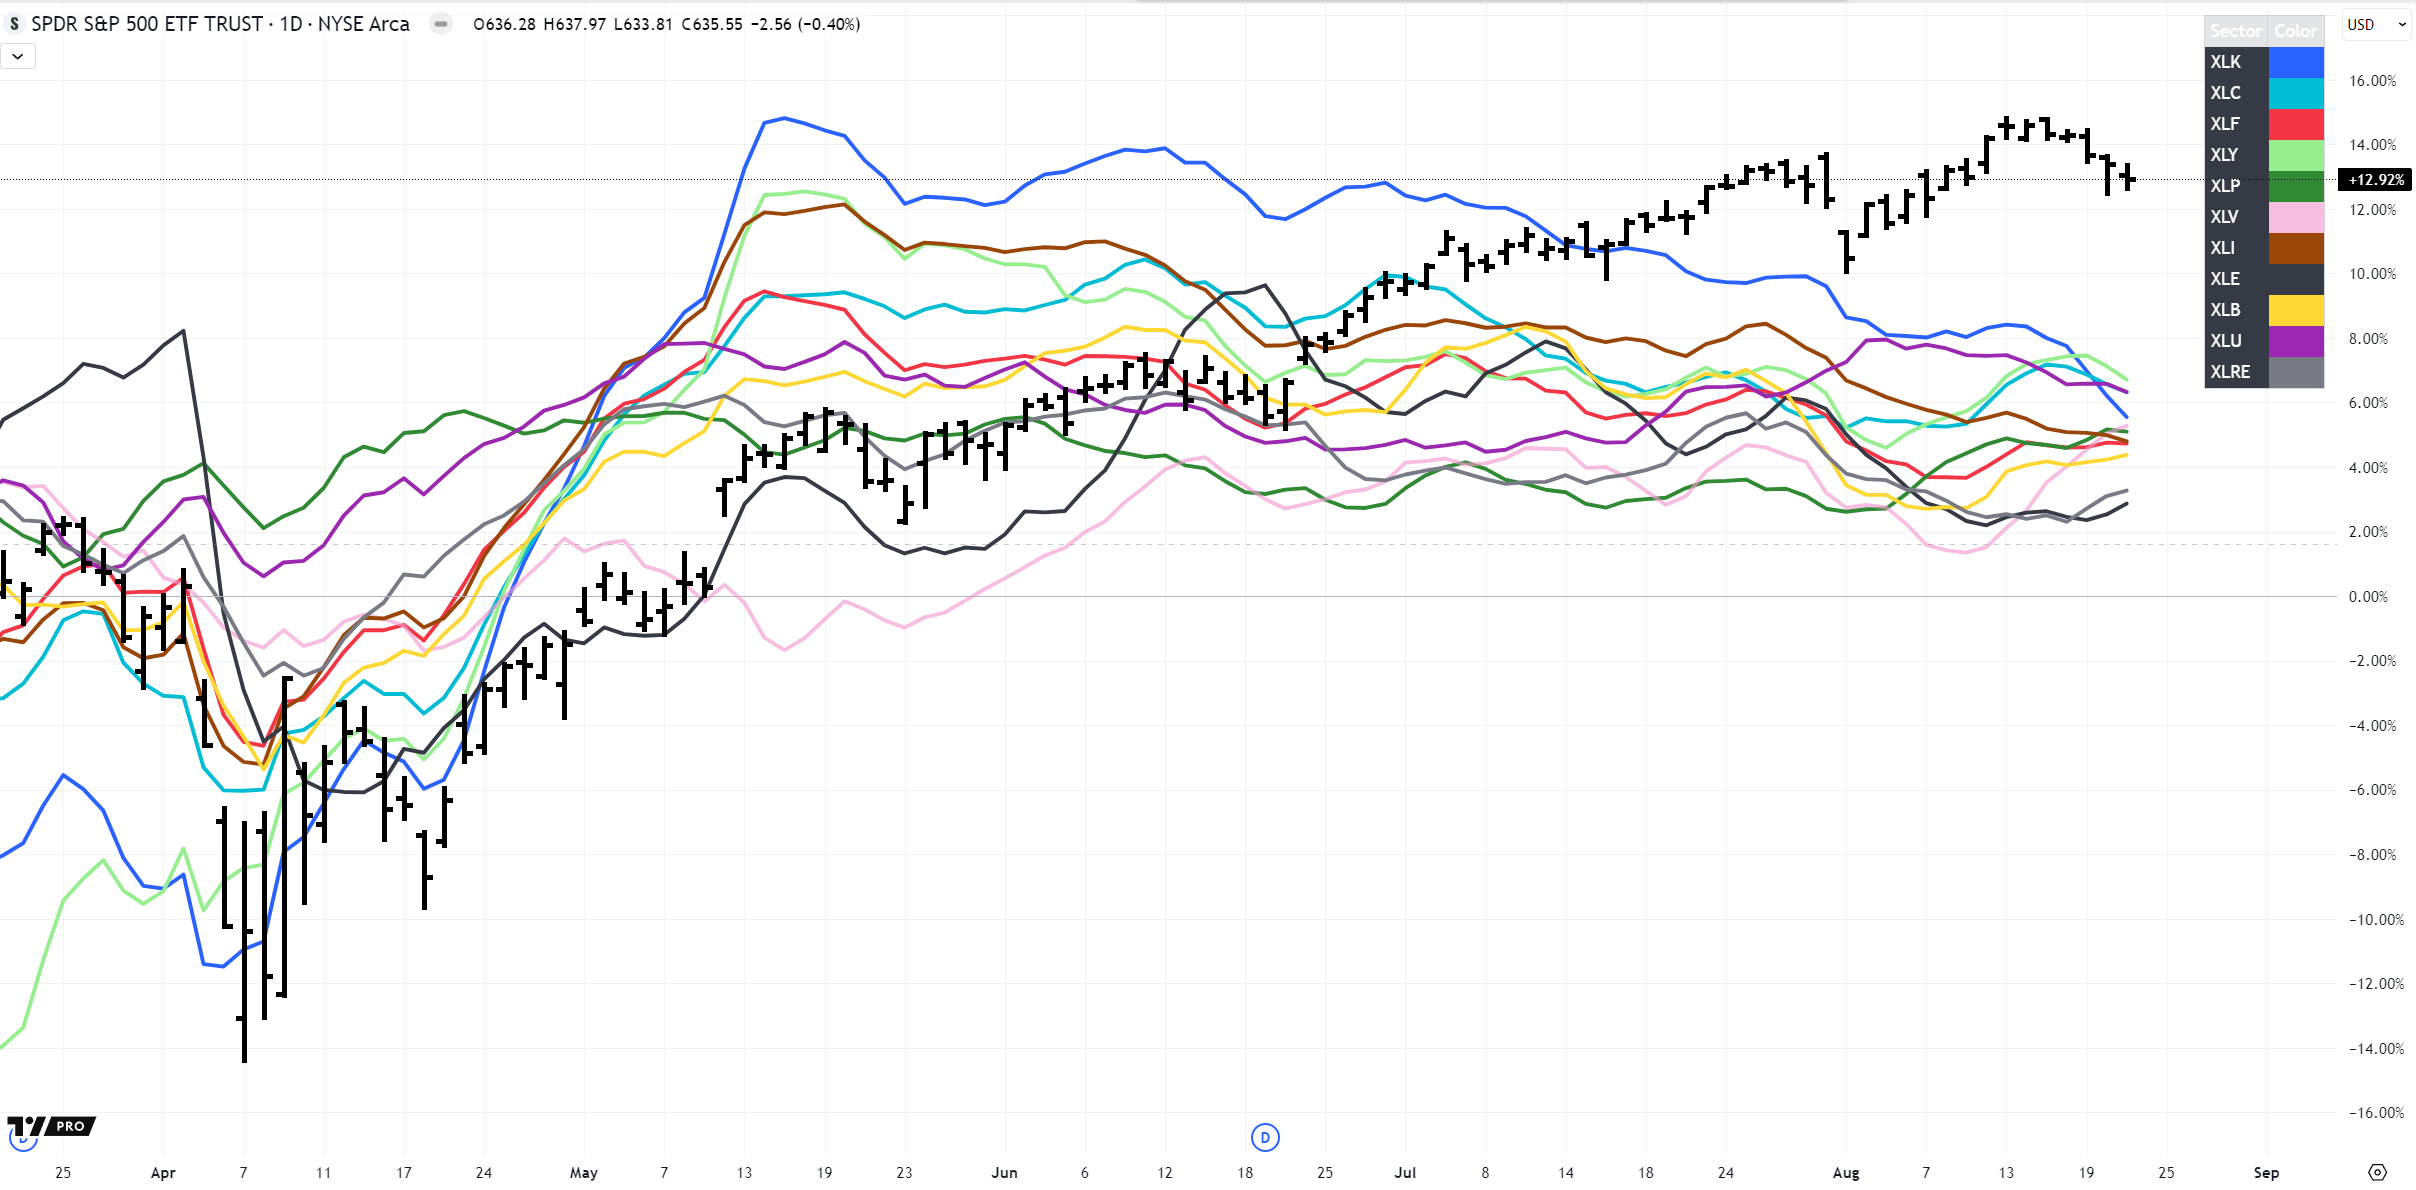
Defensive sectors continue to lead over technology, with Healthcare outperforming both Real Estate and Energy. Financials and Consumer Staples remain neutral. This defensive, risk-off stance could quickly rotate back into risk-on if the Fed delivers dovish signals.
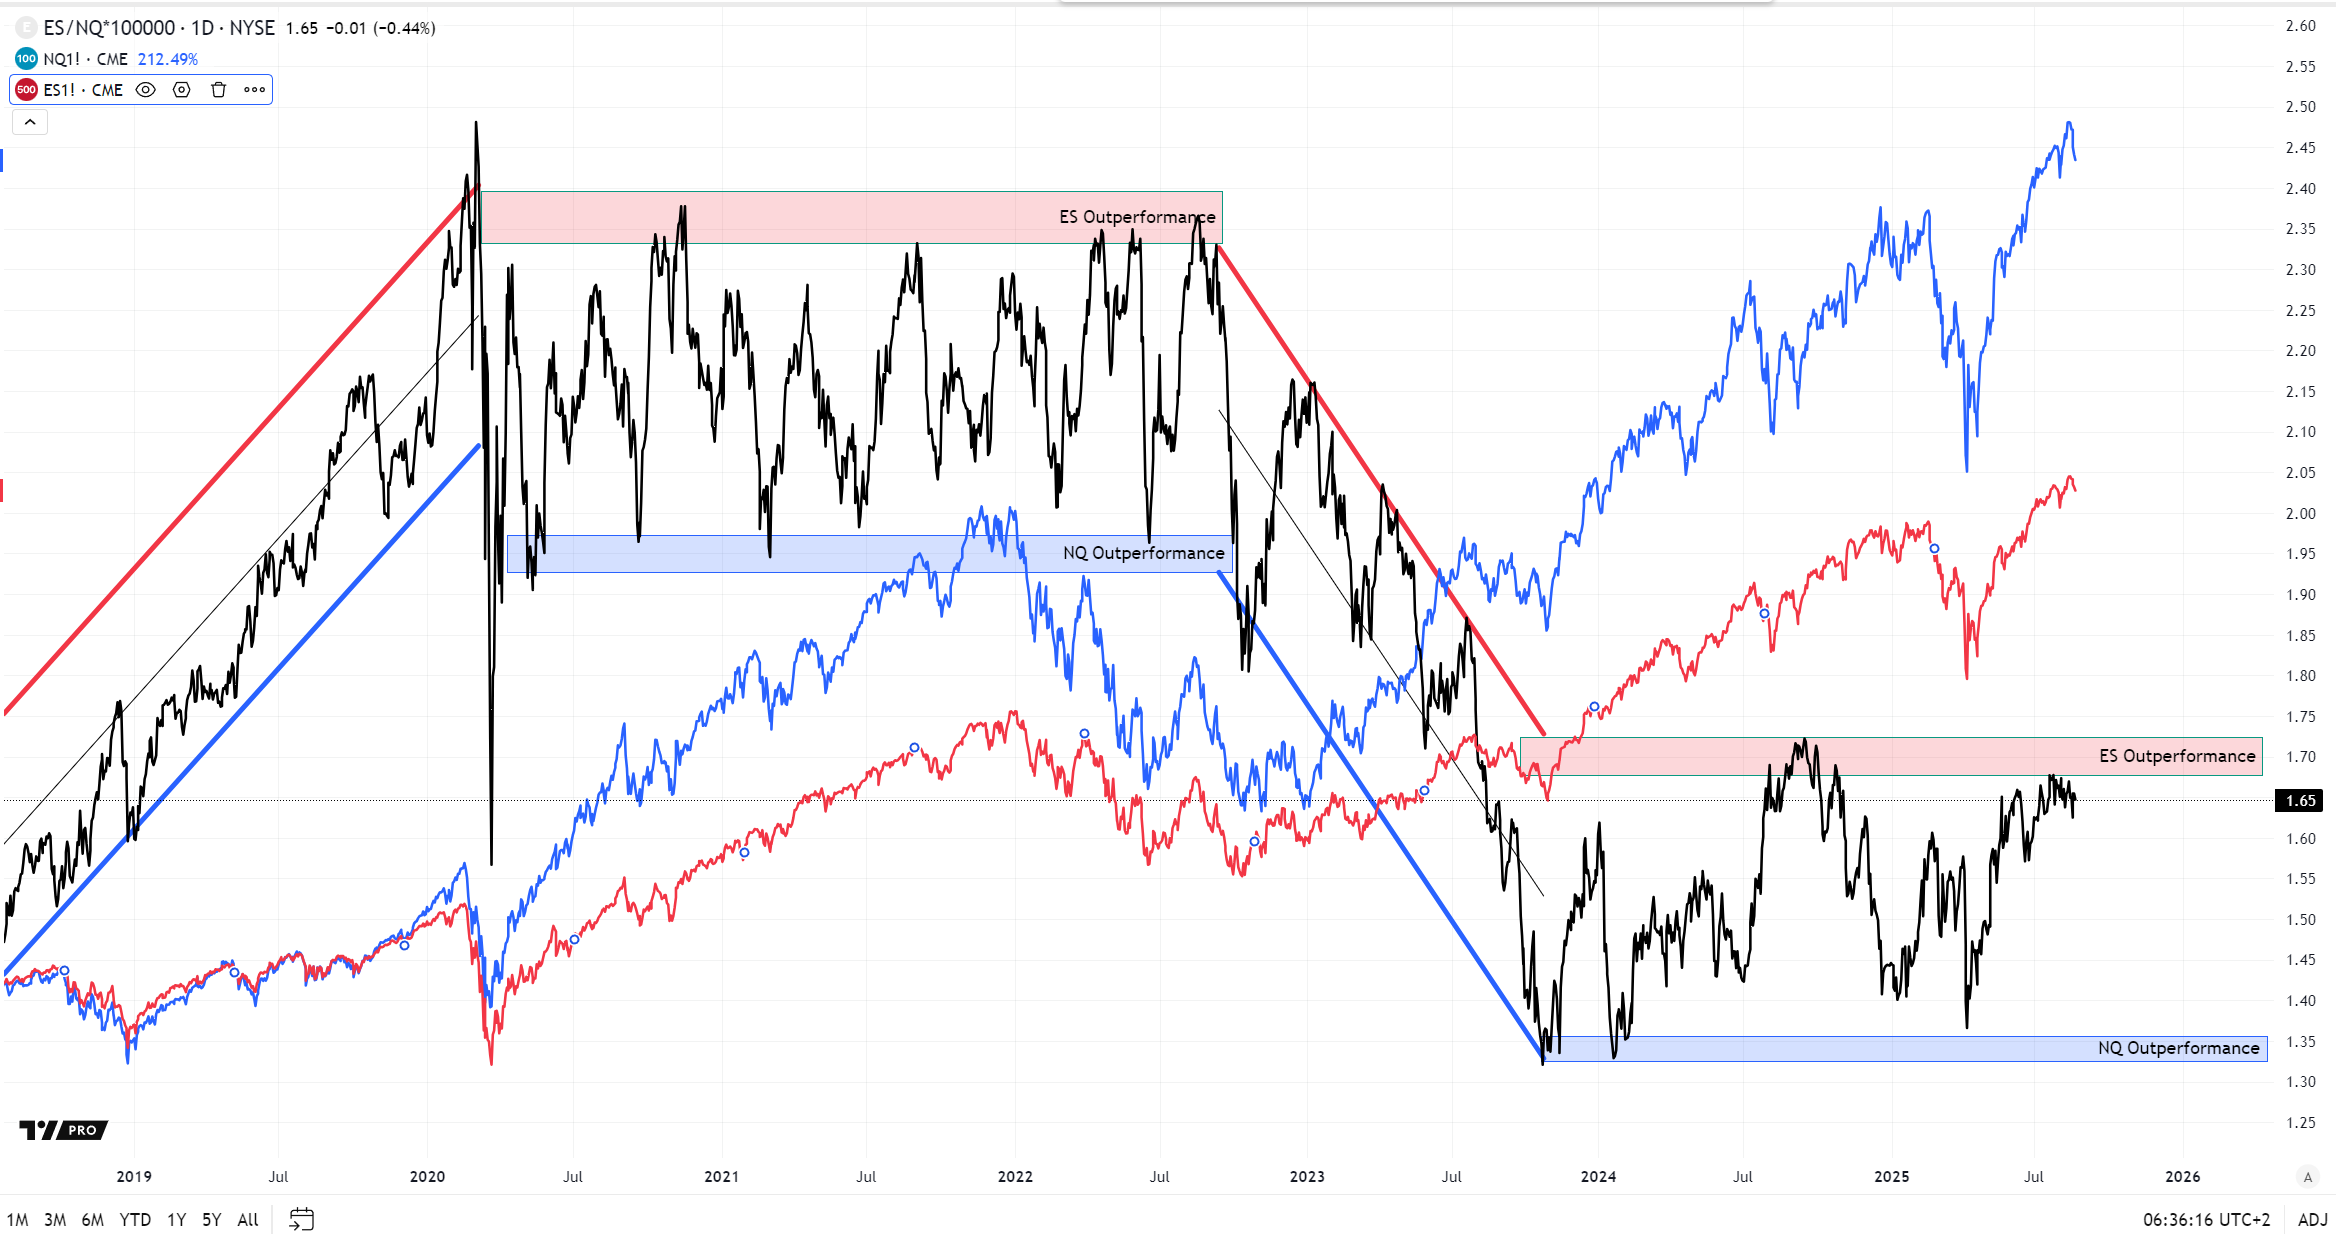
The shift away from tech is also reflected in ES outperforming NQ.
Jackson Hole Outlook
1. Dot Plot and Policy Path – The June SEP pointed to a median year-end funds rate of 3.9%, implying two cuts in 2025, followed by gradual normalization to 3.6% in 2026 and 3.4% in 2027. Inflation is still projected at 3.0% for 2025, while unemployment is expected at 4.5%. The Fed acknowledges disinflation progress, but slower than markets desire.
-
FOMC Member Sentiment – Fed officials remain divided. Kashkari and Daly see scope for two or more cuts this year, possibly starting in September, while Bostic expects only one. Williams highlights tariff-related inflation risks, urging caution, whereas Bowman and Waller favored easing as early as July. This split underscores the tension between hawkish caution and dovish urgency.
-
Jackson Hole Focus – While the official theme centers on labor markets, demographics, and productivity, Powell’s speech at 10:00 a.m. ET will dominate attention. Markets expect him to re-anchor the Fed’s framework toward price stability, moving away from the flexible-average inflation targeting of the early 2020s. His degree of commitment to near-term cuts—or insistence on data dependence—will guide the next market phase.
-
Market Implications for ES Futures – Options price in a ±0.8% weekly move, but thin August liquidity could amplify swings. A dovish tilt highlighting labor risks and discounting tariff effects could fuel a 1–2% ES rally, while a hawkish stance reasserting inflation vigilance could drag futures down by a similar magnitude. Whipsaw volatility around Powell’s remarks is the baseline expectation, with equities, yields, and the dollar all moving in tandem with his tone.
Possible Market Scenarios: Bull Case: Run up and retest the 6450 resistance with possible Head-and-Shoulders formation, which could play out bearish in the mid-term future. Bear Case: If the market make a new low today, there is possibility of a cascade-effect to quite some lower levels, e.g. a Pullback to first BUY-Zone around 6200 or a prolonged choppy Sideways-Market.